


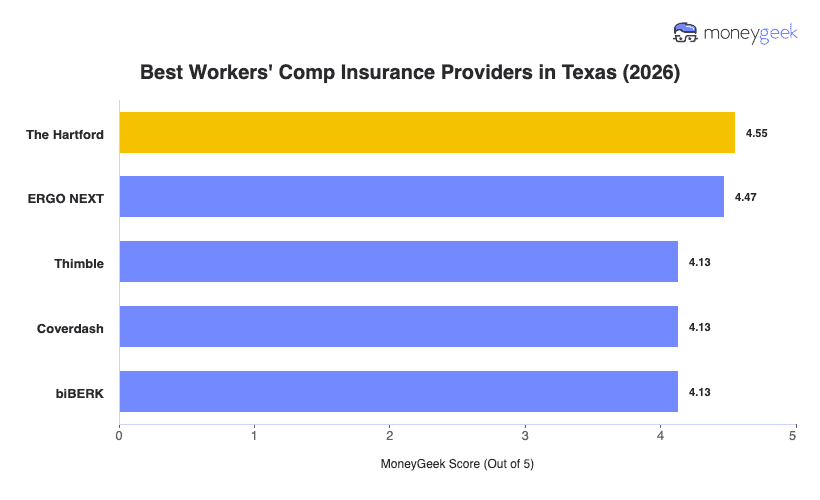
In my study, The Hartford tops my list as the best workers' compensation insurance carrier in Texas. It's one of two providers with the lowest average rate of $59 per month per employee on average, with ERGO NEXT being the other one. The Hartford is an excellent choice if you want to solid claims handling support for an affordable rate. ERGO NEXT could be a better match if you want to combine affordability with same day coverage and a self-service platform.
Best Workers' Comp Insurance in Texas (2026)
With rates as low as $8 monthly per employee, The Hartford, ERGO NEXT and Thimble have the best workers' comp insurance in Texas.
With our matching tool, MoneyGeek can connect you to top Texas workers' comp insurance providers and help you find your ideal coverage.
Select state
Updated: August 27, 2026
Advertising & Editorial Disclosure
Best Workers' Comp Insurance Companies in Texas
| The Hartford | 4.55 | $59 | 2 | 3 |
| ERGO NEXT | 4.47 | $59 | 1 | 6 |
| Thimble | 4.13 | $65 | 8 | 9 |
| Coverdash | 4.13 | $75 | 7 | 1 |
| biBERK | 4.13 | $70 | 8 | 8 |
MoneyGeek analyzed workers' comp insurance rates and provider performance across Texas using small business profiles with one to four employees spanning 408 major industries. The $64 a month Texas state average is derived from this full 408-industry dataset and is not limited to the providers reviewed on this page. Companies earn up to five points in each category in our scoring system. We then use a weighted average of these category scores to calculate an overall MoneyGeek score out of five.
- Affordability (55%): Based on average payroll for the most common employee code per industry and state classification, priced per employee for a one to four employee business.
- Customer Experience (35%): Evaluates buying (20%), which covers quote access, pricing accuracy and sales support; policy management (30%), which covers payroll reporting, audits, billing and loss control; and claims (50%), which covers FNOL speed, adjuster support, medical access, wage replacement and dispute handling.
- Coverage Options (10%): Assesses coverage completeness (35%), including employers' liability and wage and medical reimbursement; policy flexibility and endorsements (25%); eligibility, state and industry breadth (20%); and policy terms, limits and exclusions (20%).

The Hartford
Best Workers' Comp Insurance in Texas
MoneyGeek Rating
4.5/ 5
4.7/5Affordability Score
4.3/5Customer Experience Score
4.1/5Coverage Score
Average Monthly Cost
$59Claims Processing Score
4.1/5Policy Management Score
4/5Buying Process Score
4/5

ERGO NEXT
Best Texas Workers' Comp Insurance: Runner-Up
MoneyGeek Rating
4.5/ 5
4.7/5Affordability Score
4.3/5Customer Experience Score
3.8/5Coverage Score
Average Monthly Cost
$59Claims Processing Score
4/5Policy Management Score
4.1/5Buying Process Score
4.4/5
Cheapest Workers' Comp Insurance Companies in Texas
The Hartford and ERGO NEXT have the cheapest workers’ compensation rates in 24 of the 25 Texas industries we analyzed. ERGO NEXT leads on price in 14 industries, while The Hartford offers the cheapest rates in 10. biBerk ranks lowest for childcare businesses at about $22 monthly per employee.
The Hartford is generally the more affordable option for lower-risk, office-based industries, including financial services ($8 a month), consulting ($11), real estate ($12) and tech/IT ($23). ERGO NEXT has lower pricing in industries with greater physical labor or workplace exposure, like cleaning services ($66), construction ($138) and transportation ($174).
| Financial Services | The Hartford | $8 | $96 |
| Beauty, Body & Wellness Services | ERGO NEXT | $9 | $108 |
| Marketing & Communications | ERGO NEXT | $9 | $108 |
| Consulting Services | The Hartford | $11 | $132 |
| Real Estate & Property Services | The Hartford | $12 | $144 |
| Other Professional Services | The Hartford | $15 | $180 |
| Childcare Services | biBERK | $22 | $264 |
| Tech/IT | The Hartford | $23 | $276 |
| Food & Beverage | ERGO NEXT | $24 | $288 |
| Hospitality, Travel & Tourism | The Hartford | $24 | $288 |
| Healthcare & Medical | The Hartford | $26 | $312 |
| Retail & Product Rental | The Hartford | $30 | $360 |
| Nonprofit & Associations | The Hartford | $34 | $408 |
| Pet Care Services | ERGO NEXT | $36 | $432 |
| Education | ERGO NEXT | $38 | $456 |
| Fitness Services | ERGO NEXT | $41 | $492 |
| Repair & Maintenance | ERGO NEXT | $43 | $516 |
| Arts, Media & Entertainment | ERGO NEXT | $56 | $672 |
| Recreation & Sports | ERGO NEXT | $65 | $780 |
| Cleaning Services | ERGO NEXT | $66 | $792 |
| Manufacturing | The Hartford | $86 | $1,032 |
| Agriculture & Natural Resources | ERGO NEXT | $95 | $1,140 |
| Wholesale & Distribution | ERGO NEXT | $111 | $1,332 |
| Construction & Contracting | ERGO NEXT | $138 | $1,656 |
| Transportation & Logistics | ERGO NEXT | $174 | $2,088 |
How to Get the Best Workers' Comp Insurance in Texas
Follow these steps to get the right workers' comp insurance that fits your small business in Texas.
- 1
Confirm Texas Coverage Requirements
Most private employers in Texas can choose whether to carry coverage. Workers’ compensation insurance requirements are reserved for public employers and businesses working on certain government contracts. However, not having a policy makes you a nonsubscriber and removes important legal protections if an employee sues after an injury.
- 2
Identify Your NCCI Class Codes Accurately
Texas follows NCCI’s classification system with state-specific exceptions. Match each code to the work your employees perform rather than relying on job titles alone. The code is only a starting point because insurers can use their own approved rating factors, which helps explain why two carriers may quote different premiums for the same payroll.
- 3
Document Payroll, Employee Count and Claims History
Divide payroll by class code and gather loss runs showing previous claims. Separate the wages of employees working on government projects when a contract requires workers’ compensation coverage. Tell the carrier about work performed in other states as well, since a Texas policy may need an endorsement to protect employees who regularly cross state lines.
- 4
Request Quotes from Multiple Licensed Texas Carriers
Compare business insurance quotes using Texas’s workers’ compensation rate guide as another reference point. Look at the final rate for your classifications rather than comparing NCCI loss costs alone. If other insurers will not offer you a policy, Texas Mutual serves as the state’s insurer of last resort.
- 5
Compare on Quality, Not Just Price
Some Texas policies use a certified workers’ compensation health care network. In a network plan, an injured employee generally chooses a treating doctor from the network’s provider list. Without a network, employees usually have more freedom to select their doctor. Compare provider access near your worksites and how clearly each carrier explains the network rules to employees.
- 6
Complete Purchase and Establish Payroll and Audit Reporting
Post Notice 6 and give new employees written confirmation that you provide workers’ compensation coverage. When an injury causes more than one missed workday, send DWC Form-001 to your carrier within eight days. Report a work-related illness or death immediately, and give the employee a copy of the completed form with the state’s rights and responsibilities notice.
- 7
Review at Annual Renewal
Check the audit for payroll assigned to the wrong class code and confirm that the policy still covers every state where employees work. If you end coverage, notify employees within 15 days and file DWC Form-005 with the Division of Workers’ Compensation. Employers that remain nonsubscribers must file the notice each year between February 1 and April 30 and follow separate injury-reporting rules.
Best Workers' Compensation Insurance in Texas: Bottom Line
The Hartford and ERGO NEXT have the best workers' compensation insurance for most Texas employers, tied at $59 a month per employee. Thimble is a competitive third option for businesses that want a digital-first experience at $65 a month. The right choice depends on your industry, claims history, and how much weight you place on claims support versus buying convenience.

LEARN MORE ABOUT TEXAS BUSINESS INSURANCE
You'll need more than workers' comp coverage if you want to make sure your business has enough financial protection. Use the resources below to see our top provider recommendations for other coverages you'll likely need for the best business insurance in Texas.
Texas Workers' Compensation Insurance FAQ
The Hartford and ERGO NEXT tie as the cheapest workers' comp provider in Texas at $59 a month per employee, while The Hartford is our top pick among best workers' comp insurance providers. Here are the five most affordable options in the state:
- The Hartford: $59 a month
- ERGO NEXT: $59 a month
- Thimble: $65 a month
- biBerk: $70 a month
- Coverdash: $75 a month
Texas is the only state where workers' comp insurance remains optional for most private employers, but employers who skip coverage lose legal protections against workplace injury lawsuits and face unlimited liability. Government entities and construction companies working on public projects must maintain coverage.
The cost of workers' compensation insurance in Texas is about $76 per employee monthly for small businesses. Your costs depend on your industry and payroll size. Low-risk industries, like Beauty, Body & Wellness Services, pay an average of $13 per month per employee, while high-risk industries, like Construction & Contracting average $211.
You can get workers' comp coverage in Texas by:
- Purchasing policies from private insurance companies licensed to operate in Texas
- Buying coverage through the Texas Mutual Insurance Company, a policyholder-owned carrier
- Qualifying for self-insurance status if your business meets the state's strict financial requirements
Many business owners compare quotes online or through brokers to get the best rate and compliance support.
Workers' compensation in Texas covers:
- Medical expenses for workplace injuries and occupational illnesses
- Temporary income benefits replacing two-thirds of lost wages during recovery
- Impairment income benefits for permanent disabilities based on medical assessments
- Death benefits for surviving family members of workers killed in workplace accidents
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com