Updated: September 21, 2026

Advertising & Editorial Disclosure

Best Retail Store Business Insurance Companies

After extensive research, these companies are my best business insurance picks for retailers:

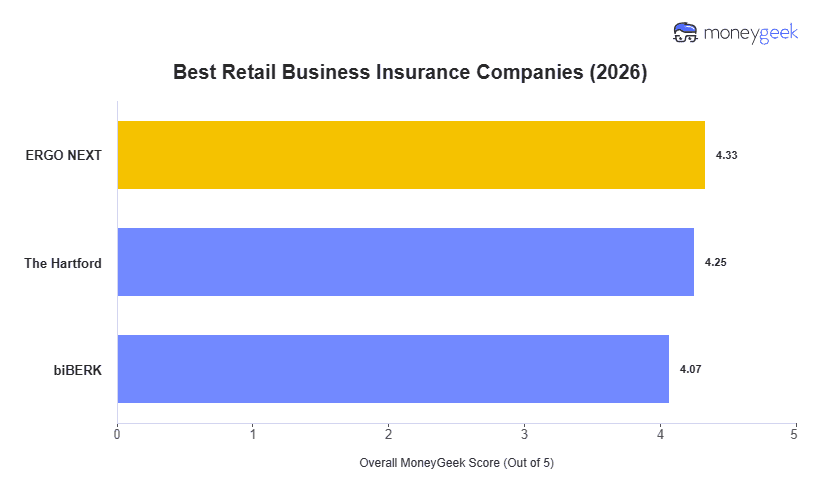
  • Choose if you are a smaller home operation and want low rates: ERGO NEXT
  • Choose if you want the best coverage and claims service: The Hartford
  • Choose if you offer delivery services in-house: biBerk
Featured Partner
The Hartford
The Hartford
  • The Hartford's Spectrum BOP is built for retail, with peak season inventory limits and equipment breakdown coverage included.
  • Retail business insurance from The Hartford averages $121 a month, 6% below the $129 benchmark, ranking second at 4.25 out of 5.
  • Retail business owner's policies from The Hartford bundle general liability, commercial property and business income coverage.
  • Founded in 1810, The Hartford now insures more than 1.5 million small business customers.

*MoneyGeek featured partner. Editorial rankings below are independent of this placement. Rates, rankings and savings comparisons are based on MoneyGeek's independent research and Hartford-reported data as of 2026. Figures are estimates and averages, not a guarantee of any individual quote, premium or discount.

My retail business insurance rankings are based on analysis across 39 retail subindustries and multiple business sizes. I compared five insurers on the factors retail owners care about most. That meant looking at policy costs for real storefront risks like slip-and-fall claims, product liability and inventory loss. I also weighed how broad each provider's coverage options are and how easy it is to buy a policy, manage it and get help when you file a claim.

Each provider was scored on three weighted factors: affordability (50%), customer experience (30%) and coverage options (20%). Customer experience scores incorporate data on buying ease, policy management, claims handling, billing accuracy and dispute resolution. See our full methodology

ERGO NEXT

ERGO NEXT: Best For Most Small Retailers

checkmarkpros
  • Most affordable rates

  • Best online buying process

  • Easy DIY policy management

closecons
  • Low limit maximums for coverage

  • Claims service for complex issues is weaker

  • Multi-location coverage not supported

COMPANY HIGHLIGHTS

ERGO NEXT ranks first overall for retail businesses because of its competitive pricing, straightforward online buying process and easy policy management. In my review, it stood out most for smaller retailers with under 5 employees that need standard coverage without a complicated purchasing experience.

Its main weakness is scalability. Coverage options and limits are less robust for retailers with more property exposure, multiple locations or more complex insurance needs. Their AI and DIY-first customer service also isn't built for the complexity that comes with business growth past the startup phase, so larger businesses are better served elsewhere.

Learn More: ERGO NEXT Business Insurance Review

The Hartford

The Hartford: Best For Coverage and Service

checkmarkpros
  • No coverage limitations with extensive options

  • Best claims service experience

  • Dedicated assigned agents and industry service departments

  • Claims risk management services are included for all customers

closecons
  • Buying and policy management often need an agent

  • Not the most affordable insurer, especially for e-commerce

  • Not available in Alaska and Hawaii

COMPANY HIGHLIGHTS

Finishing at a close second overall, The Hartford is my pick for your retail company if you value coverage and tailored human-to-human service over just having the cheapest rates. While their online tools are lackluster compared to other small online insurers, their edge is their personal touch, with a dedicated industry specialist team and an assigned agent you can build a relationship with as you grow. You also won't be at a loss for coverage, as the provider has built tailored programs for retail with virtually no limitations and added unique perks.

One of the only drawbacks I see for The Hartford is affordability. While it's still generally affordable for the value they provide, it can be a dealbreaker if you're just starting out and need to save every penny. Also, if you prefer less human interaction when dealing with insurance, it offers a few DIY options, making other competitors a better fit if that is a dealbreaker.

Learn More: The Hartford Business Insurance Review

biBerk

biBerk: Best For Retailers With In-House Delivery

checkmarkpros
  • Offers commercial auto in-house

  • Fairly simple buying process for most policies

  • Agent support is available as a secondary option, along with DIY tools

closecons
  • Rates are on average for all policies

  • General Liability & BOP policies are only available in 28 states

  • Smaller coverage selection and limit maximums

  • Online buying has technical issues and is slow

COMPANY HIGHLIGHTS

biBerk's value is highly specific to a smaller set of retailers, specifically those seeking coverage for in-house delivery services for their products. This is because they are one of the few business insurers that offer commercial auto insurance directly in all states, along with most of the common coverages small businesses need. They also offer a good balance of agent services and DIY policy management.

While their rates are in line with the industry average for business insurance, bundling with them can make your total policy costs more affordable. Even with this benefit, though, their limited options, endorsements and general policy selection are limited and really only ideal for startups or those with limited liability risk. Their buying process can also be frustrating, as there are many bugs in the system, in my experience, including the quote flow freezing, options appearing available when they aren't, and issues with binding without an agent's help.

Learn More: biBERK Business Insurance Review

What Types of Insurance Do Retailers Need?

Most retail businesses start with a business owner's policy that bundles general liability, commercial property and business interruption coverage. This is primarily because it protects you from the most common risks related to personal property damage or theft, third-party injuries to customers, and operational interruptions caused by damage to the building you're working in. 

From there, cyber insurance is a common addition, especially for online-focused sellers, and workers' comp for when you hire employees. Other specialty policies like commercial auto, liquor liability, and inland marine depend on whether you're offering alcohol as a product or if you provide in-house delivery services.

Customer injuries in your store (slip-and-fall), property damage to others and claims from products you sell
Every retail business needs this. It's the baseline policy for storefront and online sellers alike.

Falls on level ground are the #2 cause of serious workplace injuries nationwide ($10.5B/yr), and retail sees more of them than almost any other sector.

Bundles general liability, commercial property and business income coverage into one policy, often at a lower cost than buying each separately
Most small to mid-size retailers with a physical location. Covers your space, inventory and lost income if you have to shut down after a covered loss.

40% of small businesses never reopen after a disaster, and most never had income-replacement coverage to bridge the gap.

Your building (if owned), inventory, equipment, signage, fixtures and tenant improvements
Any retailer with a physical storefront, warehouse or storage space. Especially important for inventory-heavy operations like furniture, electronics or sporting goods stores.

Between shoplifting, employee theft, and damaged goods, inventory just walks off the shelves. Retailers lost about $112B to shrink in 2024, the worst rate in a decade.

Medical costs, lost wages and rehabilitation for employees injured on the job
Required in most states once you have employees. Retail workers face risks from heavy lifting, ladder use, box cutters and repetitive stocking tasks.

Stockers lifting boxes, cashiers standing all shift, ladders in the stockroom: retail's physical, repetitive work injures employees at about 60% above the national average.

Vehicles used for deliveries, pickups, or transporting inventory between locations
Any retailer that uses a car, van or truck for business purposes. Personal auto policies typically won't cover accidents during business use.

Imagine your delivery van rear-ends someone on the way to a customer's house. Juries are now handing down record awards for exactly these cases, with $10M+ verdicts up 52% in a single year.

Liquor Liability

Claims arising from the sale of alcohol, including injuries or property damage caused by an intoxicated customer
Liquor stores, convenience stores selling alcohol and specialty food retailers with a liquor license. Not included in standard GL policies.

General liability won't touch any liabilities from selling alcohol, and dram shop settlements typically run $50K to $500K on their own without coverage.

Data breaches, stolen customer payment information, ransomware attacks and regulatory fines
Retailers that process credit cards, store customer data or operate e-commerce sites. POS system breaches are a common retail exposure.

44% of breaches last year involved ransomware, and most retailers hit ended up paying to get their systems back.

Additional liability coverage above the limits of your GL, commercial auto or employer's liability policies
Retailers with higher foot traffic, multiple locations or large product liability exposure who want a buffer above their primary limits.

The median "nuclear verdict" is now $51M, more than double what it was five years ago, and you'd need umbrella coverage to help avoid this situation at a reasonable cost.

Inland Marine
Inventory, equipment or goods in transit between locations or to customer sites
Retailers that move stock between stores, warehouses or events. Standard property policies often exclude goods in transit.

Cargo theft losses jumped 60% last year to $725M, and your property policy won't cover goods once they're in transit.

Employment Practices Liability (EPLI)
Claims from employees alleging wrongful termination, discrimination, harassment or retaliation
Retailers with employees, especially those with seasonal staff and high turnover. Some BOPs include it; others require a separate purchase.

Retaliation is the single most common charge the EEOC receives, and it's specifically excluded from your GL policy.

mglogo icon

WHY GETTING RETAIL BUSINESS INSURANCE IS IMPORTANT

Retailers sell or rent out products at relatively high volumes, even if they are small organizations. Having inventory means you're susceptible to theft or losses from fires at the buildings where it's kept. Beyond this, the physical aspects of sending a product in transit or selling it in a store and handing it to customers expose you to risks of bodily injury, damage to sold inventory during transport, and claims that your products (if you make them) hurt those you've sold to. Retail stores are also among the most susceptible to cyber-attacks linked to POS systems and online sales.

These are day-to-day risks that will stack up over time, and scaling your company up only makes the risk worse. Even if you only make $15,000 in claims over the course of a year, it is well worth the few hundred dollars a month you'll likely pay for a BOP policy, inland marine, and cyber coverage to cover these risks.

How Much Does Retail Store Business Insurance Cost?

The average cost of insurance for retailers varies depending on the type of coverage you select. Based on my analysis across 39 retail subindustries in all 50 states and Washington, D.C., here's what retail businesses typically pay.

What Are These Costs Based On?

Your actual cost depends on your specific retail focus, location, employee count, payroll and coverage limits. For a more personalized estimate, use our business insurance calculator below. You can also click get quotes to be matched with an insurer based on the details you enter.

Retail Business Insurance Cost Calculator
Select Coverage Type
Select State
Select Employee Count
Select Vehicle Type
Monthly Cost Estimate—

How To Get The Best Retail Insurance

Shopping for retail business insurance is easier when you know what to look for before you start comparing quotes. This checklist walks through the key steps for finding the right fit for your store.

  1. 1

    Identify Your Retail Risk Profile

    Think about the specific risks your operation faces day to day. A clothing boutique has different exposures than a hardware store or a liquor shop. Slip-and-fall injuries, product liability claims, inventory theft and employee injuries are the most common retail risks, but their severity varies by subindustry. Your risk profile determines which coverage types you actually need and how much coverage to carry.

  2. 2

    Determine Which Coverage Types You Need

    Most retailers start with a BOP that bundles general liability, commercial property and business income coverage, which covers most risks and requirements you'll be subject to. From there, layer on what your operation requires:

    • Workers' compensation if you have employees (required in most states)
    • Commercial auto if you use vehicles for deliveries or pickups
    • Liquor liability if you sell alcohol
    • Cyber insurance if you process credit cards or store customer data online
    • Inland marine if you move inventory between locations
    • EPLI if you have seasonal staff or high turnover

    Read More: How Much Business Insurance Do You Need?

  3. 3

    Set Your Coverage Limits and Budget

    Your limits should reflect the value of your inventory, the size of your space and your exposure to liability claims. A retailer carrying $400,000 in electronics inventory needs different property limits than a pop-up vendor with a folding table and a few boxes of product. Compare quotes and coverage from multiple providers with the same to get the best view of value.

  4. 4

    Compare Provider Fit

    Not every insurer works equally well for every type of retailer. ERGO NEXT is the strongest option for solo operators, online sellers and micro-retailers who want low rates and a fast digital buying experience. The Hartford fits brick-and-mortar specialty stores that need deeper coverage, peak season inventory protection and built-in EPLI. biBERK works for independent retailers who want to buy direct without a broker. Thimble is built for pop-up vendors and seasonal sellers who need flexible, short-term coverage. Progressive Commercial is the pick for retailers that run delivery vehicles or need liquor liability.

  5. 5

    Review Claims Handling and Ongoing Support

    A cheap policy doesn't help much if the claims process is slow or combative. Look at how each provider handles filing, communication and dispute resolution. Check whether you can manage your policy, add additional insureds and pull COIs quickly, especially if your landlord or a marketplace platform requires proof of coverage on short notice. Seasonal retailers should also confirm how easy it is to adjust coverage mid-year when inventory levels shift.

Retail Business Insurance: FAQ

In addition to what was discussed in this article, I've also covered other common questions and answered them below.

Best Retail Business Insurance: Bottom Line

For most retail businesses, ERGO NEXT, The Hartford and biBerk deliver the strongest combination of pricing, service and coverage across retail's core risks. ERGO NEXT leads on overall score and in most states, but The Hartford's coverage depth makes it the better fit for larger storefronts and established brick-and-mortar formats. 

The most useful frame for evaluating any retail insurer is whether the policy was built for businesses that sell physical goods, carry inventory and manage customer foot traffic liability. Providers that understand that profile price it, cover it and service it differently than those treating retail as a generic small business category.

Best Retail Business Insurance Chart

Get More Specific Retailer Insurance Guidance

MoneyGeek offers insurance guides for the following retail areas, with more specific advice on top providers, costs and the types of coverage you need.

Get Retail Business Insurance Quotes

Use our tool below to get matched to your top business insurance provider for your retail organization. From there, you can get quotes on your match's website.

About Mark Flores


Mark Flores, Business Insurance Writer, MoneyGeek

Mark Flores is a Business Insurance Content Writer at MoneyGeek, where he focuses on commercial auto, commercial property, cyber and specialty business insurance coverage. His work simplifies coverage terms, gives business owners a strong baseline for expected costs, and narrows down policies and providers tailored to your operation, regardless of complexity.

Before joining MoneyGeek’s business insurance team, Mark worked as a Senior Content Writer at Clutch.co, where he produced structured B2B reviews and provider analyses based on client interviews, company research and service evaluation. That experience shaped his approach to business insurance content, especially when comparing insurers, explaining coverage differences and translating complex policy features into practical guidance for small business owners.

Mark also spent nearly 4 years as a digital marketing specialist serving small-business clients across industries such as home services, manufacturing and education. That background gives him practical context for how businesses evaluate vendors, manage operational needs and make purchasing decisions.

At MoneyGeek, he applies this research and evaluation experience to build guides that help transportation sectors, those with complex property-related risks (such as hotels and retail stores), and those most at risk of a cyberattack get the coverage they need at a reasonable price.

Linkedin: https://www.linkedin.com/in/mark-jason-flores-7844634a/

Contact Email: mark.flores@moneygeek.com