


Jump to the section that fits your needs best:
Average General Liability Insurance Cost (2026 Report)
Average general liability insurance costs range from $27 to $2,298 monthly and your rate will vary based on your industry, location and business size.
If you're ready to buy, get matched to the best general liability insurance provider for your business below.
Select state
Updated: September 14, 2026
Advertising & Editorial Disclosure
Featured Partner
The Hartford
- The Hartford is MoneyGeek's cheapest general liability insurer for 2026, at $102 a month, 17% below the $123 national average.
- AM Best rates The Hartford A+ (Superior) for financial strength.
- Small business customers at The Hartford pay about $69 a month for a $1 million general liability policy.
- The Hartford's small business coverage is available in 48 states, not including Alaska or Hawaii.
On The Hartford's site
*MoneyGeek featured partner. Editorial rankings below are independent of this placement. Rates, rankings and savings comparisons are based on MoneyGeek's independent research and Hartford-reported data as of 2026. Figures are estimates and averages, not a guarantee of any individual quote, premium or discount.
How Much Does General Liability Insurance Cost?
Small businesses with one to four employees pay $123 per month ($1,474 annually) on average for general liability insurance with $1 million per occurrence/$2 million aggregate limits. This average reflects analysis across 408 industries and all 50 states, plus Washington, D.C.
This national benchmark doesn't guarantee your price. Small business insurance costs vary based on industry risk level, location and business size, even for identical coverage limits.
To estimate average general liability insurance costs, we analyzed quote data from major U.S. small business insurance providers and modeled standardized premium estimates across common business profiles. These modeled results are designed to provide a consistent national benchmark and show how premiums vary by key baseline factors including business size, industry and location.
Dataset Scope and Assumptions
Our cost modeling uses standardized inputs for consistent comparisons across businesses.
- Providers analyzed: 10 major insurance providers
- Industries covered: 408 industries
- Geography: all U.S. states (including Washington, D.C.)
- Employee count bands: zero, one to four, five to nine, 10 to 19 and 20 to 49 employees (representing ~95% of small businesses)
- Policy baseline: standard general liability policy with $1 million per occurrence / $2 million aggregate limits
- Total estimates modeled: just over 1 million standardized pricing estimates
We also incorporated modeled average revenue and payroll personalized across all combinations of states, industry and employee counts to improve the accuracy of pricing. To model these assumptions against our cost factors, we used data from these sources:
- CBP (for employee size class density by state + NAICS)
- QCEW (for wage/payroll intensity by industry + geography)
- Economic Census / SUSB (for receipts/output intensity by industry)
- Calibrated against:
- Private comp databases
- IRS SOI totals
How We Calculated Average General Liability Costs
Our published averages represent modeled premiums for standardized business profiles and were aggregated in two ways:
- National benchmark average: The national average cost reflects the modeled premium for a standardized one to four-employee small business across all industries and states included in our dataset for a standard general liability policy.
- Segment averages: To show how costs vary, we calculated average modeled premiums for our national base profile and isolated for variables, including:
- Employee count (business size ranges)
- General industry categories
- States (including Washington, D.C.)
Segment averages were produced by aggregating modeled pricing trends across the full dataset so readers can compare how premiums shift across business types and regions.
Get General Liability Insurance Cost Estimates
If you want a more personalized cost estimate, you can use our general liability insurance cost calculator below.
General Liability Insurance Cost Estimate Calculator
Select your state and industry to view average business insurance premiums in your area. Rates are calculated based on a business with 5 employees and $500,000 in annual revenue.
Select General Industry
Select State
Select Employee Count
Average monthly rate—
Select General Industry
Average monthly rate—
Select State
Select Employee Count
What Factors Affect General Liability Insurance Costs?
General liability pricing varies based on three core factors: business size, geographic location and industry classification. These variables explain most premium differences across small businesses because they capture key exposures insurers price: claim frequency, severity potential, operational setup and business activity level.
Premiums in our cost modeling use these three baseline drivers. The sections below explain how each influences general liability cost and how pricing shifts across businesses.
 Business size
 is the strongest baseline pricing driver for general liability insurance because it directly correlates with total exposure. Larger businesses have more opportunities for third-party injury and property damage through higher work volume, more customer interactions and more employees.
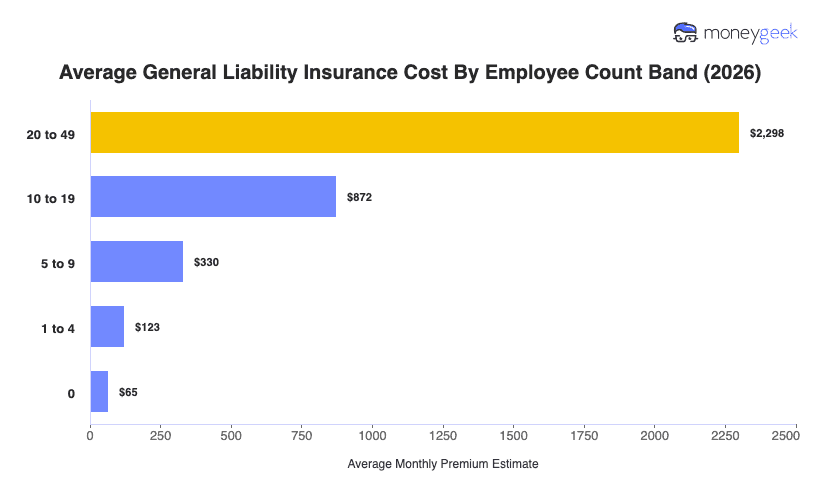
For employee count ranges representing 95% of small businesses, general liability premiums increase as business size grows. Pricing ranges from 47% lower than average for sole proprietors to 1,768% higher than average for businesses with 20 to 49 employees.
 Industry classification
 is the second strongest baseline pricing driver because claim frequency and severity vary widely across business types. Industry class codes account for exposure factors including jobsite work, customer foot traffic, equipment use, work on customer property, subcontractor oversight and product liability.
Across 408 industries, general liability premiums vary by industry from 78% below average to 174% above average. Tech/IT represents the lowest-risk category, while Contracting and Construction represents the highest risk.
 Geographic location
 is the third major baseline pricing driver because it affects claim costs, even for identical businesses with the same coverage limits. Insurers price general liability differently by state to reflect local differences in medical costs, repair and replacement costs, legal environment and claim settlement patterns.
General liability premiums vary by state from 29% lower than average in West Virginia to 54% higher than average in California.
How to Lower General Liability Insurance Costs Without Sacrificing Coverage
General liability premiums vary most by business size, industry type and state, but these baseline factors don't determine your final quote alone. Businesses can reduce premiums by adjusting the pricing levers insurers use at quoting and renewal without leaving coverage gaps.
Below we've summarized the most effective ways to get cheap general liability insurance:
Quick General Liability Cost Lowering Methods
We've ranked these immediate actions by financial risk.
 Provide clean, accurate underwriting information
Small differences in how your business is described can change your rating class and premium. Use the correct industry type, accurate revenue and employee counts, and a clear operations description. Insurers price your business using worst-case assumptions when information is unclear.
 Compare multiple insurers
Compare multiple business insurance quotes with identical coverage terms to find the best and most affordable provider.
 Bundle general liability into business owner's policies (BOP)
Bundling GL with other coverage (often commercial property in a BOP) reduces pricing versus buying separate policies and simplifies billing and renewals.
 Pay annually instead of monthly
Annual payments eliminate installment fees and often include small discounts since insurers receive their full premium upfront. This saves 5% to 10% compared to monthly payment plans, though you'll need to cover the full annual cost at policy inception.
 Increase your deductible (if you can afford it)
Higher deductibles lower premiums because you pay more of each claim yourself. Only increase your deductible if you can comfortably cover that amount out of pocket.
 Adjust your coverage limits
Premiums scale with limits. If your contracts allow it, lowering limits can reduce costs, but make sure your limits match your customer requirements and exposure.
Long-Term General Liability Cost Lowering Methods
Beyond immediate actions, these long-term strategies lower general liability premiums as your business grows.
General Liability Insurance Cost: Bottom Line
General liability insurance costs vary widely because insurers estimate your business's claim frequency and severity differently. Your premium is based primarily on business size, industry classification and location. Use the $123 monthly national average as a benchmark, not a prediction.
Apply this report by considering context, not a single price:
- Where do you fall compared to the average? (industry + state + employee count)
- What is driving your cost? (baseline risk vs. coverage design choices)
- What would meaningfully change your price? (limits, deductible, bundling and accurate underwriting details)
Frame your premium this way to evaluate quotes and coverage options based on whether they reflect your true risk profile, not just whether they're above or below the national average.
If you want to learn about other business insurance costs
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com