Cheapest General Liability Insurance Companies

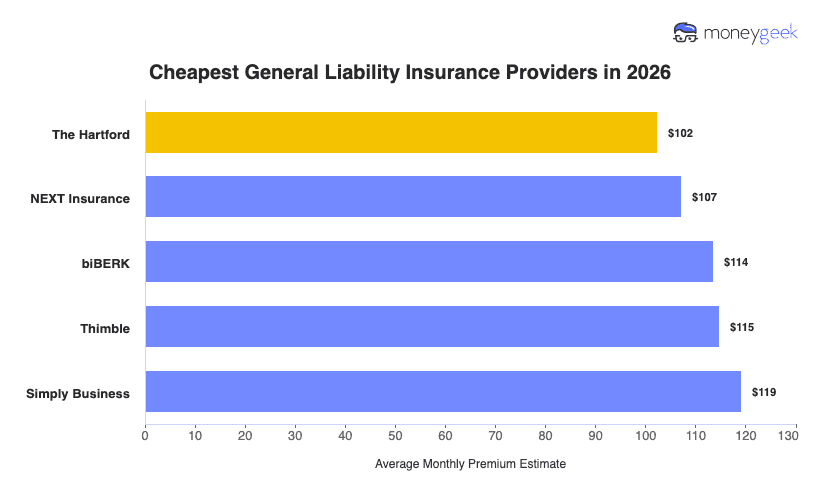
We found these providers to have the cheapest general liability insurance (AKA public liability insurance) on average:

  1. The Hartford : The cheapest general liability insurer overall with average rates of $102/mo which saves small businesses 17% on average. The company is generally cheapest for most professional service and office-based businesses (finance, tech, marketing)
  2. ERGO NEXT: NEXT saves businesses 13% on general liability insurance overall with average rates of $107/mo or $1,286/yr. The business insurer is cheapest for hands-on, operational service businesses (Contractors, Food & Beverage, Transportation)
  3. biBERK: biBERK rounds out our top three cheap general liability insurers with average savings of 8%. They are often cheapest for sole proprietor service businesses (cleaning, fitness, recreation).

Your most affordable business insurance provider and monthly rate can vary widely based on your specific business details. So, use these companies as a starting point for possible general liability policy costs, not a final answer.
Featured Partner
The Hartford
The Hartford
  • The Hartford ranks first for cheapest general liability insurance in MoneyGeek's 2026 study, at $102 a month.
  • Tech and IT, marketing, financial services, education and retail businesses get The Hartford's lowest rates.
  • A 17-time World's Most Ethical Companies honoree, The Hartford was one of only two property and casualty insurers on Ethisphere's 2026 list.
  • In 13 states, most of them in the Northeast and Midwest, The Hartford is the cheapest general liability insurer MoneyGeek analyzed.
On The Hartford's site

*MoneyGeek featured partner. Editorial rankings below are independent of this placement. Rates, rankings and savings comparisons are based on MoneyGeek's independent research and Hartford-reported data as of 2026. Figures are estimates and averages, not a guarantee of any individual quote, premium or discount.

The Hartford$102$1,22717%
ERGO NEXT$107$1,28613%
biBERK$114$1,3638%
Thimble$115$1,3767%
Simply Business$119$1,4303%

How We Determined The Cheapest General Liability Insurance Providers

The Hartford

The Hartford: Cheapest General Liability Insurance For Most Businesses

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford was the cheapest general liability insurance provider for the widest range of business profiles in our analysis, especially lower-risk professional and service businesses, and companies with more employees. The company on average has general liability insurance rates that are 17% below average at $102/mo, saving most around $21/mo. 

According to our dataset, the company offers especially attractive savings for those in the financial, medical and education sectors of over 20% compared to the average for their industry.

Most often cheapest for these business profiles:

  • General industries most often cheapest for: Tech/It, Marketing & Communications, (Arts, Media & Entertainment), Financial Services, Education, Retail & Product Rental, Healthcare & Medical
  • Employee counts most often cheapest for: 5 to 49+ employees
  • States/Regions most often cheapest in:
    • Northeast: CT, MA, NH, NJ, NY, PA, RI, VT
    • Midwest: IL, IN, MI, MN, OH, WI
    • South: MD, DC, VA

Not a Fit? Jump To: biBERK or ERGO NEXT

ERGO NEXT

ERGO NEXT: Cheapest General Liability Insurance for Hands-On Service Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT tended to be one of the lowest-cost general liability options, costing around $107/mo on average which saves small businesses around 13% compared to national benchmarks. Their lowest pricing favors hands-on service businesses, especially when employee count is small (1–4 employees). If your work happens on job sites. involves repair, or personalized service work, ERGO NEXT is frequently among the cheapest providers to compare.

Our analysis found if you are in hospitality, manufacturing, food or repair/maintenance fields general liability savings with the provider reached over 25% compared to the average within these business areas.

Most often cheapest for these business profiles

  • General industries most often cheapest for: Construction & Contracting, Consulting Services, (Beauty, Body & Wellness Services), Manufacturing, Repair & Maintenance, Pet Care Services, Misc Professional Services (Event Planners and Funeral Homes for example), (Hospitality, Travel & Tourism), Transportation & Logistics, Food & Beverage, Wholesale & Distribution, Childcare Services
  • Employee counts most often cheapest for: 1-4 employee businesses
  • States/Regions most often cheapest in:
    • West: AZ, AK, CA, CO, HI, ID, MT, NM, NV, OR, UT, WA, WY
    • South: AL, AR, DC, DE, FL, GA, KY, LA, MD, MS, NC, OK, SC, TN, TX, VA, WV
    • Midwest: IA, IL, IN, KS, MI, MN, MO, ND, NE, OH, SD, WI
    • Northeast: CT, MA, ME, NH, NJ, NY, PA, RI, VT

Not a Fit? Jump To: biBERK or The Hartford

biBerk

biBERK: Cheapest General Liability Insurance For Fitness and Recreation Businesses

COMPANY HIGHLIGHTS

biBERK rounds out the third-place spot for cheap general liability insurance, winning for affordability in the general industries surrounding recreation, exercise, real estate/property services and cleaning. Its specialty is sole proprietor businesses (2nd in affordability), and its pricing is lowest for niche market states (2nd in affordability for Alaska and Hawaii). While it is not the cheapest on our list, you can save an average of 8% or $9/mo with biBERK.

Most often cheapest for these business profiles

  • General industries most often cheapest for: Real Estate & Property Services, Recreation and Sports, Cleaning Services and Fitness Services
  • Employee counts most often cheapest for: Sole Proprietors
  • States most often cheapest in: AK, HI

Not a Fit? Jump To: ERGO NEXT or The Hartford

Cheapest General Liability Insurance By Industry

At the general industry level, ERGO NEXT is proportionally the cheapest general liability insurance company, winning 12 out of 25 general industries with savings of up to 34% on average. The Hartford isn't far behind with 7 wins at second place for affordability, biBERK sits at 3rd with four wins and Nationwide 4th with 2 wins. Tech related organizations will be able to get the most affordable general liability policies on the market at $24/mo with marketing, arts and consulting businesses following all being $30/mo or under on average.

Data filtered by:
Select
Agriculture & Natural ResourcesNationwide$8812%
Arts, Media & EntertainmentThe Hartford$3020%
Beauty, Body & Wellness ServicesNEXT Insurance$3221%
Childcare ServicesNEXT Insurance$10815%
Cleaning ServicesbiBERK$8119%
Construction & ContractingNEXT Insurance$26222%
Consulting ServicesNEXT Insurance$323%
EducationThe Hartford$3330%
Financial ServicesThe Hartford$3321%
Fitness ServicesbiBERK$8221%
Food & BeverageNEXT Insurance$9525%
Healthcare & MedicalThe Hartford$14830%
Hospitality, Travel & TourismNEXT Insurance$7034%
ManufacturingNEXT Insurance$4830%
Marketing & CommunicationsThe Hartford$2620%
Nonprofit & AssociationsNationwide$4913%
Other Professional ServicesNEXT Insurance$6318%
Pet Care ServicesNEXT Insurance$6317%
Real Estate & Property ServicesbiBERK$3920%
Recreation and SportsbiBERK$7617%
Repair & MaintenanceNEXT Insurance$5429%
Retail & Product RentalThe Hartford$8919%
Tech/ITThe Hartford$2414%
Transportation & LogisticsNEXT Insurance$7411%
Wholesale & DistributionNEXT Insurance$998%

If you want to dig deeper into the cheapest commercial insurance for your industry, we've left dedicated resources below.

Cheapest General Liability Insurance By State

ERGO NEXT's proportional lead is much larger at the location level for cheap general liability insurance, winning 38 out of 51 states and territories studied in terms of affordability. The Hartford primarily has dominance in the northeast and midwest winning the remaining states, sporting the highest average savings of 18% in Connecticut, Vermont, Rhode Island and Minnesota. West Virginia, Mississippi and South Dakota are the most general liability insurance cost friendly states and have the lowest prices available for the coverage type starting at $75/mo on average.

Data filtered by:
Select
AlabamaNEXT Insurance$8812%
AlaskaNEXT Insurance$13511%
ArizonaNEXT Insurance$10415%
ArkansasNEXT Insurance$8613%
CaliforniaNEXT Insurance$16116%
ColoradoNEXT Insurance$12415%
ConnecticutThe Hartford$13018%
DelawareNEXT Insurance$11412%
District of ColumbiaNEXT Insurance$15913%
FloridaNEXT Insurance$12315%
GeorgiaNEXT Insurance$10513%
HawaiiNEXT Insurance$14112%
IdahoNEXT Insurance$8414%
IllinoisThe Hartford$11816%
IndianaThe Hartford$8817%
IndianaNEXT Insurance$9313%
IowaNEXT Insurance$8312%
KansasNEXT Insurance$8913%
KentuckyNEXT Insurance$8913%
LouisianaNEXT Insurance$969%
MaineNEXT Insurance$9812%
MarylandThe Hartford$12917%
MarylandNEXT Insurance$13513%
MassachusettsThe Hartford$13917%
MichiganThe Hartford$9617%
MinnesotaThe Hartford$10518%
MississippiNEXT Insurance$7813%
MissouriNEXT Insurance$9212%
MontanaNEXT Insurance$8115%
NebraskaNEXT Insurance$9113%
NevadaNEXT Insurance$11115%
New HampshireNEXT Insurance$11713%
New JerseyThe Hartford$13217%
New MexicoNEXT Insurance$8814%
New YorkThe Hartford$14917%
North CarolinaNEXT Insurance$9614%
North DakotaNEXT Insurance$8512%
OhioThe Hartford$9216%
OklahomaNEXT Insurance$8812%
OregonNEXT Insurance$11715%
PennsylvaniaThe Hartford$10816%
Rhode IslandThe Hartford$10718%
South CarolinaNEXT Insurance$8412%
South DakotaNEXT Insurance$8012%
TennesseeNEXT Insurance$9714%
TexasNEXT Insurance$10613%
UtahNEXT Insurance$9414%
VermontThe Hartford$10118%
VirginiaNEXT Insurance$11615%
WashingtonNEXT Insurance$12916%
West VirginiaNEXT Insurance$7513%
WisconsinNEXT Insurance$9413%
WyomingNEXT Insurance$9213%

Is The Cheapest General Liability Insurance Right For Your Business?

The cheapest general liability insurance policy can be a smart choice as long as it still protects your business properly. The lowest-cost option is safest when the following criteria are met:

  • Coverage limits match your actual risk exposure (and any contract requirements)
  • Coverage is affordable, so you can pay them if you ever file a claim
  • Coverage add-ons and endorsements (if needed) are available at a reasonable cost
  • The provider has a strong customer experience reputation, including the buying process, policy management, and claims handling

Ultimately, the goal isn’t to choose the cheapest policy at all costs, it’s to choose the best general liability option that meets your coverage needs at an affordable rate. However, if your budget only allows for the lowest-cost policy, you may need to accept tradeoffs (like lower limits or fewer add-ons) and plan to upgrade coverage as your business grows.

How To Get Cheaper General Liability Insurance Without Sacrificing Protection

Position your business for the lowest possible general liability rates without compromising protection with the following methods:

  • bag icon

    Compare general liability quotes using the same limits (apples-to-apples)

    To confirm who’s actually cheapest for your business, compare quotes using the same limits and coverage terms. Our rankings are based on standardized estimates, so quoting directly is the best way to verify your lowest-cost provider.

  • hammer icon

    Ensure your business classification (class code) is correct

    The most common reason businesses overpay for general liability and other business insurance types is due to class code misclassification. If your business is misclassified on your policy, it can increase your premium significantly, sometimes by 20%+ depending on the class code.

  • insurance2 icon

    Only pay for general liability coverage limits you actually need

    Identifying not only the general liability coverage you are required to get, but the actual limits that will protect your business from the most likely risks will stop you from overpaying. For example, if you have a low risk business, a $500,000 per occurence and $1 million aggregate policy can save you around 13% compared to a standard $1 million per occurence and $2 million aggregate policy. Just make sure that if you're choosing lower coverage limits that you're still meeting any requirements you may have (check any client, landlord, or vendor requirements).

    Read More: How Much General Liability Insurance Do I Need?

  • coins2 icon

    Bundle general liability insurance when it lowers your total cost

    Generally speaking you can save between 10% to 15% when bundling general liability insurance with other policies, especially when it is a Business Owners Policy (BOP). However, you should ensure that the total cost with discounts is actually the lowest cost value for the coverage you need and with a provider you can trust.

  • falling icon

    Reduce general liability claim risk in ways insurers actually price

    Not every method of communicating general liability claim risk reduction changes your premium, but these actions commonly do:

    • strong safety procedures (especially for jobsite work)
    • keeping certificates of insurance (COIs) on file for subcontractors
    • avoiding small claims when possible (frequent claims history raises rates)
    • using written agreements (especially with subcontractors and customers)

Affordable General Liability Insurance: Bottom Line

There’s no single cheapest general liability insurance company for every business. The cheapest option depends on your industry, state and business size and the lowest-priced policy only works if it still meets your contract requirements and protects you from real risk exposure. Use our recommendations to narrow your options, compare quotes apples-to-apples to confirm who’s truly cheapest for your business and ensure you’re choosing the lowest-cost option that still meets your coverage needs.

Cheapest General Liability Insurance Chart

How We Determined The Cheapest General Liability Insurance Providers

To identify the cheapest general liability insurers, we analyzed real pricing data from 10 major providers and modeled a large set of standardized pricing estimates across common U.S. small business profiles.

Dataset scope and assumptions

  • Providers analyzed: 10 major insurance providers
  • Industries covered: 408 industries
  • Geography: all U.S. states and territories (including Washington, D.C.)
  • Employee count bands: 0, 1–4, 5–9, 10–19 and 20–49 employees (95% of market)
  • Policy baseline: standard $1 million per occurrence / $2 million aggregate general liability policy
  • Pricing estimates modeled: just over 1 million total estimates

We also incorporated modeled average revenues and payrolls across business profiles to improve pricing accuracy.

How we determined which provider was “cheapest”

We used this dataset to determine which insurers were most often the lowest-cost option across different business profiles. Our “cheapest” rankings include both:

  • General Recommendation: Provider rankings based on average estimated pricing for a standardized 1–4 employee business profile across all industries and states in our dataset.
  • Factor Combination Recommendations: Provider rankings based on which insurer was most often cheapest within specific business factor combinations. For example:
    • Industry × State pricing was compared using a standardized 1–4 employee profile
    • Employee count affordability was derived by comparing aggregated pricing trends across industries and states

Important note: These results represent standardized pricing estimates, not personalized quotes. Actual pricing can vary based on your business classification, revenue/payroll, claims history and the specific limits, deductibles and endorsements you choose. For the most accurate cheapest-provider answer, we recommend comparing quotes apples-to-apples using the same coverage limits.

Read our full methodology.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com