Cheapest Florida General Liability Insurance Companies

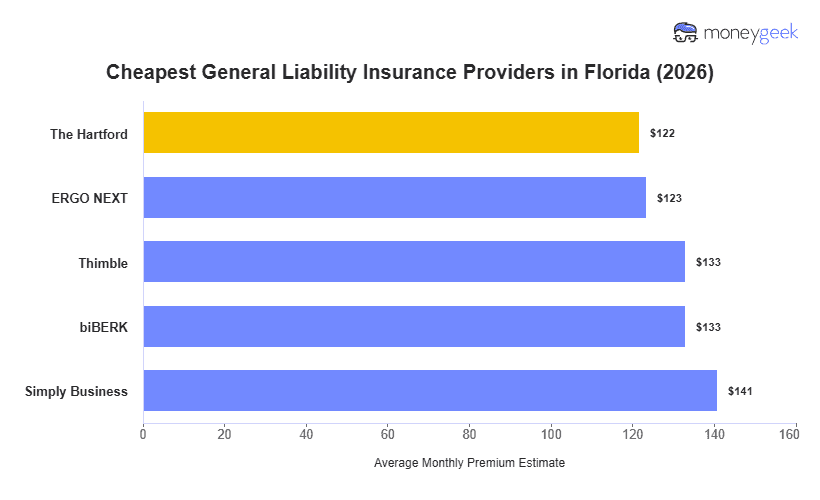
I analyzed general liability quotes across 25 general industries and found that the same three providers consistently have the cheapest general liability insurance in Florida. Note, however, that the most affordable option for you depends on your specific business type and operations.

  • The Hartford: Most affordable for professional services and creative businesses (IT consultants, financial advisors, photographers, web developers)
  • ERGO NEXT: Lowest rates for hands-on trades and personal care services (carpentry, plumbing, hair salons, massage therapy)
  • biBerk: Cheapest for fitness centers and cleaning companies (bowling alleys, gyms, janitorial services, carpet cleaning)

Your team size and past claims can also change your general liability insurance premium. If you're an event vendor and usually serve large tourist crowds, are more common for your business than for a home-based consultant. Use our list as a starting point to narrow your options. Then, compare quotes with the same limits and policy terms to find the lowest price for your business.

The Hartford$122$1,45816%
ERGO NEXT$123$1,48115%
Thimble$133$1,5948%
biBerk$133$1,5958%
Simply Business$141$1,6902%
Coverdash$151$1,807-4%
Progressive Commercial$153$1,839-6%
Nationwide$162$1,944-12%
Hiscox$162$1,949-13%
Chubb$164$1,965-13%

We identified the cheapest general liability insurers in New Jersey using pricing data from 10 major providers and more than 20,000 estimates covering 408 business types across 25 industries. Our data includes businesses with zero to 49 employees. Each estimate assumes $1 million in coverage per claim and $2 million total coverage for the policy period, with revenue and payroll factored into the price.

For the overall rankings, we compare average rates for businesses with one to four employees across industries. Industry recommendations use the same one-to-four-employee range so the comparisons stay consistent. We also compare how rates change as businesses grow.

These prices are estimates, not personalized quotes. Your actual premium can change based on your business type, revenue or payroll, claims history, coverage limits, deductible and endorsements.

Read our full methodology

The Hartford

The Hartford: Cheapest for Professional Services and Creative Businesses

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks the cheapest for 25% of all business types analyzed. Small businesses in Florida pay around $122 monthly, 12% below the state average and save roughly $23 monthly. Monthly rates for driving schools and driving instructors are 43% to 45% lower than the average premiums.

Most often cheapest for these business profiles:

  • General industries: Agriculture and Natural Resources, Arts, Media & Entertainment, Education, Financial Services, Health Care and Medical, Tech/IT
  • Employee count: One to 49 employees

Not a fit? Jump to: ERGO NEXT or biBerk

ERGO NEXT

ERGO NEXT: Cheapest for Hands-On Trades and Service Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

Small Florida businesses working in construction, food service and personal care find their lowest rates through ERGO NEXT. If we're looking at specific business types, it's the most affordable option for 42% (173 out of 408). Food trucks, catering operations and mobile food vendors save the most, paying 46% to 48% below average premiums, while most small businesses' monthly costs run around $123, $21 less than the state average.

Most often cheapest for these business profiles:

  • General industries: Beauty, Body and Wellness Services, Childcare Services, Construction and Contracting, Consulting Services, Food and Beverage, Hospitality, Travel and Tourism, Manufacturing, Marketing and Communications, Other Professional Services, Pet Care Services, Real Estate and Property Services, Repair and Maintenance, Retail and Product Rental, Transportation and Logistics

Not a fit? Jump to: The Hartford or biBerk

biBerk

biBerk: Cheapest for Fitness Centers and Cleaning Companies

COMPANY HIGHLIGHTS

At $133 monthly ($1,595 annually), biBerk saves most Florida small businesses roughly $11 per month compared to the state average. Solo proprietors get even better rates at $65 monthly, running 11% below what most sole proprietors pay. Health care providers and tree service contractors see the strongest discounts: doulas save 34%, student nurses save 31% and tree removal businesses cut costs by 34% compared to typical Florida premiums.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Recreation and Sports
  • Employee count: Sole proprietors

Not a fit? Jump to: The Hartford or ERGO NEXT

Is the Cheapest General Liability Insurance Right for Your Florida Business?

A small service company working with a limited client base probably prioritizes price, while businesses serving tourist crowds or working under venue contracts need higher limits or added policy features. Florida’s tourism-heavy economy makes those differences more important, and these situations show when a low-cost policy may not be enough.

  • Venue and vendor requirements: You may need an additional insured endorsement or proof of coverage before you can start the job, and not every low-cost option gets those documents in the time you need them.
  • Large-event exposure: Serving big crowds changes the stakes. If one incident could injure several guests, higher liability limits matter more than an affordable policy.
  • Specialized operations: A cheap quote won’t help if the insurer doesn’t cover what you do. If you run a U-pick farm or another visitor-facing operation with activities outside standard business classifications, confirm that your core services are included before buying.
  • Changing contract needs: Project-based work requires policy updates as jobs change. If clients regularly ask for revised certificates or new additional insureds, look at how easily the insurer can handle those requests, not just the initial rate.

If your business is relatively simple and doesn’t have many contract or coverage requirements, you can focus more on price. If your Florida business works with large venues with heavy customer traffic or has specialized operations, weigh coverage fit alongside cost and consider the best general liability insurers that can meet those needs.

How to Get Cheaper General Liability Insurance in Florida

Florida’s weather and seasonal business patterns affect what insurers charge. You can lower general liability costs without leaving your business underinsured. Focus on the parts of your policy and operations that actually influence your pricing.

  • swipe icon

    Compare general liability quotes using the same limits

    A lower quote isn’t always a better deal if it gives you less coverage. When you compare business insurance quotes, make sure insurers price the same coverage limits and deductibles. That way, you can compare them fairly.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Insurers use a class code to describe what your business does and help set your rate. If that description’s wrong, you could end up paying for risks that don’t apply to you. For example, a Florida property maintenance company shouldn’t be priced as a landscaping contractor if it doesn’t perform landscaping work. Check the business description on your quote and review it again at renewal if your services have changed.

  • insurance2 icon

    Only pay for general liability coverage limits you actually need

    You don’t need to choose the highest limit available. Base your coverage on the general liability requirements in your client contracts or lease, along with the risks your business handles day to day. The right limits should satisfy those obligations while giving you enough protection for the work you actually do.

  • money2 icon

    Use general liability deductibles and payments strategically

    A higher deductible lowers your premium, but you’ll pay more yourself if you file a claim. Before increasing it, compare how much you’ll save with the extra amount you’d need to cover out of pocket.

    Payment structure matters too. Paying annually can help you avoid installment fees, but monthly payments are easier on cash flow. If your income’s seasonal, compare each payment option’s total cost and choose the one that fits your business.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    A business owner's policy (BOP) combines general liability with commercial property coverage. Bundling can save money when you actually need both types of insurance. Compare the cost of a BOP with standalone general liability before assuming the bundle is cheaper.  If you run a home-based business, however, you usually have little property to insure. A BOP might mean you’re buying coverage you don’t need.

  • takingNotes icon

    Lower your claim risk in ways Florida insurers reward

    Insurers consider how likely your business will fill a claim. Documented safety practices can help show that you’re managing risks and improve your risk profile. I suggest you start with these:

    • Hurricane preparedness protocols: Secure outdoor equipment before storms and document how your business prepares for severe weather.
    • Heat safety training: Train employees who work outdoors to recognize heat illness and follow safe work practices during hot weather.
    • Lightning safety procedures: Set clear rules for stopping outdoor work during thunderstorms, especially for construction or landscaping crews.
    • Mold prevention documentation: Keep records of HVAC inspections and humidity-control measures if your business operates in enclosed or moisture-prone spaces.

Affordable General Liability Insurance in Florida: Bottom Line

The Hartford, ERGO NEXT and biBerk offer some of Florida’s cheapest general liability rates, but statewide rankings only show where to start. Industry pricing helps you see which insurers may charge less for businesses like yours, while coverage requirements show whether a low-priced policy will actually meet your needs. The fairest price comparison comes when policies offer the same level of protection, because then you’re comparing insurers rather than different amounts of coverage.

Cheapest General Liability Insurance in Florida Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

Chances are, you'll need more than general liability to make sure your Florida business has enough financial protection. With more policies in your mix, finding affordable coverage becomes even more important. I've put together some resources that shows which have low-cost premiums for other coverage types.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com