
Best Professional Liability Insurance (E&O) Companies in Florida

Our analysis of Florida professional liability insurers found three providers that consistently outperformed the field on rates, coverage quality and customer experience.

  1. ERGO NEXT: A fully digital buying process, 24/7 certificate of insurance access and rates that beat the Florida average by 25% earned ERGO NEXT the top position. The insurer ranks first for professional liability across most Florida industries, including consulting, financial services, healthcare, tech, construction and pet care. Education businesses should look elsewhere, where ERGO NEXT ranks seventh in the state.
  2. The Hartford: Responsive claims handling and an industry-specific underwriting approach set The Hartford apart, particularly for Florida's beauty, wellness, cleaning, real estate and tech businesses, where it ranks first or second. With more than 200 years in operation, the insurer brings dedicated service teams and a complaint rate 22% below the national average. It underperforms for healthcare and other professional services, where it ranks ninth in Florida.
  3. Hiscox: Founded in 1901, Hiscox built its reputation on specialist professional liability coverage, and that depth shows for Florida education providers, consultants, nonprofits, financial services firms and childcare operators, where it ranks first or second. Its professional liability policies cover work performed anywhere in the world, which suits Florida businesses with clients across state lines or internationally.

These three providers are the best fit for most Florida businesses, but no single ranking accounts for every variable in your situation. Comparing business insurance options side-by-side and getting quotes directly from carriers gives you the clearest picture of what your business will actually pay.
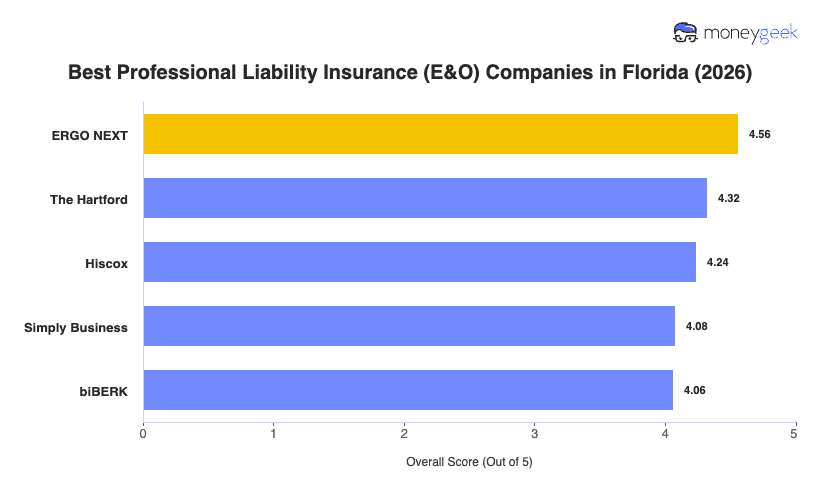
ERGO NEXT4.5611$45
The Hartford4.3234$50
Hiscox4.2447$49
Simply Business4.0892$56
biBERK4.0689$58

How to Get the Best Professional Liability Insurance in Florida

Start getting professional liability coverage by working through these seven steps built for Florida businesses.

  1. 1

    Check your FL licensing board requirements first

    Find whether your profession has a mandatory coverage floor set by a Florida licensing board before comparing quotes. Licensed physicians must show financial responsibility with minimum malpractice coverage of $100,000 per claim and $300,000 aggregate without hospital privileges, contractors licensed through the DBPR must meet public liability minimums, and the Florida Bar requires attorneys to report coverage annually. Verify any carrier is authorized in Florida through the Office of Insurance Regulation company search.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on who your clients are, what your contracts require and how much a claim could cost. Use $250,000 to $500,000 for freelance consultants, marketing agencies, fitness instructors and cleaning services, $500,000 to $1 million for IT consultants, attorneys, CPAs, real estate pros and nonprofits, and $1 million to $2 million for physicians, architects, engineers, financial advisers and childcare operators. Enterprise clients in Miami and Tampa commonly require $1 million minimums, which helps set how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the FL market

    Florida's regional markets vary enough that a local agent with industry experience adds real value. Miami's international finance firms have different needs than Tampa's healthcare and logistics sector or Orlando's hospitality and aerospace businesses. Seek agents who regularly place professional liability coverage for your industry in your metro, since they know which carriers underwrite it competitively and which decline or surcharge it.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Premium comparisons alone won't tell you enough, so review policy terms side by side, checking exclusions, deductibles, limits and whether the policy covers prior acts. One carrier may exclude regulatory investigation costs while another covers them, a meaningful difference in Florida's active licensing environment. Pull quotes from at least three carriers and weigh what each policy actually covers before deciding, since comparing quotes on price alone can hide the terms that matter most.

  5. 5

    Research providers beyond price

    Confirm the carrier is licensed to write professional liability business in Florida, then check its claims handling record and financial stability. Industry associations tied to Florida's major sectors, including the Florida Bar, the Florida Medical Association and the Florida Chamber of Commerce, can point you toward carriers with proven track records in the state.

  6. 6

    Consider bundling with other business coverage

    Pairing professional liability with general liability or a business owner's policy often cuts total premiums by 10% to 15%. Using a single carrier also simplifies renewals and certificate of insurance management.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Florida professional liability policies are almost always written on a claims-made basis, so coverage applies only to claims filed while the policy is active, and the policy's retroactive date sets how far back covered work reaches. Switching carriers or letting coverage lapse can leave past work uncovered, a sharp risk in the high-litigation Miami-Dade, Broward and Palm Beach region. Purchase prior acts or tail coverage when switching insurers to close that gap.

Best Florida Professional Liability Insurance (E&O): Bottom Line

The right professional liability coverage in Florida depends on your industry, the size of your client contracts and your budget. ERGO NEXT takes the top overall rating for Florida businesses, but your profession, coverage limits and regional market should decide the final call. Verify your licensing board's requirements first, then compare quotes from at least three carriers before you commit.

Best Professional Liability Insurance Florida Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best FL small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance FL: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources