


Jump to the section that meets your needs best:
Average Professional Liability Insurance Cost (2026 Report)
Average professional liability insurance costs range anywhere from $19/mo to $166/mo. Most small businesses pay between $30/mo to $70/mo, but pricing can vary widely depending on industry, business size and location.
If you're ready to buy, get matched to the best professional liability insurer for your business with the tool below.
Select state
Updated: September 8, 2026
Advertising & Editorial Disclosure
Featured Partner
The Hartford
- The Hartford is MoneyGeek's cheapest professional liability insurer for 2026, at $45 a month, 20% below the $56 industry average for a business with one to four employees.
- In MoneyGeek's analysis, The Hartford's professional liability rates run up to 46% below the industry average for consulting, tech and financial services firms.
- In 16 states, most of them in the Northeast, The Hartford's professional liability rates are the lowest MoneyGeek analyzed.
- For that same one-to-four-employee profile, The Hartford remains the cheapest option analyzed, with the industry averaging $675 a year.
On The Hartford's site
*MoneyGeek featured partner. Editorial rankings below are independent of this placement. Rates, rankings and savings comparisons are based on MoneyGeek's independent research and Hartford-reported data as of 2026. Figures are estimates and averages, not a guarantee of any individual quote, premium or discount.
How Much Does Professional Liability Insurance Cost on Average?
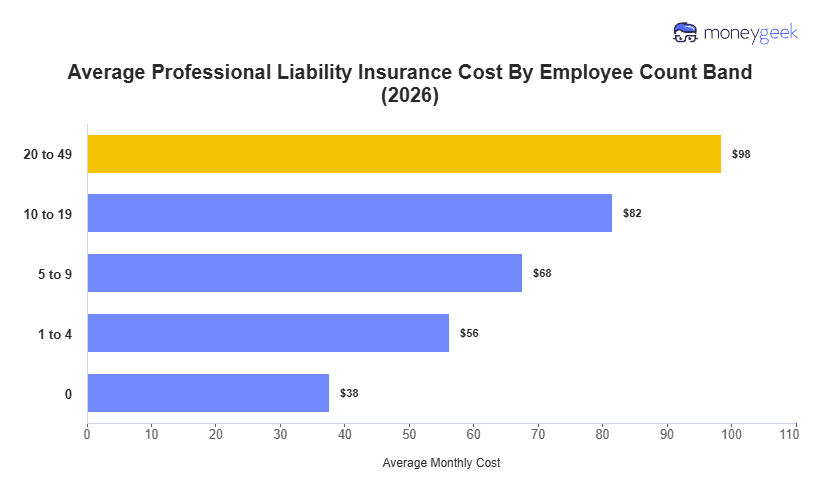
At the national level, professional liability insurance costs sit at $56/mo or $675/yr on average for a 1-to-4-person small business getting a $1 million per claim and $2 million aggregate policy.
This average price is aggregated across 151 industries and all states and territories in the United States we studied that represent most small companies that need coverage based their actual service risk. Keep in mind this national cost may not apply to you and it should be used as a starting point rather than an actual quote.
For more personalized small business insurance cost estimates, you can use our professional liability insurance calculator below.
To estimate average professional liability insurance costs, we analyzed quote data from major U.S. small business insurance providers and modeled standardized premium estimates across common professional service profiles. These modeled results are designed to provide a consistent national benchmark and show how premiums vary by key baseline factors including business size, profession type, and location.
Dataset Scope and Assumptions
Our cost modeling uses standardized inputs for consistent comparisons across businesses.
- Providers analyzed: 10 major insurance providers
- Professions covered: 151 professional service categories
- Geography: all U.S. states (including Washington, D.C.)
- Employee count bands: solo practitioners, one to four, five to nine, 10 to 19, and 20 to 49 employees
- Policy baseline: standard errors & omissions (E&O) / professional liability policy with $1 million per claim / $1 million aggregate limits
- Total estimates modeled: just over 1 million standardized pricing estimates
We also incorporated modeled average revenue, payroll, and claims history personalized across all combinations of states, profession type, and employee counts to improve the accuracy of pricing. To model these assumptions against our cost factors, we used data from these sources:
- CBP (for employee size class density by state + NAICS)
- QCEW (for wage/payroll intensity by profession + geography)
- Economic Census / SUSB (for receipts/output intensity by profession)
- Calibrated against:
- Private comp databases
- IRS SOI totals
How We Calculated Average Professional Liability Costs
Our published averages represent modeled premiums for standardized professional service profiles and were aggregated in two ways:
- National benchmark average: The national average cost reflects the modeled premium for a standardized one to four-employee professional services business across all professions and states included in our dataset for a standard professional liability policy.
- Segment averages: To show how costs vary, we calculated average modeled premiums for our national base profile and isolated for variables, including:
- Employee count (business size ranges)
- Profession / industry categories
- States (including Washington, D.C.)
Segment averages were produced by aggregating modeled pricing trends across the full dataset so readers can compare how premiums shift across profession types and regions.
Get Professional Liability Insurance Cost Estimates
Use our business insurance calculator below to get estimates for professional liability insurance, personalized to your industry, state and business size.
Professional Liability Insurance Cost Estimate Calculator
Select General Industry
Select State
Select Employee Count
Monthly rate estimate—
Select General Industry
Monthly rate estimate—
Select State
Select Employee Count
What Factors Affect Professional Liability Insurance Costs
The main factors that affect your professional liability insurance costs as currently and as your business grows are your industry, location and employee count. All of these details together influence the possible frequency of claims and the possible severity involved regarding errors/omissions in professional work, faulty advice given and failures to follow through with contractual obligations.
Our costs models follow these factors as the core of our professional liability pricing analysis. Below we explain each of these factors, why they influence costs and how much we found they affected them.
 Industry Area
Your industry is the strongest baseline factor in determining your professional liability insurance cost. This is primarily due to your area of work determining the types of services you provide and as such determines the damage you can do to clients and customers for not fulfilling contractual obligations, providing faulty advice or making professional mistakes/omissions.
In our study, cleaning services have the lowest average costs sitting 67% below the national average due to most risks being related to bodily injury or completed operations coverage for general liability policies. On the opposite end, childcare services are the highest cost industry area at 195% above average due to the vast majority of lawsuits being about negligence in regard to client's children.
 Business Size
Your business size or number of employees is the second most influential factor that affects your professional liability premiums. The logic behind this is simple, the more people that can make professional mistakes the higher pricing will be. As businesses grow larger, it is also harder to manage service quality which often causes more professional mistakes and negligence to happen.
Compared to a 1-to-4-person business, a 20 to 49 employee business is 75% higher on average to insure with a professional liability policy.
 Location
State is the least influential of our baseline factors affecting professional liability costs. It's determining factors are much more indirect and relate to the differing legal environments in states in regard to settlement amount and likelihood of higher cost and nuclear verdicts.
The spread was tight in our study and the lowest cost state was only 11% lower than national benchmarks (North Dakota) while the highest cost state sits only 15% higher (New York)
How to Lower Professional Liability Insurance Costs
Most businesses can lower professional liability premiums through a mix of quick fixes and longer-term strategies. Here are the most practical options for getting cheap professional liability coverage without cutting the coverage you need.
Quick Professional Liability Cost Lowering Methods
You can use these quick methods to lower your costs for professional liability insurance.
 Provide clean and accurate underwriting information
The easiest way to save the most on any business insurance, including professional liability insurance, is by making sure your company is classified correctly. This means ensuring that the industry codes, revenue, payroll, employee count, claims information, and operations descriptions are properly detailed so insurers can price most accurately. Having an improper industry code is the most common issue here and a mistake can influence rates by more than 30%.
 Determine how much professional liability insurance you need
Finding out how much professional liability insurance is needed for your small businesses sets you up to not overpay for coverage or exclude it entirely from consideration based on your actual risk. Consider the work you do and whether it lines up with what professional liability policies cover, the value of and types of clients/customers you have, and the legal environment surrounding your profession and work case scenarios.
 Only get minimum required professional liability insurance
If you can't afford the coverage you need, going with minimum professional liability insurance requirement amounts is the right choice. Ensure you meet state licensing requirements and any terms present in client contracts, so you are compliant.
 Compare multiple insurers
We found that it is possible to get savings of over 40% on average if you compare multiple providers and find the cheapest for your profile. When comparing quotes, make sure you look at 3 to 5 providers that you shortlist based on affordability, customer experience and coverage to get the best deal.
- Bundle professional liability insurance with other policies
Bundling on average saves you anywhere from 10% to 15% on average. So when getting any business insurance policy, consider bundling policies together with professional liability insurance with the same company.
 Pay annually instead of monthly
Especially as policy premiums go up as your business grows, paying annually for professional liability and other business insurance types can save you money. Often savings are between 5% and 10%, but can reach higher depending on the total cost of your policy.
Long-term Professional Liability Cost Lowering Strategies
These long-term cost lowering strategies will help ensure your professional liability insurance rates are cheap over time.
Professional Liability Insurance Cost: Bottom Line
Professional liability premiums reflect how insurers read your firm's specific risk: what you do, who your clients are, your location's legal environment, your claims history and the systems you have in place to prevent errors.
A national average is only a starting point. What matters is knowing where your premium sits relative to your actual risk profile and why.
Three questions put that into practice:
Apply this report by asking three questions:
- Does my premium reflect my actual risk? Take into account your profession, services offered, client types, revenue and claims history, not just whether your number is above or below average.
- What is driving my cost right now? Separate your baseline risk factors (profession, business size, state, prior claims) from coverage design choices (limits, deductible, retroactive date, tail coverage). Each requires a different response.
- What would meaningfully change my price and over what timeline? Some levers work at the next renewal; others compound over years. Knowing which is which helps you prioritize.
Use these questions to evaluate quotes and coverage based on whether they accurately reflect your risk profile, not just whether the number feels high or low. The goal isn't the cheapest policy. It's the right coverage, with the right provider, at a price that reflects how well-run your firm actually is.
If you're interested in other business insurance policy costs
We've left resources below for average costs for common business insurance policies:
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com