Best Professional Liability Insurance (E&O) Companies in Maryland

Our analysis of Maryland professional liability insurers found three providers that consistently outperformed the rest on overall score:  

  1. ERGO NEXT holds the top overall score in Maryland, backed by the strongest customer experience rating and the best coverage score in the state. The buying process is fully digital. You get a quote, bind coverage and download your certificate without waiting for a callback or going through a broker. That matters for Maryland's large population of independent contractors and solo practitioners who need proof of coverage on short notice for a client contract. ERGO NEXT ranks first in Maryland for healthc are, fitness, pet care, real estate and other professional services. Engineers, architects and large construction operations aren't a good fit, since the insurer's underwriting skews toward smaller service businesses.
  2. The Hartford earns the second-place ranking for its profession-specific underwriting, which most carriers can't match. For Maryland businesses in consulting, financial services, tech, marketing and hospitality, The Hartford ranks first in the state across all of those industries, which means it prices competitively and structures coverage well for the specific claim types those professions see. The exception is health care and other professional services, where it ranks ninth in Maryland, well behind the field. Medical practices should look elsewhere.
  3. Hiscox covers more industries than any competitor and prices well for the ones where it leads. In Maryland, it ranks first in childcare, cleaning services, and nonprofits, and its coverage score remains strong even at lower price points. A small nonprofit in Baltimore or a childcare facility in Annapolis should pull a Hiscox quote first. Sole practitioners and firms under 10 employees across any industry will find it easier to buy here than through most traditional carriers.

These three providers suit most Maryland businesses well, but no ranking replaces side-by-side comparison. Comparing business insurance options across carriers before you buy gives you the clearest read on price and fit.
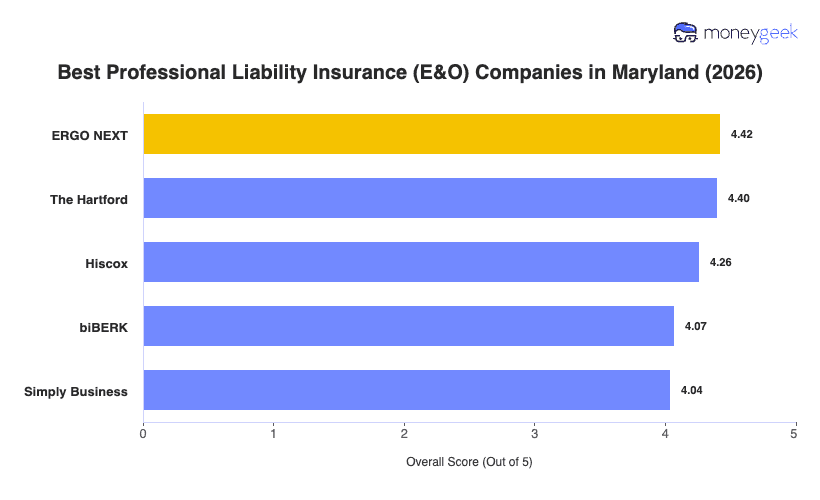
ERGO NEXT4.4211$50
The Hartford4.4034$41
Hiscox4.2647$46
biBERK4.0779$52
Simply Business4.0492$52

How to Get the Best Professional Liability Insurance in Maryland

Start getting professional liability coverage by matching your policy to your profession, your clients and the contracts you sign.

  1. 1

    Check your MD licensing board requirements first

    Confirm whether your profession has a mandatory coverage floor set by a Maryland board. Real estate licensees must carry E&O of at least $100,000 per claim and $500,000 aggregate, and insurance producers must hold E&O as a condition of licensure. Verify any carrier is admitted in the state through the Maryland Insurance Administration.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on who your clients are, what your contracts require and how large a claim could get. Use that to frame how much professional liability insurance you need, from $250,000 for lower-risk service providers up to $2 million for physicians, engineers and public-project contractors.

  3. 3

    Work with a local agent who knows the MD market

    Maryland's risk profile shifts by region, from Baltimore's health care, biotech and logistics base to the federal contractors and consulting firms clustered in Montgomery County. Pick an agent who works in your industry and knows what local clients and agencies require in contracts right now.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Rate alone won't tell you what you're buying. Compare whether defense costs sit inside or outside the limit, what the deductible and exclusions cover and whether the retroactive date reaches all your prior work. A firm serving federal agencies should confirm government contract work is covered.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Confirm the carrier is admitted in Maryland, since a non-admitted insurer offers no state guaranty fund protection if it fails. Then review how it handles claims in your profession, and compare any endorsed association programs against open-market quotes.

  6. 6

    Consider bundling with other business coverage

    Combining professional liability with general liability or a business owner's policy can trim your total premium by 10% to 15%. Ask each carrier whether a packaged BOP changes the rate on the professional liability piece.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Maryland policies are almost universally claims-made, so the policy in force when a claim is filed responds, not the one active when the error occurred. A lapse or a reset retroactive date can leave past work unprotected. If you retire, sell or switch carriers, buy tail coverage and confirm your retroactive date carries over.

Best Maryland Professional Liability Insurance (E&O): Bottom Line

ERGO NEXT earns the top overall rating in Maryland, but the right pick depends on your industry, the size of your client contracts and what your largest clients or licensing board require you to carry. A solo real estate agent in Annapolis and a health care consulting firm in Baltimore both need coverage, and each could land on a different carrier and limit. Pull quotes from at least three providers, confirm each is licensed through the Maryland Insurance Administration and compare policy terms before you buy, not after a claim arrives.

Best Professional Liability Insurance Maryland Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best MD small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance MD: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources