


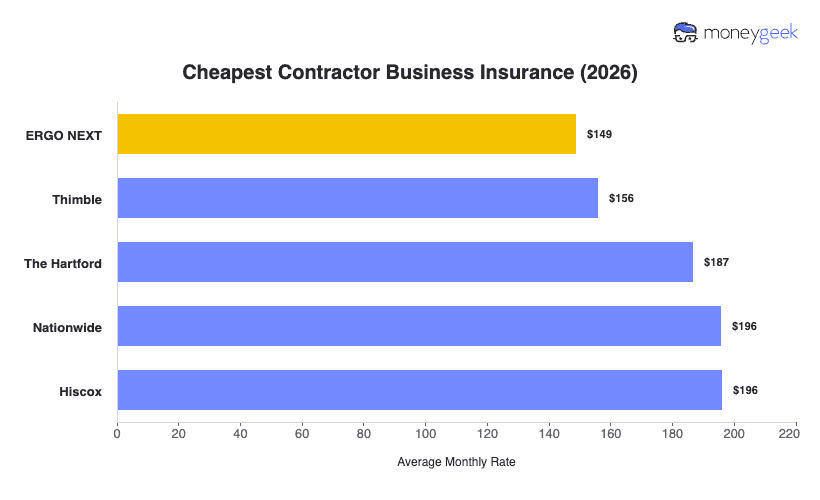
ERGO NEXT offers the cheapest business insurance for most contractors at $149 per month, but the gap between the top five providers is narrow enough that your trade, state and crew size can shift which carrier actually prices lowest for your profile. See how all five providers compare below:
Cheap Contractor Business Insurance
ERGO NEXT, Thimble and The Hartford offer the lowest rates for contractor business insurance, and premiums can start as low as $62 per month. The cheapest provider for your contracting business depends on your trade, crew size, location and the coverage types your contracts require.
Need proof of insurance fast? Save up to 30% with your cheapest contractor insurer match with our tool below.
Select state
Updated: September 14, 2026
Advertising & Editorial Disclosure
Cheapest Contractor Business Insurance Companies
| ERGO NEXT | $149 | $1,785 |
| Thimble | $156 | $1,871 |
| The Hartford | $187 | $2,243 |
| Nationwide | $196 | $2,349 |
| Hiscox | $196 | $2,356 |
How We Determined the Cheapest Contractor Business Insurance Providers
Contractors cover everything from solo handyman jobs to full-crew roofing, electrical and HVAC operations, and that spread changes how carriers price risk. A plumber running a two-person shop faces different exposure than a general contractor managing commercial build-outs with a 20-person crew. Each breakdown covers which provider prices lowest by coverage type and sub-industry, and where strong lower-cost alternatives exist.
Cheapest Contractor Business Insurance by Contractor Profession
Your trade is the single biggest factor in which carrier prices lowest. ERGO NEXT dominates the core field trades (including general contracting, plumbing, electrical, HVAC and painting), while Thimble takes the lead in specialty and seasonal work like tree surgery, restoration and snow removal. That split tracks with how carriers assess physical risk versus project-based exposure.
See how the cheapest provider breaks down by contractor profession in the table below:
| Arborist | ERGO NEXT | $115 | $1,384 | $0 |
| Architecture Firm | The Hartford | $91 | $1,097 | $0 |
| Artisan Contractor | ERGO NEXT | $133 | $1,593 | $0 |
| Asbestos Contractor | ERGO NEXT | $228 | $2,736 | $0 |
| Carpentry | Thimble | $183 | $2,201 | $0 |
| Concrete Contractor | ERGO NEXT | $229 | $2,750 | $0 |
| Demolition Contractor | ERGO NEXT | $195 | $2,337 | $0 |
| Door and Window Installation | Thimble | $160 | $1,923 | $0 |
| Drywall Contractor | ERGO NEXT | $168 | $2,013 | $0 |
| Electrical Contractor | ERGO NEXT | $147 | $1,758 | $0 |
| Engineering Firm | ERGO NEXT | $94 | $1,128 | $0 |
| Excavation Contractor | ERGO NEXT | $205 | $2,461 | $0 |
| Fence Installation | ERGO NEXT | $137 | $1,648 | $0 |
| Fire Sprinkler Contractor | ERGO NEXT | $172 | $2,061 | $0 |
| Flooring Installation | ERGO NEXT | $141 | $1,688 | $0 |
| General Contractor | ERGO NEXT | $148 | $1,779 | $0 |
| Glazier/Glass Contractor | ERGO NEXT | $175 | $2,104 | $0 |
| Handyman Services | ERGO NEXT | $172 | $2,059 | $0 |
| Home Improvement Contractor | ERGO NEXT | $165 | $1,980 | $0 |
| HVAC Contractor | ERGO NEXT | $154 | $1,847 | $0 |
| Insulation Contractor | ERGO NEXT | $172 | $2,069 | $0 |
| Interior Design | Thimble | $64 | $764 | $0 |
| Irrigation Services | Thimble | $113 | $1,352 | $0 |
| Land Surveying | ERGO NEXT | $70 | $842 | $0 |
| Lawn Care Service | Thimble | $122 | $1,460 | $0 |
| Masonry Contractor | ERGO NEXT | $191 | $2,290 | $0 |
| Painting Contractor | ERGO NEXT | $139 | $1,669 | $0 |
| Paving Contractor | ERGO NEXT | $184 | $2,208 | $0 |
| Pest Control | ERGO NEXT | $100 | $1,205 | $0 |
| Plumbing Contractor | ERGO NEXT | $150 | $1,804 | $0 |
| Railroad Contractor | ERGO NEXT | $209 | $2,508 | $0 |
| Remodeling Contractor | ERGO NEXT | $169 | $2,022 | $0 |
| Restoration Contractor | Thimble | $187 | $2,250 | $0 |
| Roofing Contractor | ERGO NEXT | $241 | $2,892 | $0 |
| Sandblasting Contractor | ERGO NEXT | $206 | $2,476 | $0 |
| Septic Services | ERGO NEXT | $175 | $2,100 | $0 |
| Siding Contractor | ERGO NEXT | $149 | $1,784 | $0 |
| Snow Removal Service | Thimble | $128 | $1,536 | $0 |
| Solar Contractor | ERGO NEXT | $144 | $1,722 | $0 |
| Tile Contractor | ERGO NEXT | $142 | $1,710 | $0 |
| Tree Service | ERGO NEXT | $135 | $1,623 | $0 |
| Tree Surgeon | Thimble | $136 | $1,635 | $0 |
| Utility Contractor | ERGO NEXT | $180 | $2,160 | $0 |
| Waterproofing Contractor | ERGO NEXT | $140 | $1,680 | $0 |
| Welding Contractor/Shop | ERGO NEXT | $188 | $2,251 | $0 |
If you want to see the cheapest options by subindustry, we prepared resources showing affordable options to find the best fit for your budget:

Cheapest Contractor Business Insurance By Coverage Type
What you're buying matters as much as who you're buying from. Most contractors need general liability and workers' comp at minimum, but businesses with vehicles, expensive job-site equipment or design-build contracts may also need commercial auto, commercial property and professional liability.
General liability and workers' comp tend to be the most expensive lines for contractors because field trades carry significant on-site injury and property damage risk. The cheapest provider for each coverage type can differ from the cheapest overall insurer, so comparing by coverage type gives you a more complete picture.
General Liability | ERGO NEXT | $262 | $3,146 | 22% |
Workers' Comp | ERGO NEXT | $224* | $2,693* | 30% |
Professional Liability | ERGO NEXT | $72 | $865 | 14% |
Commercial Auto | Progressive Commercial | $151 | $1,811 | 22% |
Commercial Property | ERGO NEXT | $99 | $1,186 | 24% |
Cyber Insurance | Chubb | $62 | $739 | 18% |
We prepared resources for each coverage type so you can compare providers and find the most affordable option:


Is the Cheapest Insurance Right for Your Contracting Business?
Cheap coverage can work well when the policy actually fits how your business operates and holds up against the standards of the best business insurance for contractors. These four factors help you evaluate whether a lower-cost option is enough for your operation:
- Coverage limits: General contractors and commercial clients often require $1M/$2M minimum limits, and a policy that prices low by capping coverage at $500,000 can disqualify you from the projects you're bidding on.
- Deductibles: Contracting work produces claims that range from stolen tools to job-site property damage, so a high deductible can wipe out whatever you saved on your premium after a single incident.
- Add-ons: Tools and equipment coverage, inland marine and professional liability aren't always included in a base policy, but a general contractor managing subcontractors or an electrician doing commercial work may need all of them to satisfy contract requirements.
- Claims handling and customer service: When a contractor gets hit with a property damage or injury claim mid-project, slow claims support can stall work, damage a client relationship and cost more than the premium savings were worth.
How to Get More Affordable Coverage Without Being Underinsured
Finding cheap contractor business insurance doesn't mean accepting gaps in your coverage. It means building your policy strategically so you're not overpaying for protection you need. These six strategies can help you lower your premium without leaving your operation exposed.
 Get quotes before you talk to a broker, not after
Independent brokers work with a limited carrier panel, and the carriers that price most competitively for contractors, particularly ERGO NEXT and Thimble, sell direct and aren't always represented. Start with direct quotes from the carriers that lead for your trade and state, then use a broker to fill any gaps in specialty coverage.
 Check your business classification code
Insurers price contractor policies by trade classification, and the wrong code can raise your cost of contractor business insurance well beyond what your actual risk warrants. A handyman doing light residential work who gets classified under general contracting, or an artisan contractor grouped with industrial operations, may be overpaying by $50 per month or more. Ask your carrier to confirm the code matches your primary trade.
 Raise your deductible strategically
A higher deductible lowers your monthly premium, but it works best for contractors with clean claims histories and lower on-site damage risk. A solo painter with no prior claims may benefit from the trade-off, while a roofing crew working high-value commercial properties may want to keep the deductible low to avoid a large out-of-pocket hit on a single claim.
 Compare quotes using the same coverage limits
Rate comparisons only hold up when the coverage underneath is identical. Contractors often carry different liability limits depending on whether they work residential or commercial accounts, so a $500,000 quote won't compare fairly against a $1 million quote. Lock in the same limits, deductibles and coverage types before comparing small business insurance quotes from multiple carriers.
 Pay annually if your work isn't seasonal
Most carriers charge an installment fee on monthly payments, which adds to your total cost over the year. Paying your premium upfront in a single annual payment removes that fee. The caveat for contractors: if your workload drops in winter or you scale up and down by project, paying annually on a policy you may want to adjust mid-term can cost more than the fee you're avoiding. Confirm the carrier's refund and mid-term adjustment policy first.
 Adjust your coverage when your crew size changes
Workers' comp is priced directly on payroll and headcount, so a contractor who's downsized from a crew of eight to three, or shifted from W-2 employees to subcontractors, may still be paying premiums based on the old numbers. Carriers don't adjust downward automatically. An annual policy review tied to your actual crew and payroll can produce meaningful savings without switching carriers or dropping coverage.
Cheap Contractor Insurance: Bottom Line
Contractor insurance costs vary sharply by trade, state and crew size, and the cheapest overall provider won't be the cheapest for every profile. A solo handyman working residential jobs faces fundamentally different risk and different pricing than a general contractor managing commercial build-outs with company vehicles and a full crew. The right measure of cheap isn't just the lowest premium. It's the lowest premium that still covers how your business actually operates.
How We Determined the Cheapest Contractor Business Insurance Providers
To identify the cheapest contractor business insurers, real pricing data from seven major providers was analyzed and standardized pricing estimates were modeled across common U.S. contractor business profiles.
Dataset scope and assumptions
- Providers analyzed: 7 major insurance providers
- Sub-industries covered: 45 contractor sub-industries
- Geography: all U.S. states and territories (including Washington, D.C.)
- Employee count bands: 0, 1-4, 5-9, 10-19 and 20-49 employees
- Policy baseline: standard $1 million per occurrence / $2 million aggregate for all coverage types except workers' comp, which uses state-mandated coverage limits
- Pricing estimates modeled: 196,000 total estimates
Modeled average revenues and payrolls across contractor business profiles were also incorporated to improve pricing accuracy.
How we determined which provider was "cheapest"
This dataset was used to determine which insurers were most often the lowest-cost option across different contractor business profiles. The "cheapest" rankings include both:
- General Recommendation: Provider rankings based on average estimated pricing for a standardized 1-4 employee business profile across all contractor sub-industries in the dataset.
- Factor Combination Recommendations: Provider rankings based on which insurer was most often cheapest within specific business factor combinations. For example:
- Contractor sub-industry pricing was compared using a standardized 1-4 employee profile
- Coverage type affordability was derived by comparing aggregated pricing trends across contractor sub-industries
Important note: These results represent standardized pricing estimates, not personalized quotes. Actual pricing can vary based on your business classification, revenue/payroll, claims history and the specific limits, deductibles and endorsements you choose. For the most accurate cheapest-provider answer, we recommend comparing quotes apples-to-apples using the same coverage limits.
About Connor Bolton

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.
The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.
Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.
Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.