

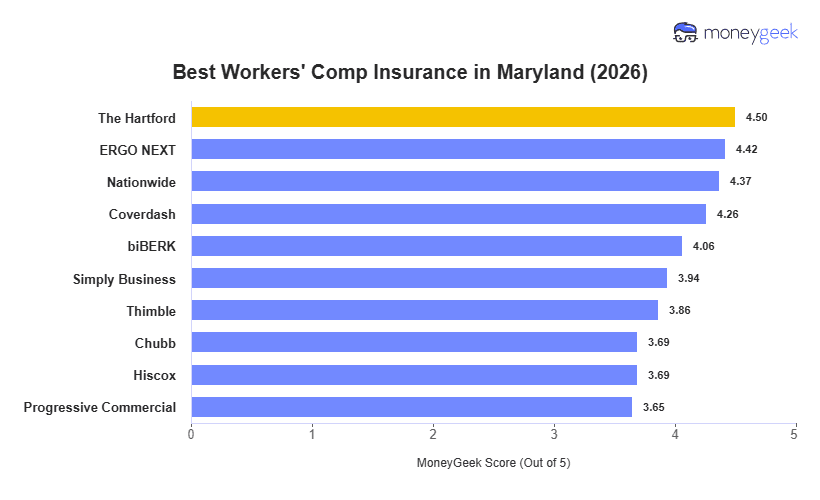
My analysis of 10 major insurers showed that The Hartford is the best workers' compensation insurance company in Maryland. Its average premium is around 19% lower than the state average, which saves you around $23 per month or $278 per year. The Hartford provides solid post-purchase support, from agents that can assist with any changes you need on your policy to teams that specialize on different industries.
Best Workers' Comp Insurance in Maryland (2026)
With rates as low as $10 monthly, The Hartford, NEXT and Nationwide offer the best workers' comp insurance in Maryland.
With our matching tool, MoneyGeek can can connect you to top Maryland workers' comp providers for your business.
Select state
Safe & SecureVerified and VettedTrusted Brands
Updated: August 27, 2026
Advertising & Editorial Disclosure
Best Workers' Comp Insurance Companies in Maryland
| The Hartford | 4.50 | $96 | 3 | 3 |
| ERGO NEXT | 4.42 | $96 | 1 | 6 |
| Nationwide | 4.37 | $95 | 6 | 5 |
| Coverdash | 4.26 | $112 | 5 | 1 |
| biBERK | 4.06 | $112 | 8 | 8 |
MoneyGeek analyzed workers' comp insurance rates and provider performance across Maryland using small business profiles with one to four employees spanning 408 major industries. Companies earn up to five points in each category in our scoring system. We then use a weighted average of these category scores to calculate a MoneyGeek score out of five.
- Affordability (55%): Based on average payroll for the most common employee code per industry and state classification, priced per employee for a one to four employee business.
- Customer Experience (35%): Evaluates buying (20%), which covers quote access, pricing accuracy and sales support; policy management (30%), which covers payroll reporting, audits, billing and loss control; and claims (50%), which covers FNOL speed, adjuster support, medical access, wage replacement and dispute handling.
- Coverage Options (10%): Assesses coverage completeness (35%), including employers' liability and wage and medical reimbursement; policy flexibility and endorsements (25%); eligibility, state and industry breadth (20%); and policy terms, limits and exclusions (20%).

The Hartford
Best Workers' Comp Insurance in Maryland
MoneyGeek Rating
4.5/ 5
4.3/5Affordability Score
4.1/5Customer Experience Score
4.5/5Coverage Score
Average Monthly Cost
$96Claims Processing Score
4.1/5Policy Management Score
4/5Buying Process Score
4/5

ERGO NEXT
Best Maryland Workers' Comp Insurance: Runner-Up
MoneyGeek Rating
4.4/ 5
4.3/5Affordability Score
4.4/5Customer Experience Score
3.9/5Coverage Score
Average Monthly Cost
$96Claims Processing Score
4/5Policy Management Score
4.1/5Buying Process Score
4.4/5
Cheapest Workers' Comp Insurance Companies in Maryland
The Hartford and ERGO NEXT offer the cheapest workers' comp rates across most Maryland industries. The Hartford leads 13 industries and ERGO NEXT leads 10, with biBerk and Coverdash each winning one specialty category. The Hartford prices lowest for office-based industries with lower injury exposure. ERGO NEXT is the better choice for physical, trade-heavy work where injury risk runs highest.
| Agriculture & Natural Resources | ERGO NEXT | $160 | $1,920 |
| Arts, Media & Entertainment | ERGO NEXT | $92 | $1,104 |
| Beauty, Body & Wellness Services | The Hartford | $12 | $144 |
| Childcare Services | biBERK | $35 | $420 |
| Cleaning Services | The Hartford | $106 | $1,272 |
| Construction & Contracting | ERGO NEXT | $229 | $2,748 |
| Consulting Services | The Hartford | $15 | $180 |
| Education | ERGO NEXT | $64 | $768 |
| Financial Services | The Hartford | $10 | $120 |
| Fitness Services | Coverdash | $64 | $768 |
| Food & Beverage | ERGO NEXT | $40 | $480 |
| Healthcare & Medical | The Hartford | $39 | $468 |
| Hospitality, Travel & Tourism | The Hartford | $36 | $432 |
| Manufacturing | The Hartford | $128 | $1,536 |
| Marketing & Communications | The Hartford | $13 | $156 |
| Nonprofit & Associations | The Hartford | $51 | $612 |
| Other Professional Services | The Hartford | $20 | $240 |
| Pet Care Services | ERGO NEXT | $61 | $732 |
| Real Estate & Property Services | The Hartford | $16 | $192 |
| Recreation & Sports | ERGO NEXT | $107 | $1,284 |
| Repair & Maintenance | ERGO NEXT | $70 | $840 |
| Retail & Product Rental | The Hartford | $45 | $540 |
| Tech/IT | The Hartford | $31 | $372 |
| Transportation & Logistics | ERGO NEXT | $292 | $3,504 |
| Wholesale & Distribution | ERGO NEXT | $185 | $2,220 |
How to Get the Best Workers' Comp Insurance in Maryland
Find out how to get workers' comp insurance with the right provider at the best price.
- 1Confirm Maryland Coverage Requirements
Maryland’s workers’ compensation requirement begins when you hire one covered employee, including someone who works part time. Sole proprietors and partners are excluded automatically unless they elect coverage. Certain corporate officers and LLC members can also opt out, but they must file a formal exclusion with the Workers’ Compensation Commission.
- 2Identify Your NCCI Class Codes
Most Maryland insurers use NCCI class codes and state-approved loss costs as the foundation for their rates. The code should describe your business operation and its injury risk, not simply an employee’s title. Separating payroll between classifications matters because each code carries its own rate per $100 of payroll.
- 3Document Payroll, Employee Count and Claims History
Record payroll by class code and note which owners have elected coverage or filed exclusions. Insurers will also request loss runs, which show your previous workers’ comp claims and their costs. Using the same employee count, payroll period and ownership treatment for every application prevents conflicting quotes.
- 4Request Quotes From Multiple Licensed Maryland Carriers
Maryland combines competitive private insurance with a state-created insurer of last resort. Start by comparing business insurance quotes from licensed carriers willing to cover your operations. If your claim history or type of work limits those options, Chesapeake Employers Insurance Company must provide coverage to eligible businesses that cannot obtain it in the open market.
- 5Compare on Quality, Not Just Price
Maryland gives an injured employee the right to choose a medical provider, so a large preferred-provider network should not drive your decision by itself. Look at how quickly the carrier authorizes treatment, pays medical bills and keeps you informed about work restrictions. Those services help you coordinate an employee’s return without interfering with their provider choice.
- 6Complete Purchase and Establish Payroll and Audit Reporting
Once you bind the policy, confirm its payroll-reporting method and display Maryland’s workers’ comp notice where employees can see it. Create a reporting process before an injury occurs. If an accident causes more than three days of disability or death, you must report it to the Commission within 10 days after receiving notice.
- 7Review at Annual Renewal
Reconcile the insurer’s audited payroll with your records before renewing. Then review your experience modification rating, or e-mod, which compares your recent claims with those of similar businesses. Maryland insurers generally update this factor each year using the latest three-year claims period, so unresolved claim estimates can affect your next premium.
Best Workers' Compensation Insurance in Maryland: Bottom Line
The Hartford, ERGO NEXT and Nationwide rank as Maryland's top workers' comp insurers. Businesses should research each company's service quality, maximize discounts and select coverage that fits your budget.

LEARN MORE ABOUT MARYLAND BUSINESS INSURANCE
You'll need more coverages in your Maryland business insurance policy than workers' compensation. If you want to see which providers we recommend, you can find resources below:
Maryland Workers' Compensation Insurance FAQ
The Hartford is the best workers' comp insurance in Maryland. Nationwide is the cheapest by overall average rate at $95 a month, but The Hartford and ERGO NEXT follow close behind at $96:
- Nationwide: $95 a month
- ERGO NEXT: $96 a month
- The Hartford: $96 a month
- Coverdash: $112 a month
- biBerk: $112 a month
Maryland requires workers' comp insurance for all employers with at least one employee. The Maryland Workers' Compensation Commission administers the program. Employers who fail to carry required coverage face penalties including fines and potential legal liability.
Maryland's state average workers' comp cost is $119 per employee monthly, well above the $74 national benchmark. Beauty, Body & Wellness Services ($16 a month) and Financial Services ($16 a month) are the most affordable industries in the state, while Transportation & Logistics ($364 a month) and Construction ($333 a month) are the most expensive.
Maryland employers get workers' compensation insurance through private carriers in a competitive market. Chesapeake Employers' Insurance Company (formerly The Injured Workers' Insurance Fund (IWIF)) operates as a competitive state fund alongside private carriers. Employers who can't obtain voluntary or from the Chesapeake Employers' Insurance Company may access the NCCI-administered assigned risk pool.
Workers' comp insurance in Maryland cover the following:
- Medical expenses: Covers all reasonable and necessary medical treatment; the Maryland Workers' Compensation Commission administers the fee schedule.
- Wage loss benefits: Pays temporary total disability at 66⅔% of the employee's average weekly wage (verify 2026 maximum against the Maryland Workers' Compensation Commission).
- Vocational rehabilitation: Provides retraining and employment support for workers who cannot return to their pre-injury occupation.
- Death benefits: Pays burial expenses and compensation to qualifying dependents based on the deceased worker's wage.
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com