
Best Professional Liability Insurance (E&O) Companies in Alabama

Our analysis of Alabama professional liability insurers found three providers that stood out on affordability, customer experience and coverage breadth.

  1. ERGO NEXT: Acquired by Munich Re's ERGO Group in 2025, it combines digital-first buying with serious financial backing. The entire purchase takes about 10 minutes online, certificates of insurance are available on demand and you can manage your policy around the clock via web or mobile app. It ranks first across 15 of 18 industries in Alabama, with no profession categories in the bottom three, making it the most consistently strong pick for Alabama small businesses.
  2. The Hartford: Its second-place finish is driven by coverage depth in specific industries. It ranks first in Alabama for Hospitality, Travel and Tourism and places second for Arts, Media and Entertainment, Education and Real Estate. Over 200 years in business and more than a million small businesses insured means its claims support infrastructure is battle-tested. Alabama businesses in Healthcare and Medical or Other Professional Services should look elsewhere, as The Hartford ranks ninth in both categories locally.
  3. Hiscox: Built entirely around business insurance, Hiscox writes coverage across 180-plus professions and ranks first in Alabama for Tech/IT and Nonprofits. Financial services firms, consultants and childcare operators also land in its top two spots in Alabama. It suits businesses that need real industry-specific policy depth rather than a generic small-business policy.

These three represent the strongest fit for most Alabama businesses, but no ranked list captures every situation. Comparing business insurance options side-by-side and getting direct quotes gives you the clearest picture.
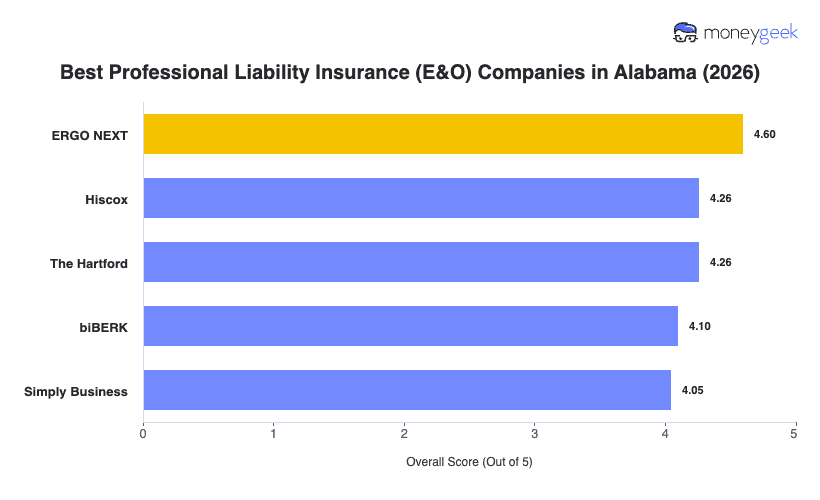
ERGO NEXT4.60$3711
Hiscox4.26$4547
The Hartford4.26$4634
biBERK4.10$5179
Simply Business4.05$5192

How to Get the Best Professional Liability Insurance in Alabama

Buying professional liability coverage in Alabama isn't a one-time decision. Your profession, your clients and where you operate all shape the answer. These steps walk you through getting professional liability coverage that fits your business rather than one that just checks a box.

  1. 1

    Check your AL licensing board requirements first

    Start by learning whether your profession has a mandatory coverage floor. Licensed massage therapists need at least $1 million in coverage before the state issues a license, and design professionals who go without a policy have to give clients a written, notarized disclosure first. Physicians face no licensure mandate, but Blue Cross and Blue Shield of Alabama won't enroll a provider in its network without at least $1 million per claim. The Alabama Department of Insurance keeps the official directory of licensed insurers.

  2. 2

    Assess your coverage needs based on your work and clients

    The value of your contracts and the cost of a realistic worst-case claim set your limit, not whatever quote comes in lowest. Lower-risk service businesses often sit fine at $250,000 to $500,000 per occurrence, while health care providers, engineers, architects and anyone bound by a $1 million contract minimum need to carry more. MoneyGeek's guide on how much professional liability insurance you need breaks the tiers down by profession.

  3. 3

    Work with a local agent who knows the AL market

    Alabama's market varies by region, so a local agent is worth the time. Huntsville's defense and aerospace work carries government contract requirements you won't see elsewhere, Birmingham handles most of the financial, legal and health care volume with its own credentialing and disclosure rules, and Mobile's maritime economy brings its own exposures. Look for someone with direct experience in your specific profession, not just your broad industry.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Premium is only one number on the quote. When comparing quotes, look at whether defense costs come out of your limits or sit outside them, what your retroactive date covers, and what the policy excludes.

  5. 5

    Research providers beyond price

    Before you bind, confirm the carrier is licensed to write professional liability in Alabama and check its claims-handling record, which tells you more than any marketing does. You can pull complaint data through the Alabama Department of Insurance to compare insurers.

  6. 6

    Consider bundling with other business coverage

    Pairing professional liability with general liability or a business owner's policy usually trims total premium by 10% to 15%, and most Alabama businesses need both anyway. It also makes it easier to produce a single certificate of insurance when a client asks for proof.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Alabama policies are almost always claims-made, so a claim has to be filed and reported while the policy is active. Let it lapse or switch carriers and work you did while covered can suddenly fall through the cracks, which is why professionals lean on tail coverage to protect past work. If you're changing insurers, ask about prior acts coverage, which pushes your new policy's retroactive date back to match your old one and closes the gap.

Best Alabama Professional Liability Insurance (E&O): Bottom Line

The right professional liability coverage in Alabama comes down to your industry, the value of your client contracts and how your work is structured. ERGO NEXT earns the top spot in MoneyGeek's analysis, but a health care provider who needs Blue Cross and Blue Shield of Alabama network credentialing, or an engineer working under Alabama's design professional disclosure law, may find a different carrier fits better. Start by confirming your licensing board requirements, then get quotes from at least three carriers and compare what each policy actually covers, not just what it costs.

Best Professional Liability Insurance Alabama Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

Beyond professional liability, most Alabama businesses need a few other policies to cover risks an E&O policy doesn't touch. Start with a look at the best AL small business insurance options, then round out coverage from there.

Professional Liability Insurance AL: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources