
Best Professional Liability Insurance (E&O) Companies in Texas

Our analysis of Texas professional liability insurers identified three providers that consistently outperformed the field on rates, coverage quality and customer experience.

  1. ERGO NEXT: A fully digital buying experience, quotes that bind in about 10 minutes and 24/7 certificate of insurance access through its app put ERGO NEXT at the top for most Texas small businesses. It ranks first in 15 of 18 Texas industries in our study. Texas contractors and hospitality operators should note that ERGO NEXT excludes construction-related operations and higher-risk hospitality work from professional negligence coverage.
  2. The Hartford: Claims handling depth and specialist support drive its Texas rankings, where it takes the top spot for real estate and hospitality and travel businesses and ranks second for marketing, communications and education firms. Texas healthcare providers and other professional services businesses will find it ranks ninth in those industries, making it a weaker fit there.
  3. Hiscox: Its professional liability policies cover work performed anywhere in the world, with claims filed in the U.S. or Canada, which suits Texas businesses with out-of-state clients. Hiscox ranks first for childcare and second across consulting, financial services, tech/IT and nonprofits.

These three providers represent the best fit for most Texas businesses, but no ranked list accounts for every situation. Comparing business insurance options side-by-side and getting direct quotes gives you the clearest picture.
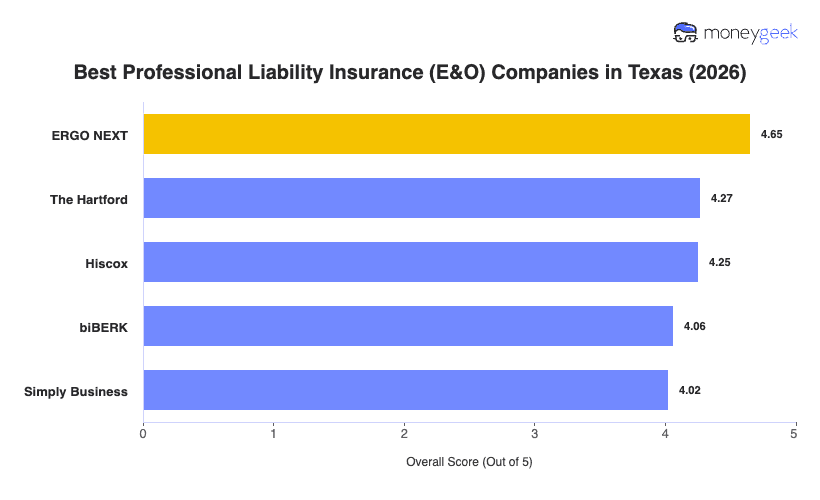
ERGO NEXT4.6511$40
The Hartford4.2734$49
Hiscox4.2547$48
biBERK4.0689$55
Simply Business4.0292$55

How to Get the Best Professional Liability Insurance in Texas

Getting professional liability coverage in Texas depends on your industry, your clients and the region of the state where you operate.

  1. 1

    Check your TX licensing board requirements first

    Confirm whether your profession carries a mandatory coverage requirement before you buy. Texas real estate inspectors must file a certificate of insurance with the Texas Real Estate Commission, and the Texas Department of Insurance requires licensed agents to carry at least $500,000 per claim in E&O.

  2. 2

    Assess your coverage needs based on your work and clients

    Your needs depend on who your clients are, how large your contracts are and how much a negligence claim could realistically cost you. Enterprise clients in Austin and Dallas-Fort Worth routinely require $1 million per occurrence minimums in their master service agreements. Use those factors to gauge how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the TX market

    Coverage needs vary across the state. Austin's tech sector drives contract-heavy E&O requirements, Dallas-Fort Worth's financial and corporate market calls for higher limits, and Houston's energy corridor and Medical Center create specialized demands. Choose an agent with direct experience in your industry and your region.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Rate is only one factor. Compare exclusions, deductibles and whether defense costs sit inside or outside the policy limit, since inside-the-limit terms cut into what is left for settlements. Comparing quotes from three or more carriers is the only way to see these differences.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Verify that any carrier you consider is licensed to write professional liability in Texas through the Texas Department of Insurance directory, and check its AM Best rating for financial strength. Texas associations like the Texas Society of CPAs, the State Bar of Texas and the Texas Medical Association also maintain member coverage resources worth reviewing.

  6. 6

    Consider bundling with other business coverage

    Bundling professional liability with general liability or a business owner's policy often trims combined premiums by 10% to 15%. ERGO NEXT, The Hartford and Hiscox all offer multi-policy discounts for Texas businesses.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Texas professional liability policies are almost always claims-made, so a claim must be filed while your policy is active for coverage to apply, and a lapse leaves prior work unprotected. If you switch carriers or retire, buy tail coverage to extend your reporting window and confirm the new carrier honors your existing retroactive date.

Best Texas Professional Liability Insurance (E&O): Bottom Line

The right professional liability coverage in Texas comes down to your industry, your client contracts and your budget. ERGO NEXT earns the top overall rating in our analysis, but a cleaning business in San Antonio and a financial advisor in Dallas have very different needs, so the best provider for one won't always be the best for the other. Assess your exposure, confirm any licensing requirements for your profession and compare quotes from at least three carriers before you commit.

Best Professional Liability Insurance Texas Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best TX small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance TX: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources