
Best Professional Liability Insurance (E&O) Companies in Mississippi

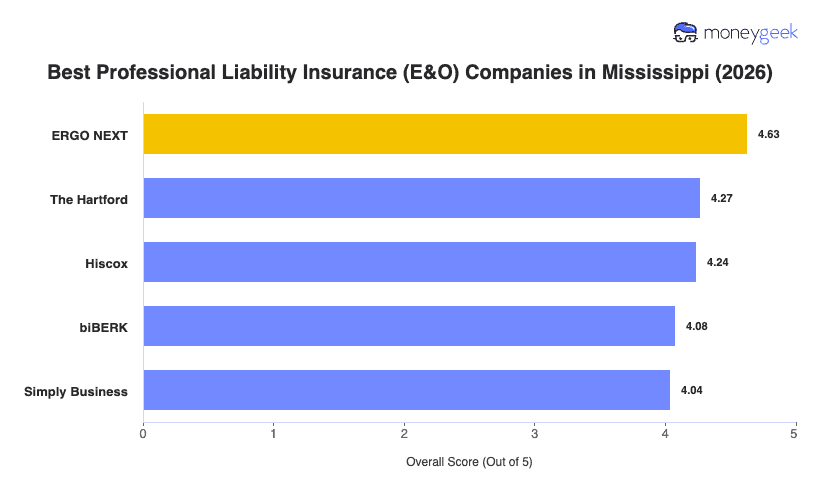
Our analysis of Mississippi professional liability insurers found three providers that consistently outperformed the rest on rates, coverage quality and service.

  1. ERGO NEXT: Topping our rankings with an overall score of 4.63 out of 5, it earned the top position in affordability, customer experience and coverage simultaneously, an unusual sweep across all three dimensions. ERGO NEXT is a digital-first insurer that issues policies for many professions near-instantly, which matters for Mississippi businesses that need proof of coverage quickly for client contracts. It ranks as the lowest-cost option in 15 of 18 industries in Mississippi, with particularly strong savings for consultants, financial services firms, cleaning operations and childcare providers.
  2. The Hartford: A strong second overall at 4.27 out of 5, The Hartford has more than 200 years in the industry and carries an AM Best A+ (Superior) financial strength rating. Its breadth across professional categories makes it a reliable choice for small to mid-size Mississippi businesses that want to consolidate coverage with a single well-established carrier. Tech and IT professionals and arts and media businesses in Mississippi will find The Hartford's rates especially competitive. That said, healthcare professionals and other professional services firms will find the insurer less price-competitive in Mississippi, where it ranks 9th on affordability in both of those categories.
  3. Hiscox: Third overall at 4.24 out of 5, Hiscox is the top-ranked provider in Mississippi specifically for Tech/IT, scoring 4.51 out of 5 in that industry. It's built a reputation as the go-to E&O carrier for solo practitioners and firms under 10 employees, with clear digital quoting and coverage across virtually every profession that needs professional liability in Mississippi. Hiscox carries an AM Best A (Excellent) financial strength rating.

These three providers cover the widest range of Mississippi businesses well, but no ranked list accounts for every situation your business brings to the table. Comparing business insurance options side by side and pulling quotes directly from multiple carriers gives you the clearest picture of what you'd actually pay.

ERGO NEXT4.6311$38
The Hartford4.2734$49
Hiscox4.2447$48
biBERK4.0879$54
Simply Business4.0492$54

How to Get the Best Professional Liability Insurance in Mississippi

The right approach to getting professional liability coverage in Mississippi depends on your industry, your clients and where in the state you operate.

  1. 1

    Check your MS licensing board requirements first

    Find out whether your profession has a mandatory coverage floor before you shop. The Mississippi Real Estate Commission requires E&O for all active licensees with a minimum $100,000 per-claim limit. Physicians face no statutory malpractice mandate, but hospitals and credentialing bodies effectively require it, and design-build contractors carry professional liability exposure even though the contractor board only mandates general liability.

  2. 2

    Assess your coverage needs based on your work and clients

    Match your tier to who your clients are and what a claim against your work could cost. Lower-stakes service businesses often sit at $250,000 to $500,000, while consultants, real estate agents and nonprofits commonly need $500,000 to $1 million. Tech, healthcare, financial services and childcare operators typically need $1 million to $2 million. Use these as a starting point for how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the MS market

    Mississippi's risk profile shifts by region. Jackson's government contractors, healthcare and financial firms often need higher limits, the Biloxi-Gulfport corridor brings gaming, hospitality and maritime exposure, and Hattiesburg's healthcare and education sectors have their own norms. Look for agents who have placed coverage specifically in your industry.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Rate is only one part of what you're buying. Two policies at the same premium can differ on whether defense costs sit inside or outside the limit, whether there's a consent-to-settle or hammer clause, and how broadly the policy defines your covered services. Read the professional services definition carefully and update it whenever your scope of work changes.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Confirm any carrier is licensed in Mississippi through the Mississippi Insurance Department before binding. AM Best financial strength ratings tell you whether a carrier can pay claims years out, which matters for a long-tail claims-made policy. State associations like the Mississippi Bar, Mississippi Medical Association and Mississippi Association of Realtors often maintain sponsored E&O programs worth checking.

  6. 6

    Consider bundling with other business coverage

    Combining professional liability with general liability or a business owner's policy typically cuts total premiums by 10% to 15% versus buying separately. Most Mississippi businesses need both anyway, since one covers your service errors and the other covers third-party injury and property damage.

  7. 7

    Do not let your coverage lapse, and understand tail coverage

    Mississippi professional liability policies are almost always claims-made, so the policy in force when the claim is filed responds, not the one in force when the error happened. Lapsing or switching carriers without tail coverage leaves past work unprotected. If you're retiring, selling or switching insurers, buy tail coverage or confirm your new carrier honors your prior retroactive date before the old policy expires.

Best Mississippi Professional Liability Insurance (E&O): Bottom Line

Choosing the right professional liability coverage in Mississippi comes down to your industry, what your client contracts require and whether you need a carrier that moves fast or one with deep coverage breadth. ERGO NEXT earns our top rating at 4.63 out of 5, but that score reflects averages across 18 industries, and your own profession should drive the final call. Confirm any licensing board requirements that apply to your work, then compare at least three quotes with attention to how each policy defines your covered services and whether defense costs erode your limit or sit outside it.

Best Professional Liability Insurance Mississippi Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best MS small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance MS: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources