
Best Professional Liability Insurance (E&O) Companies in Colorado

Our analysis of Colorado professional liability insurers found three providers that consistently outperformed the rest of the field on rates, coverage quality and customer experience.

  1. ERGO NEXT: It earns the top spot by pairing the state's lowest rates with a genuinely fast buying experience. Denver consultants and Boulder tech startups can get quoted, buy a policy and pull a certificate of insurance in about 10 minutes through the app or website, with 24/7 policy management after that. Businesses in consulting, finance, education and tech score better with competing providers, so those industries should weigh their options before committing.
  2. The Hartford: For Colorado businesses that expect to actually use their coverage, claims handling matters more than shaving a few dollars off the monthly rate, and this is where The Hartford earns its spot. Backed by more than 200 years in the industry, it ranks first or second in Colorado for Hospitality, Travel and Tourism, Marketing and Communications, and Education. Health care professionals and other professional services businesses should look elsewhere. The Hartford underperforms in both categories in this state.
  3. Hiscox: Coverage breadth is what sets Hiscox apart. It writes professional liability across more than 180 industries and ranks second in Colorado for Financial Services, Consulting, Tech/IT and Childcare. Businesses in Arts, Media and Entertainment or Recreation and Sports will find better fits elsewhere on this list.

These three providers cover the needs of most Colorado businesses well, but no ranking captures every variable your business brings to the table. Comparing business insurance options side by side and getting direct quotes gives you the clearest picture of what you'll actually pay and what you'll actually get.
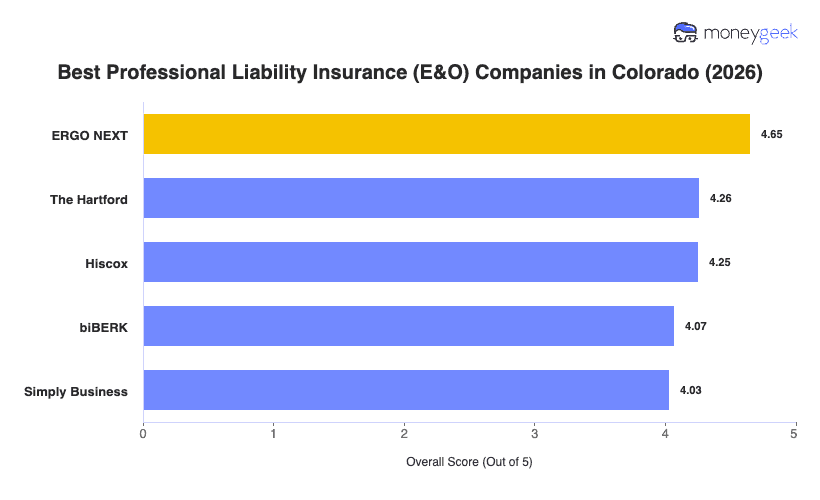
ERGO NEXT4.5411$39
The Hartford4.3234$42
Hiscox4.2547$43
biBERK4.1179$46
Simply Business4.0792$47

How to Get the Best Professional Liability Insurance in Colorado

Your industry, the clients you work with, where in the state you operate and what your contracts require all shape what getting professional liability coverage costs you. These steps walk you through the process from start to finish.

  1. 1

    Check your CO licensing board requirements first

    Some Colorado professions have a mandatory coverage floor before you can legally practice. Licensed physicians must carry $1 million per occurrence and $3 million aggregate through the Colorado Medical Board. Real estate brokers, appraisers and mortgage loan originators must maintain E&O of at least $100,000 per claim and $300,000 aggregate through the Division of Real Estate, with automatic license inactivation if coverage lapses.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on who your clients are, what contracts you sign and how much a claim could realistically cost. Lower-exposure businesses like cleaning services, photographers and marketing agencies often sit at $250,000 to $500,000, while physicians, architects and childcare operators may need $1 million to $2 million. Use these tiers as a starting point for how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the CO market

    Colorado's business environment varies enough by region that a generalist won't cut it. Denver's financial services, tech and health care concentration creates very different coverage conversations than construction-heavy Colorado Springs and Pueblo, or the tourism-driven hospitality businesses in Aspen, Vail and Breckenridge. Find an agent with direct experience in your industry and region.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Price is the easiest thing to compare and often the least important. When comparing quotes, check whether defense costs are paid inside or outside the policy limit, since a $1 million policy that burns through defense first is materially weaker than one where defense is separate. Confirm the retroactive date, deductible and exclusions on every quote, and know that clients may request a certificate of insurance before work starts. 

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Verify any carrier through the Colorado Division of Insurance to confirm it holds an active certificate of authority in the state. The Colorado Medical Society, the Colorado Bar Association and the Colorado Association of Realtors all publish carrier resources and sometimes offer sponsored E&O programs worth comparing against the open market.

  6. 6

    Consider bundling with other business coverage

    Pairing your professional liability with general liability or a business owner's policy often trims your total premium by 10% to 15%. ERGO NEXT, The Hartford and Hiscox all offer bundling across their Colorado professional liability and general liability products.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Colorado professional liability policies are almost universally claims-made, so the policy active when a claim is filed pays, not the one active when the work was done. If coverage lapses for even a day, you lose protection for everything done up to that point. When you retire, close a business or switch carriers, buy tail coverage to stay protected for past work. It runs 100% to 200% of your final year's premium, and with Denver and the Front Range generating the state's highest litigation volume, a gap isn't a theoretical risk.

Best Colorado Professional Liability Insurance (E&O): Bottom Line

Choosing professional liability coverage in Colorado starts with your industry, your client contracts and your budget, not with picking a name. ERGO NEXT earns the top overall rating, but a physician in Denver, a design-build contractor in Colorado Springs and a financial advisor in Boulder all need different limits and different carriers. Pull quotes from at least three providers, compare what each policy actually covers, and check that your limits reflect Colorado's 2025 damage cap increases if you're in health care.

Best Professional Liability Insurance Colorado Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best CO small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance (E&O) CO: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources