
Best Professional Liability Insurance (E&O) Companies in Oregon

Our analysis of Oregon professional liability insurers found three providers that consistently outperformed the field across affordability, customer experience and coverage quality.

  1. ERGO NEXT: Rates and a fully digital buying experience that takes about 10 minutes from start to certificate of insurance put ERGO NEXT at the top of the Oregon rankings. The insurer ranks first across 14 of 18 industries in Oregon, with its strongest scores in health care, fitness, pet care, childcare and arts and media. Consulting, education and financial services businesses will find better rates and coverage fit elsewhere, as ERGO NEXT's pricing in those industries runs above the Oregon average.
  2. The Hartford: A 200-year track record and fast claims processing set The Hartford apart from most competitors in the Oregon market, particularly for consulting and financial services professionals, where it ranks first in the state. The insurer lets businesses start with a core policy and layer on additional coverage as they grow, which suits Oregon's large population of small professional firms in Portland and Eugene.
  3. Hiscox: Tailored policies across more than 180 industries give Hiscox an unusually broad reach for a small business insurer, and it ranks first in Oregon for education providers and nonprofits. The insurer's online buying process is available around the clock, and its policies can cover up to five office locations under a single plan, which works well for Oregon businesses operating across multiple markets.

Ranked providers represent the best fit for most Oregon businesses, but no single list captures every consideration. Comparing business insurance options side by side and getting direct quotes gives you the clearest picture before you commit.
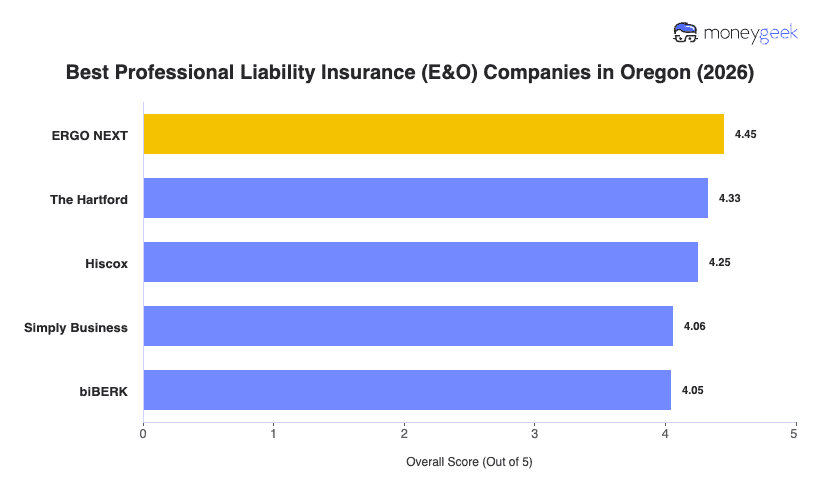
ERGO NEXT4.4511$48
The Hartford4.3334$43
Hiscox4.2547$44
Simply Business4.0692$50
biBERK4.0579$52

How to Get the Best Professional Liability Insurance in Oregon

The path to getting professional liability coverage that actually fits your Oregon business runs through a few concrete steps.

  1. 1

    Check your OR licensing board requirements first

    Confirm whether your profession has a mandatory coverage floor set by an Oregon licensing body. Private practice attorneys must carry $300,000 aggregate through the Oregon State Bar Professional Liability Fund, investment advisers and broker-dealers must file proof of at least $1 million in E&O, and insurance agents need at least $500,000 per occurrence.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on who your clients are, what your contracts require and how much a single claim could realistically cost. Lower-risk consultants, photographers and cleaning businesses typically sit at $250,000 to $500,000 per occurrence, while physicians, architects and childcare operators land at $1 million to $2 million. Use these tiers as a starting point for how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the OR market

    Oregon's business environment varies enough by region that a generalist agent will miss things. Portland and Hillsboro have dense tech and financial services sectors that demand high limits and specific endorsements, while Bend's construction and recreation industries carry different risk profiles. Seek out an agent with direct experience in your specific industry.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Rate comparisons only help when the coverage is equivalent. Check the retroactive date on each claims-made quote, confirm whether defense costs sit inside or outside your limits, and look closely at exclusions. A low rate on a policy that excludes your primary risk is worse than paying more for coverage that responds.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    A carrier's willingness to pay claims matters as much as its premium. Verify that any insurer is licensed to write professional liability in Oregon through the Oregon Division of Financial Regulation's license lookup. Industry groups like the Oregon State Bar and the Technology Association of Oregon publish carrier track records worth consulting first.

  6. 6

    Consider bundling with other business coverage

    Buying professional liability with general liability or inside a business owner's policy often cuts your combined premium by 10% to 15% versus separate policies. Oregon tech and healthcare firms that also need cyber liability can frequently bundle it under one carrier for less.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Oregon professional liability policies are almost always claims-made, meaning coverage responds when a claim is filed, not when the error occurred. If your policy lapses or you switch carriers without tail coverage, past work is no longer protected against later claims. If you're retiring, selling or changing insurers, buy the endorsement or confirm prior acts coverage first.

Best Oregon Professional Liability Insurance (E&O): Bottom Line

The right professional liability coverage in Oregon comes down to your industry, the minimum limits your licensing board or clients require, and how much of the state's litigation exposure applies to your type of work. ERGO NEXT earns the top overall rating, but The Hartford is worth a close look for consulting and financial services firms, and Hiscox is the stronger fit for education businesses and nonprofits. Get quotes from at least three carriers, compare policy terms alongside rates, and confirm the insurer is licensed in Oregon before you commit.

Best Professional Liability Insurance Oregon Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best OR small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance OR: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources