Best Professional Liability Insurance (E&O) Companies in Wyoming

Our analysis of Wyoming professional liability insurers found three providers that consistently outperformed the field on rates, customer experience and coverage quality.

  1. ERGO NEXT: Topping the list on both affordability and customer experience, this digital-first insurer ranks first in 15 of 18 industries for Wyoming businesses. The buying process is fast and straightforward, with quotes and coverage binding available in minutes, which matters when a client contract hits your desk, and you need proof of insurance that same day. ERGO NEXT works well for construction and contracting, cleaning services, health care, fitness, pet care, real estate and tech businesses in Wyoming. No Wyoming industry ranks it below third.
  2. The Hartford: A+ rated and active across multiple professional categories, The Hartford earns its spot on the strength of its industry-specific coverage options and claims support infrastructure. It ranks first or second in Wyoming for consulting services, financial services, education, hospitality and marketing. It scores lower for health care providers and other professional services, where its affordability rating drops, so medical and specialty professionals should compare it carefully against other options.
  3. Hiscox: Built for small firms and solo practitioners, Hiscox brings a clean buying experience and strong coverage across most industries. It ranks first in Wyoming for hospitality, travel and tourism, and scores well for tech, nonprofits, childcare, beauty and wellness, and pet care. That profile fits Wyoming's business environment well, where independent operators and small professional firms make up the majority of the market.

Ranked providers represent the best fit for most Wyoming businesses, but no list captures every situation. Comparing business insurance options side by side and getting quotes directly from multiple carriers gives you the clearest picture of what you'll pay.
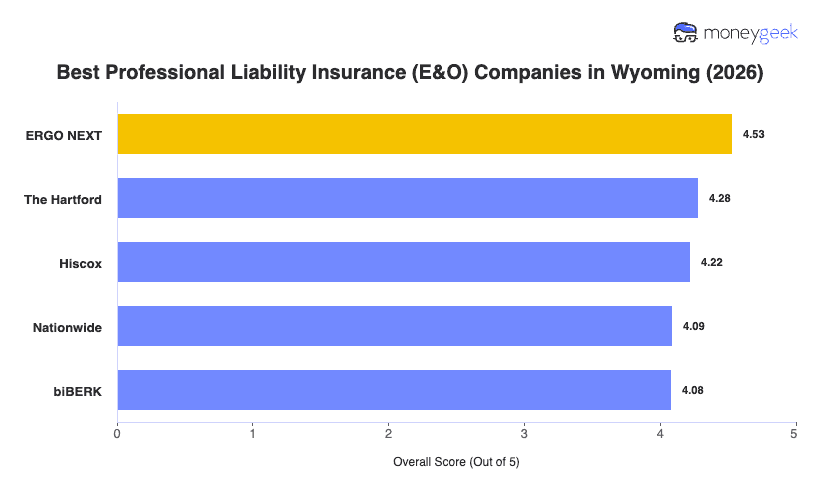
ERGO NEXT4.5311$44
The Hartford4.2834$42
Hiscox4.2247$45
Nationwide4.0955$47
biBERK4.0879$50

How to Get the Best Professional Liability Insurance in Wyoming

Start with a clear picture of your risk, your contracts and your state's rules before getting professional liability coverage in Wyoming.

  1. 1

    Check your WY licensing board requirements first

    Find out whether your profession has a mandatory coverage floor. Wyoming physicians must carry at least $50,000 per claim for the state's patient compensation fund, and real estate agents and brokers must hold E&O coverage of $100,000 per occurrence and $500,000 aggregate to activate a license.

  2. 2

    Assess your coverage needs based on your work and clients

    Match your limits to your client type, contract value and realistic claim cost when deciding how much professional liability insurance you need. Small-contract businesses often sit at $250,000 to $500,000 per occurrence, while physicians, engineers and public-project contractors are typically pushed into the $1 million to $2 million range.

  3. 3

    Work with a local agent who knows the WY market

    Wyoming's economy shifts by region, from government contractors in Cheyenne to energy firms in Casper to high-end tourism and wealth management in Jackson Hole. Look for an agent with direct experience in your industry and geography, not just general commercial lines.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Don't stop at the premium, since two similarly priced policies can behave very differently at claim time. Check whether defense costs sit inside or outside your limits, and confirm the retroactive date on any claims-made policy reaches back far enough to cover your prior work.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Verify any carrier is admitted in Wyoming through the Wyoming Department of Insurance, since a non-admitted insurer doesn't offer the same regulatory protections. Weigh claims-handling track record and profession-specific experience, and check endorsed programs through groups like the Wyoming State Bar or Wyoming Medical Society.

  6. 6

    Consider bundling with other business coverage

    Pairing professional liability with general liability or a business owner policy often trims your total premium by 10% to 15%. Most Wyoming small businesses need both anyway, so ask each carrier whether bundling earns a discount.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Wyoming professional liability policies are almost always claims-made, so a lapse wipes out coverage for all past work the moment it expires. When you retire, close up or switch insurers, buy tail coverage to extend your reporting window, which matters most in the state's more active legal and medical markets.

Best Wyoming Professional Liability Insurance (E&O): Bottom Line

The right professional liability policy in Wyoming depends on your industry, the size of your client contracts and your exposure to litigation. ERGO NEXT earns the top overall rating statewide, but it isn't automatically the right fit for everyone, since healthcare providers must meet the state's minimum malpractice requirements, real estate professionals have to satisfy Wyoming Real Estate Commission mandates, and Casper's energy sector often works under contracts that dictate specific limits and prior-acts coverage. Get quotes from at least three carriers, confirm each is licensed in Wyoming, and match your limits to what your clients and licensing boards actually require.

Best Professional Liability Insurance Wyoming Chart

Professional Liability Insurance WY: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources