


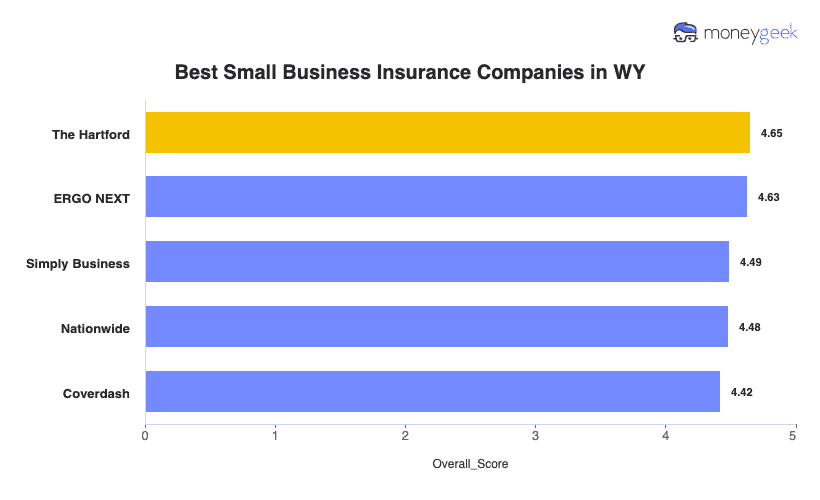
The Hartford has the highest overall score in my analysis and is also the least expensive insurer in the table at $82 per month. That combination makes it my pick for the best business insurance provider in Wyoming. ERGO NEXT costs $20 more but ranks first for customer service, so it may suit you better if fast online servicing matters. Another strong option is Simply Business, which is a good match if you want to compare quotes from multiple carriers before deciding.
Best Small Business Insurance in Wyoming
In my analysis, Wyoming's best business insurance providers in 2026 are The Hartford, ERGO NEXT and Simply Business.
The work you do, how many people you employ, the risks you need to manage and your budget help determine the right provider for your business.
MoneyGeek can help you get Wyoming business insurance quotes from your top insurer match with our tool below.
Select state
Updated: September 8, 2026
Advertising & Editorial Disclosure
Best Small Business Insurance Companies in Wyoming
| The Hartford | 4.65 | $82 | 2 | 3 |
| ERGO NEXT | 4.63 | $102 | 1 | 2 |
| Simply Business | 4.49 | $98 | 5 | 1 |
| Nationwide | 4.48 | $100 | 2 | 4 |
| Coverdash | 4.42 | $102 | 6 | 2 |
| biBERK | 4.39 | $106 | 2 | 5 |
| Progressive Commercial | 4.33 | $100 | 7 | 5 |
| Thimble | 4.31 | $95 | 8 | 5 |
| Hiscox | 4.28 | $111 | 4 | 6 |
| Chubb | 4.27 | $119 | 3 | 4 |
Note: Wyoming insurance averages can help you compare costs, but they aren’t meant to mirror one “typical” business. MoneyGeek’s methodology uses the same two-employee profile across 79 major industries so the numbers stay consistent. Your own premium will depend on the details of your operation and the coverage you buy.

The Hartford
Best and Cheapest Wyoming Business Insurance
MoneyGeek Rating
4.7/ 5
4.7/5Affordability
4.6/5Customer Experience
4.7/5Coverage Options
Average Monthly Cost of General Liability Insurance
$75This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
N/AThis rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Survey: Claims Process
4.5/5 (1st)Our Survey: Agent Service
4.7/5 (1st)

ERGO NEXT
Best Wyoming Customer Experience
MoneyGeek Rating
4.6/ 5
4.5/5Affordability
4.7/5Customer Experience
4.8/5Coverage Options
Average Monthly Cost of General Liability Insurance
$95This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
N/AThis rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Survey: Digital Experience
4.8/5 (1st)Our Survey: Likely to Be Recommended to Others
4.8/5 (1st)

Simply Business
Best Commercial Coverage Options in Wyoming
MoneyGeek Rating
4.5/ 5
4.5/5Affordability
4.2/5Customer Experience
4.9/5Coverage Options
Average Monthly Cost of General Liability Insurance
$89This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
N/AThis rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Survey: Digital Experience
4.5/5Our Survey: Service Quality
4.0/5
How to Get the Best Cheap Business Insurance in Wyoming
Getting business insurance in Wyoming requires balancing affordable rates against protection from winter storms and 8.7 million annual tourists creating liability exposure. These six steps secure cost-effective coverage from reliable providers.
- 1
Assess what coverage your Wyoming business actually needs
Wyoming weather can change what deserves attention first. If wind, heavy snow or a multi-day closure could damage your building or interrupt operations, make sure your property coverage can handle that exposure. Then check the rules tied to your business. Workers’ comp for covered extra-hazardous industries runs through Wyoming’s state system, while business vehicles need the state-required auto liability coverage.
Read More: How Much Business Insurance Do I Need?
- 2
Get quotes from affordable providers with strong customer ratings
Once you have a shortlist, compare business insurance quotes using the same limits and deductible. Then look closely at what each insurer is actually willing to cover. A lower quote may reflect a restrictive exclusion, a different business classification or fewer optional endorsements. I’d also check how quickly each provider can issue documents or make policy changes, especially if contracts or seasonal work create tight deadlines.
- 3
Check insurer reliability before choosing based on price
For Wyoming, I’d test an insurer against a bad-weather scenario before committing. Ask what happens if wind or snow damages your property and you can’t reopen for several days. How do you report the loss, and how quickly can someone approve repairs or other next steps? That answer can matter more than a modest premium difference when your revenue stops until the business is operating again.
- 4
Cut insurance costs without reducing your protection
Start with the way you pay and structure coverage rather than cutting limits. Bundling liability and property may reduce the total, while paying annually can avoid installment charges. A higher deductible can also lower the premium if you have enough cash set aside for a smaller loss. Wyoming businesses with employees should ask whether qualifying safety programs can reduce workers’ comp costs. Review your full-year business insurance costs before deciding which option actually saves money.
- 5
Secure coverage that meets contract or lease requirements
If a Jackson Hole property owner or a contractor asks for proof of insurance, the details of the agreement should drive what you buy. Check the required liability limits and whether you need an additional insured endorsement before work starts. Then confirm how quickly your insurer can issue a certificate of insurance (COI). A cheaper policy offers little advantage if missing paperwork delays the job.
- 6
Update your policy when business operations change
Treat certain business changes as automatic insurance check-ins. Hiring can affect your workers’ comp obligations, while buying a vehicle creates a new auto exposure. A larger contract may also require limits your current policy doesn’t carry. Wyoming’s state workers’ comp rates can change too, so review those costs separately when new rates take effect instead of assuming last year’s budget still applies.
Best Business Liability Insurance in Wyoming: Bottom Line
The Hartford protects your business for $20 less monthly than competitors while covering storm damage and customer injuries, though your best choice depends on whether you need the fastest claims payment or the broadest coverage. Compare three providers to find savings, get required workers' compensation through Wyoming's state fund and bundle your policies to pay less for small business insurance.

LOOKING FOR THE BEST INSURANCE FOR A SPECIFIC COVERAGE TYPE?
Different policies can point you toward different providers. Use these Wyoming guides to see which insurers we recommend for different coverage types.
Business Insurance in Wyoming: FAQ
Small business owners across Wyoming face numerous questions when selecting business insurance coverage. We've compiled answers to the most common concerns below:
Wyoming makes one part of the answer unusual because workers’ comp for covered extra-hazardous industries runs through the state system rather than the private market. For everything else, I’d work backward from what could create a costly claim. That may mean commercial auto for business vehicles, general liability coverage for customer or contract risks, or property insurance if your operation depends on buildings, equipment or inventory.
The cost of your Wyoming coverage depends on which policies you actually need. These averages give you a starting point:
- General liability: $106 per month or $1,269 per year
- Commercial auto: $140 per month per vehicle or $1,684 per year per vehicle
- Commercial property: $113 per month or $1,353 per year
- Professional liability: $52 per month or $627 per year
- Cyber insurance: $71 per month or $849 per year
Think about what would keep you from opening tomorrow. If damaged equipment or a building loss would stop the business, property protection needs to sit near the top of the list. If your bigger exposure comes from customers or work performed away from your premises, general liability coverage matters first. I’d add other policies only when the way you operate creates a clear reason for them.
Pay attention to the questions the insurer asks before quoting. A carrier that understands your industry should ask about the work you perform, where you perform it and any higher-risk activities that change your exposure. I’d also check the exclusions and business classification on the quote. If they don’t match what you actually do, ask the insurer to correct them before you buy.
About Connor Bolton

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.
The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.
Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.
Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.