

My analysis ranked these companies as the best small business insurers for coffee shops and cafés:
Best Coffee Shop Business Insurance
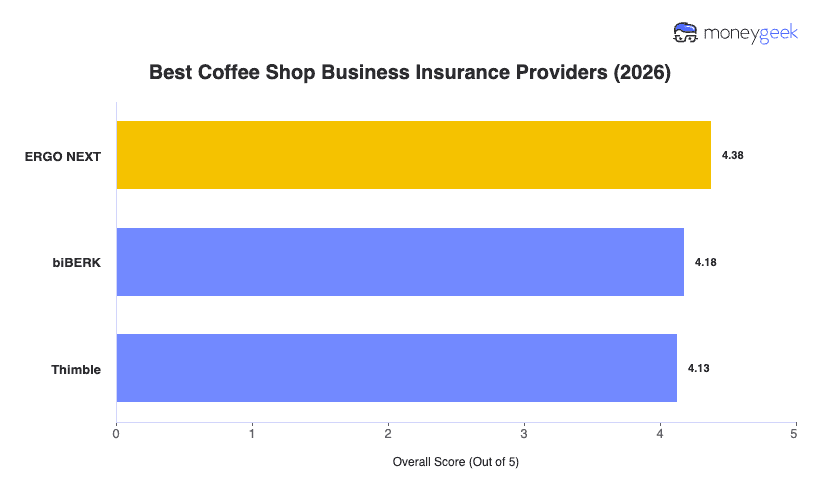
The best insurance for coffee shops and cafés is offered by ERGO NEXT and biBERK.
MoneyGeek helps you compare the best coffee shop insurers, coverage types and costs, so you can find the protection your operation needs.
Ready to shop? Use our tool below to get matched with your top provider and start your coffee shop insurance quote.
Select state
Safe & SecureVerified and VettedTrusted Brands
Updated: October 9, 2026
Advertising & Editorial Disclosure
Best Business Insurance Companies For Coffee Shop
I don't take ranking insurers for coffee shops lightly, because the risks a café carries look nothing like a typical retail store. Scalding beverages, pressurized equipment, wet floors behind a cramped bar and high employee turnover create a claims profile that punishes generic coverage. My rankings are built on three things: what you'll actually pay, what happens when you need help and whether the coverage holds up when it counts. I scored each provider across affordability (50%), customer experience (30%) and coverage options (20%), weighted that way because premium cost determines what a single-location café on thin margins can sustain month to month, but a cheap policy that fights you on a spoilage claim or takes three days to issue a COI is no bargain.
This is what made up my analysis of popular insurers, which was assisted (not run) by AI:
- Affordability: I pulled quotes isolating pricing factors across food and beverage sub-industries, all 50 states (plus DC), employee count (5 ranges from 0 to 49), 16 vehicle types (for commercial auto) and six of the most common coverage types, extrapolating 500,000+ estimates to build a full pricing picture for coffee shops and cafés specifically.
- Customer Experience: 300,000+ reviews, forum conversations and industry research were aggregated and manually parsed to identify the patterns that made customers enjoy and dislike service from each insurer. I also went through what an actual coffee shop owner would go through for all providers analyzed, testing their quoting experiences and policy management tools (excluding claims due to limitations).
- Coverage Options: I read the fine print of policy terms, isolated the exclusions and hidden costs that affect food service operations (like equipment breakdown carve-outs, liquor liability restrictions and spoilage sub-limits), and documented every option available for all providers to determine which has the best coverage for your café now and as your operation grows.

ERGO NEXT: Best Overall for Budget-Conscious Cafés
pros
Lowest average monthly cost for coffee shops
BOP includes food spoilage endorsement
Liquor liability available as GL add-on
cons
Complex claims take longer to resolve
Agent access limited to email chat
Solo operators pay above industry average
COMPANY HIGHLIGHTS
ERGO NEXT runs about 20% below what coffee shops pay on average for coverage, and that gap holds whether you are staffing a small counter team or managing a full café floor. Backed by Munich Re, its self-service platform lets you quote, bind and pull a COI entirely through the app without waiting on an agent. The BOP includes a food spoilage endorsement that pays when a power outage or compressor failure wipes out your refrigerated inventory, and liquor liability plugs into your GL policy as an add-on instead of requiring a separate purchase.
Where ERGO NEXT falls short is on claims handling for layered losses. A boiler failure that shuts the shop for a weekend and triggers both an equipment repair and a business income claim is the scenario where BBB complaints flag delays and denials most often. Post-merger support routes through an email chat system rather than a direct phone line, which adds friction when you need answers fast.
Read Our Review: ERGO NEXT Business Insurance Review

biBERK: Best for Agent-Guided and Growing Operations
pros
Licensed agents walk you through options
Single-policy bundling for expanding cafés
Berkshire Hathaway financial backing
cons
COI turnaround takes up to three days
No coffee-shop-specific policy framing
Claims stage ranks sixth in this study
COMPANY HIGHLIGHTS
I recommend biBERK for café owners who want someone explaining what their BOP actually covers before they sign. When you call during business hours, a licensed agent walks through your options, flags gaps you might miss buying alone and explains how product liability sits in relation to your GL policy if you sell a third-party baker's pastries at the counter. At around $94 a month it sits about 4% above the sub-industry average, but the value shows up when your operation grows. Liquor liability, EPLI, spoilage coverage and hired and non-owned auto all bundle under a single policy with one renewal date.
The friction surfaces around speed and specificity. Adding your landlord as an additional insured takes up to two business days, and a custom COI with the exact wording your lease requires can stretch to three. You also won't find espresso equipment or barista injury framing built into the policy options, so the coverage works but the language is generic food service rather than café-specific.
Read Our Review: biBerk Business Insurance Review

Thimble: Best for Flexible and Event-Based Café Coverage
pros
Monthly or project-based policies
A quote you can bind and a COI in under a minute
Second-place ranking for customer experience
cons
Last-place ranking for coverage options in this study
Less claims support after you file
Liquor liability is a separate add-on
COMPANY HIGHLIGHTS
Thimble earned its spot here because no other provider on this list lets you buy coffee shop coverage by the month, the job or the year with the same ease. At $88 a month it sits below the sub-industry average, and food businesses on the platform typically save 5% to 12% compared to the industry benchmark. I had a bindable GL quote in under a minute and a downloadable COI before finishing my coffee. That speed matters when you book a weekend pop-up or a catering gig and need proof of insurance the same day.
The tradeoff is coverage depth. Thimble ranks last among the seven providers I evaluated on coverage options, and that gap shows up once your operation outgrows a simple GL and property setup. Higher limits require an umbrella policy, and liquor liability has to be layered on separately rather than folded into your GL. Claims filing starts out simple enough, but assignment lags and communication drops off during the resolution process, especially on contested liability claims.
Read Our Review: Thimble Business Insurance Review
What Types of Insurance Do Coffee Shop Need?
Coffee shops carry a risk combination most retail businesses don't share. You hand scalding liquid to the public across a counter hundreds of times a day, your operation depends on pressurized equipment worth tens of thousands of dollars, and your staff works around steam, wet tile and repetitive motion on every shift. General liability and commercial property are non-negotiable before you open. Add even one barista and workers' compensation becomes legally required in most states. From there, coverage layers on with your operation. A delivery vehicle, a beer and wine license, a catering program or a loyalty app each introduce exposure your base policies were not built to handle.
The table below summarizes the most common types of business insurance that coffee shops need to meet lease requirements and cover the financial risks specific to food service.
Third-party bodily injury and property damage claims, including customer burns from hot beverages, slip-and-fall injuries on wet floors and damage to a customer's belongings at your counter | Your commercial lease will almost certainly require this before you open, and it stays required for the life of the lease | Average GL claim severity reached $101,000 in 2024, up 45% since 2020, and hot beverage burns and slip-and-fall incidents are the two most frequent claim triggers for coffee shops. | |
Damage or loss to your espresso equipment, commercial refrigeration, leasehold build-out and inventory from fire, theft, vandalism or water damage | If you lease or own a café space with business equipment your landlord's policy will not cover | Restaurants filing property claims face average losses around $9,000 per incident, with fire losses regularly exceeding $100,000, and your landlord's insurance covers the building structure, not your equipment or improvements inside it. | |
Employee medical bills, lost wages and rehabilitation after a work injury, including steam burns, slips behind the bar and repetitive strain from espresso tamping | Most states require this from the moment you hire your first barista, whether full-time or part-time | Coffee shops produce 45% more lost time injuries than any other restaurant type, and "Barista Wrist" from repetitive tamping averages 366 days of recovery. | |
Bundles general liability and commercial property into a single policy, often with endorsements for equipment breakdown and food spoilage included or available | Small cafés that need both GL and property coverage and want simplified billing with one renewal date | A BOP typically costs less than buying GL and property separately, and food service endorsements like spoilage coverage protect your refrigerated inventory when a compressor failure or power outage would otherwise be an uninsured loss. | |
Injuries and vehicle or property damage from work-related driving, including catering deliveries, supply runs and mobile coffee cart transport | If your café owns a vehicle or employees regularly use personal cars for business errands | Personal auto policies exclude accidents that happen during business use, so a barista picking up supplies in their own car who gets in a collision on the way back creates a claim their personal insurer will deny. | |
Liquor liability | Claims arising from alcohol-related injuries or property damage caused by a patron who was overserved at your shop | When your café holds a beer or wine license, since your GL policy will not cover alcohol-related incidents | Some states require proof of liquor liability coverage as a condition of holding the license, and a single overservice claim naming your shop can produce legal costs that GL alone will not touch. |
Costs from data breaches, ransomware and notification obligations when customer payment data or loyalty program records are compromised | If you process card payments, run a loyalty app or store customer data across POS terminals | A breach exposing payment card data triggers notification requirements, credit monitoring costs and potential regulatory penalties that your GL policy does not cover, and the risk scales with every terminal and loyalty account your shop adds. | |
Extra liability protection that kicks in after your primary GL, auto or workers' comp policy reaches its limit | When a lease, catering contract or vendor agreement requires limits above your base policies | A single large catering event claim or a serious burn injury lawsuit can exhaust a standard $1 million GL limit, and an umbrella extends coverage above that ceiling without requiring you to restructure your underlying policies. | |

WHY GETTING COFFEE SHOP INSURANCE IS IMPORTANT
Your café serves drinks hot enough to cause second-degree burns, uses equipment that can break without warning and has floors that can stay wet all day. General liability for a coffee shop averages $116 a month, or about $1,388 a year. A single slip-and-fall settlement in food service can cost $10,000 to $50,000. One claim like that can wipe out years of premiums and months of profit. If your espresso machine's boiler fails, the repair can cost $2,000 and close the shop for a weekend. That's when the gap between the cost of coverage and the cost of going without it becomes clear.
How Much Does Coffee Shop Business Insurance Cost?
Coffee shop business insurance costs average $96 a month, or $1,149 a year. Steady customer traffic, high-temperature equipment and commercial lease requirements all push those costs up. Commercial auto costs the most, at $162 a month, because of the risk from catering and delivery vehicles. General liability is next, at $116 a month, because every coffee shop has hot-beverage burn and slip-and-fall risk. What you pay depends on your headcount, whether you have a liquor license, how many locations you have and your claims history.
The costs for common coverage types are below:
- General Liability: $116 monthly ($1,388 annually)
- Commercial Auto: $162 monthly ($1,942 annually)
- Cyber Insurance: $103 monthly ($1,231 annually)
- Commercial Property: $65 monthly ($774 annually)
- Workers' Comp: $34 monthly ($411 annually)
What Are These Costs Based On?
The costs presented are for a 1 to 4-person business aggregated across all 50 states plus D.C. Assumptions by coverage type are as follows.
- Coverage limits for workers' comp and commercial auto represent state-required coverage.
- General liability is for a $1 million per occurrence and $2 million aggregate policy.
- Commercial property assumes an average estimated property value across all professions.
- Cyber insurance assumes a $1 million limit policy.
Our business insurance calculator below can give you a more tailored estimate based on your café details. It also connects you directly with a provider match when you're ready to get quotes.
Coffee Shop Insurance Cost Calculator
Select your state and industry to view average business insurance premiums in your area. Rates are calculated based on a business with 5 employees and $500,000 in annual revenue.
Select Coverage Type
Select Employee Count
Select Vehicle Type
Select State
Average Monthly Cost—
Select Coverage Type
Average Monthly Cost—
Select Employee Count
Select Vehicle Type
Select State
How To Buy The Best Coffee Shop Business Insurance
I've outlined the buying process below step by step. If you want something to take with you while gathering quotes, download the coffee shop business insurance buying worksheet to keep everything organized across providers.
- 1
Identify Required Coverages
Start with your lease. Almost every commercial landlord requires general liability before you get the keys, and many require the landlord to be named as an additional insured on your GL policy. That endorsement has to be added through your carrier. Handing your landlord a certificate of insurance (COI) proves coverage exists, but it does not extend your policy to cover them. If your café holds a beer or wine license, check whether your state requires proof of liquor liability as a licensing condition. Then look at your employee count, since most states mandate workers' comp from your first hire regardless of hours worked.
Read More: Business Insurance Requirements
- 2
Map Your Café Risks to Coverage
Walk through a realistic worst-case scenario and test which policy would actually respond. Say your espresso machine boiler fails on a Friday evening, forcing a weekend closure. Commercial property alone won't cover the lost revenue from those two days. You need equipment breakdown coverage and a business income endorsement to bridge that gap. Do the same exercise for a barista burn injury, a customer slip near the condiment station, a spoiled dairy order after a power outage and a data breach through your POS system. Any risk without a clear policy match is a gap worth closing before it becomes a claim.
- 3
Set Limits That Reflect Your Actual Exposure
Your lease minimum and your actual exposure are not the same thing. A $1 million per occurrence GL limit satisfies most landlords, but a serious burn injury lawsuit or a multi-party slip-and-fall claim can push costs well past that ceiling. Size your limits against what a worst-case claim would actually cost your shop, not what the lease requires as a floor. A café running catering, holding a liquor license and managing a team of baristas carries more scenarios that can exhaust lower limits than a counter-only operation with no employees.
Read More: How Much Business Insurance Do I Need?
- 4
Research Providers Specific to Your Café
Not every insurer writes food service coverage the same way. Some include equipment breakdown and food spoilage in their BOP by default. Others treat them as add-ons or exclude them entirely. Before requesting quotes, confirm that each provider on your list covers your specific operation, including liquor service if you pour, catering if you travel off-site and hired auto if baristas use personal vehicles for supply runs. A provider that prices well for a simple counter-service shop may not have the endorsements a full-service café with evening wine service actually needs.
- 5
Compare Quotes With Identical Terms
Look up what coffee shop insurance typically costs for your operation size so you have a reference point before quotes arrive. Then request quotes using the same limits, deductibles and endorsements from every provider. A policy that looks $30 cheaper per month but carries a higher deductible, excludes food spoilage or narrows your equipment breakdown coverage is not a real savings. Line up the same terms across every quote so the price comparison reflects actual coverage differences.
- 6
Review Your Policy Before Signing
Read the policy document against your lease, your licensing requirements and any catering contracts before committing. Confirm the named insured matches your business's legal name exactly, because even a minor mismatch can create compliance problems when your landlord or a catering client checks your paperwork. Check whether your BOP includes equipment breakdown and food spoilage or whether those need to be endorsed separately. Verify that your GL aggregate is high enough to absorb more than one claim in a policy year if your shop runs steady foot traffic.
- 7
Reassess Your Needs As Your Café Changes
Hiring your first barista triggers workers' comp in most states. Adding a beer or wine license introduces liquor liability. Moving into catering changes your GL exposure and may require commercial auto or a hired and non-owned auto endorsement. Opening a second location means your property coverage needs to extend to a new address it was never written for. Any of those shifts can create gaps in a policy that fit your shop perfectly six months ago. Review coverage at least once a year and before any major operational change.
Coffee Shop Insurance: FAQ
Beyond what this guide covers, I've answered the most common remaining questions café owners have before purchasing business insurance.
Coffee shop business insurance is a set of policies built around the specific ways a café creates financial risk. General liability responds when a customer is burned or slips on a wet floor. Commercial property covers the espresso equipment and build-out your landlord's policy ignores. Workers' comp pays when a barista is injured behind the bar. The right combination depends on your menu, your staffing, whether you serve alcohol and how your lease is structured.
It depends on your state, your employee count and your lease. Most states require liability coverage from commercial tenants as a lease condition rather than a statute, so the mandate comes from your landlord, not the government. Workers' compensation rules kick in at your first hire in nearly every state, with the threshold varying from one employee to five depending on where you operate. A liquor license may also trigger a separate insurance requirement at the state level.
Most landlords require proof of general liability coverage before handing over the keys. That typically means providing a COI naming the property owner as an additional insured on your GL policy. Some landlords also require a minimum coverage limit written into the lease itself. If you cannot show proof of active coverage by the lease start date, the landlord can withhold access to the space, delay your build-out or void the agreement entirely.
In almost every case, your landlord will ask for a certificate of insurance that shows your general liability coverage is active and lists your policy limits. Many leases also require you to add the landlord as an additional insured through a policy endorsement, which your insurer adds separately from the COI.
A COI only proves you have coverage. It doesn't extend your coverage to the landlord. Read your lease to see whether you need the endorsement as well as the certificate.
Yes. A standard general liability policy excludes claims related to alcohol service. The moment you hold a beer or wine license you need a separate liquor liability policy or an endorsement added to your GL. Some states require proof of liquor liability as a condition of maintaining the license. If a patron is overserved at your shop and injures someone after leaving, the claim falls entirely outside your GL coverage without that addition in place.
Pull up your GL policy and check whether it extends coverage beyond your listed premises. Many café policies are written for a single fixed location and do not automatically cover you when your team serves at an outside venue. If the policy language limits coverage to your shop address, you need either a scheduled premises endorsement or a separate event policy before your staff works off-site. Catering clients will often verify this before signing a contract.
Your coverage requirements shift whenever your operation does. Hiring your first employee triggers workers' comp. Adding a liquor license introduces a new liability category. Buying a delivery vehicle or sending baristas on supply runs in personal cars creates commercial auto exposure. Opening a second location means property coverage needs to be restructured. Any of these changes can leave you underinsured if your policy is still built around the shop you ran six months earlier.
Best Coffee Shop Business Insurance: The Bottom Line
You now know which providers fit different types of café operations, what coverage your shop actually needs and what those policies cost. The piece most owners get wrong is buying the minimum their lease requires and treating it as complete protection. A lease minimum satisfies your landlord. It does not cover a boiler failure that shuts you down for a weekend, a barista burn claim that exceeds your aggregate or a spoiled dairy order after a power outage. The right policy accounts for how your shop actually runs, not just what the lease says.
When you start comparing quotes, make sure every provider is quoting the same limits, deductibles and endorsements. And as a reminder before you compare, these are my top picks overall for coffee shops.
Get Coffee Shop Business Insurance Quotes
No two coffee shops pay the same rate, and the provider that fits your single leased café may not be the right match if you run catering, hold a liquor license or manage multiple locations. Request business insurance quotes below to get matched with a provider that fits your operation.
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com
Sources
- Verisk. "The rising cost of slip and fall claims for US businesses." Accessed November 6, 2026.
- NEXT Insurance. "How to protect your restaurant business from common and costly insurance claims." Accessed November 6, 2026.
- Merkel & Cocke, P.A.. ""Barista Wrist" Injuries are a Leading Cause of Workers' Compensation Claims." Accessed November 6, 2026.
- PolicySweet. "Workers Compensation Insurance: Why Does Your Coffee Shop Need it?." Accessed November 6, 2026.