
Best Professional Liability Insurance (E&O) Companies in New Mexico

Our analysis of New Mexico professional liability insurers found three providers that consistently outperformed on rates, coverage quality and overall service experience.

  1. ERGO NEXT: Buying a policy takes about 10 minutes online, no agent required, with an instant certificate of insurance you can share with clients from your phone. That speed and simplicity earned ERGO NEXT the top position, and it backs it up with the lowest rates among New Mexico's top-ranked providers. The insurer ranks first overall across 15 of 18 industries in the state, which works well for the widest range of New Mexico businesses.
  2. The Hartford: More than 200 years in the industry gives The Hartford a depth of claims-handling infrastructure that newer digital carriers haven't built yet. It ranks first in New Mexico for Hospitality, Travel and Tourism, Real Estate and Beauty and Wellness, and its professional liability policies can be bundled directly into a business owner's policy, which simplifies coverage management for businesses that need more than one line. New Mexico businesses in health care or other professional services should look elsewhere, as The Hartford ranks ninth in both categories for the state.
  3. Hiscox: Coverage tailored to more than 180 industries makes Hiscox a strong pick for white-collar professionals who need a policy that reflects what they do. It ranks first in New Mexico for Tech/IT and is a consistent top-two finisher for financial services, nonprofits and consulting. Construction and recreation businesses will find better-matched options with other providers.

These three providers are the best fit for most New Mexico businesses, but no ranked list covers every situation. Comparing business insurance options side by side and pulling quotes directly from carriers gives you the clearest picture of what's right for your business.
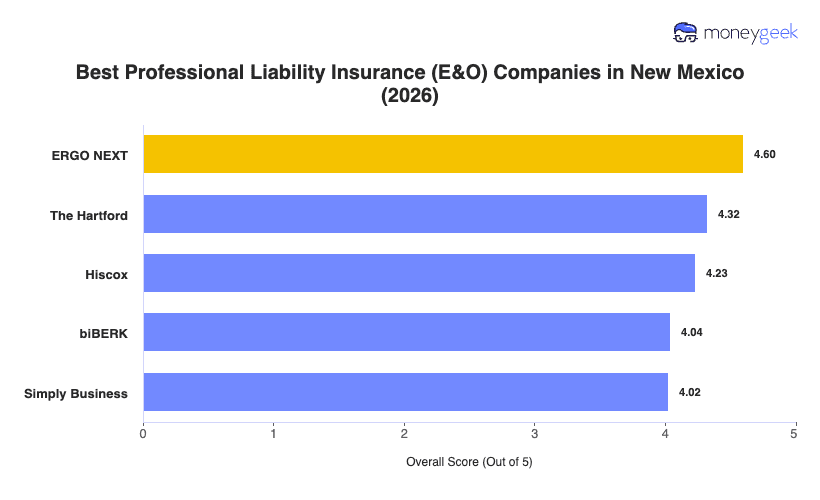
ERGO NEXT4.6011$38
The Hartford4.3234$46
Hiscox4.2347$47
biBERK4.0479$54
Simply Business4.0292$53

How to Get the Best Professional Liability Insurance in New Mexico

Your industry, your clients and your region shape both what coverage you need and what you'll pay, so getting professional liability coverage that actually fits starts with a few deliberate steps.

  1. 1

    Check your NM licensing board requirements first

    Find out whether your profession has a mandatory coverage floor before you shop. The New Mexico Real Estate Commission requires active brokers to carry E&O before a license is issued, and physicians in the state's Patient Compensation Fund must carry at least $250,000 per occurrence. Confirm any threshold through your board or the New Mexico Office of the Superintendent of Insurance.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on contract size, who sits on the other side of them and what a claim could realistically cost. Lower-risk service businesses often land at $250,000 to $500,000 per occurrence, while physicians, engineers and childcare operators may need $1 million to $2 million. Use those tiers as a starting point for how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the NM market

    New Mexico's economy shifts sharply by region, from Albuquerque's tech and federal contracting to Farmington's energy sector and the Borderplex's cross-border trade. An agent grounded in your industry will steer you toward the right limits and carriers. Prioritize industry experience over ZIP code familiarity.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Price alone can leave you underinsured. Look closely at whether defense costs are paid inside or outside the limit, what the retroactive date covers and which exclusions apply to your specific work. An IT consultant whose policy excludes intellectual property claims, for example, may be exposed on the exact claim most likely to arise from a Sandia or Los Alamos contract.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Confirm any carrier is licensed to write professional liability in New Mexico before binding, then check its claims-handling record, which matters in the state's active litigation environment. Physicians should work through a broker with specific experience in the Patient Compensation Fund structure.

  6. 6

    Consider bundling with other business coverage

    Combining professional liability with general liability or a business owner's policy typically reduces premiums 10% to 15% versus buying each separately. Bundling also simplifies your renewal cycle and closes gaps between policies. Carriers like The Hartford let you add E&O directly to a BOP.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    New Mexico policies are written on a claims-made basis, so the policy active when a claim is filed pays, not the one active when the work was done. A lapse of even one day voids protection for all prior work. If you switch carriers or retire, buy tail coverage from your prior insurer to extend reporting for past work.

Best New Mexico Professional Liability Insurance (E&O): Bottom Line

The right professional liability coverage in New Mexico comes down to your industry, the contract requirements your clients set and the limits your budget supports. ERGO NEXT takes the top spot in our analysis, but it won't be the best fit for every business. Physicians working through the state's Patient Compensation Fund, for instance, are better off starting with a broker who specializes in New Mexico's malpractice market. Confirm your licensing board's requirements first, then compare quotes from at least three carriers before committing.

Best Professional Liability Insurance New Mexico Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best NM small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance NM: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources