
Best Professional Liability Insurance (E&O) Companies in Kentucky

Our analysis of Kentucky professional liability insurers found three providers that consistently outperformed the field on rates, service quality and coverage breadth.

  1. ERGO NEXT has the highest affordability score of the three. It also holds the top overall ranking, with consistently strong scores across every category. It ranks #1 across 14 of 18 industries in Kentucky, including health care, financial services, consulting, construction and cleaning services. No industry in Kentucky ranks it at the bottom of the field. That makes it a safe choice for most businesses in the state.
  2. The Hartford earns the second spot for its deep profession-specific coverage options. It ranks #2 in Kentucky for arts, education and marketing professionals, and it holds the same spot for fitness, hospitality and real estate businesses. These industries often have client contracts that demand specific coverage terms. Health care and other professional services are its weak spot: it ranks ninth, so medical practices and similar businesses should look elsewhere.
  3. Hiscox is the best overall option for tech businesses in Kentucky, ranking #1 in Tech/IT statewide. It also ranks #2 for consulting, financial services, beauty and wellness, childcare and nonprofits. Its coverage score is competitive, and no Kentucky industry ranks it in the bottom tier.

These three are strong fits for most Kentucky businesses. No ranked list covers every situation, so comparing business insurance options side by side gives you the clearest picture of what a provider offers for your profession.
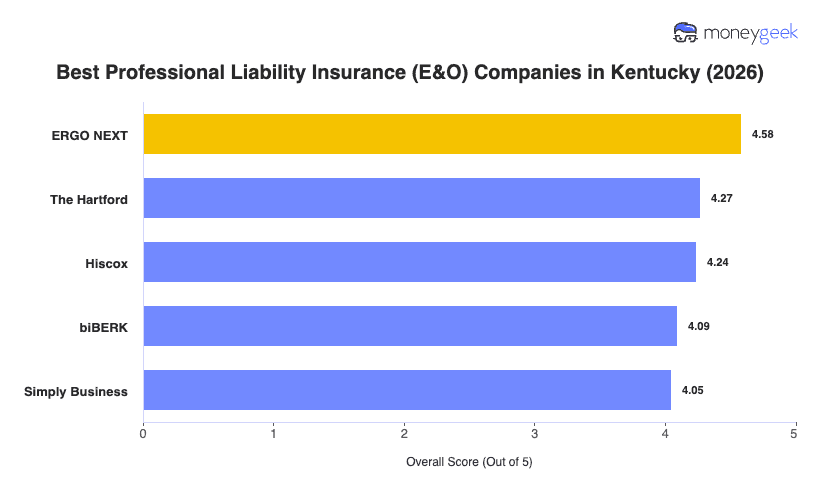
ERGO NEXT4.5811$38
The Hartford4.2734$45
Hiscox4.2447$44
biBERK4.0979$49
Simply Business4.0592$50

How to Get the Best Professional Liability Insurance in Kentucky

Kentucky businesses have several paths to getting professional liability coverage, and these seven steps walk you through buying a policy that fits your profession, your region and your clients.

  1. 1

    Check your KY licensing board requirements first

    Confirm whether your profession faces a mandatory coverage floor before you shop. Real estate licensees must carry at least $100,000 per claim and $1 million aggregate, and attorneys practicing through an LLC, PLLC or LLP must maintain adequate coverage under Kentucky Supreme Court rules. 

    Where to check: the Kentucky Department of Insurance company search confirms a carrier is licensed in the state.

  2. 2

    Assess your coverage needs based on your work and clients

    Your tier depends on what a client could lose if your work goes wrong and what your contracts already require. Lower-stakes service businesses often sit at $250,000 to $500,000, Louisville and Lexington enterprise clients commonly require $1 million, and health care providers and public-project engineers typically land at $1 million to $2 million. Match the tier to your exposure when deciding how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the KY market

    Coverage needs differ across Kentucky's regions, so an agent who knows your industry beats a general commercial-lines background. Louisville concentrates health care, logistics and financial services in the state's most litigated metro, Lexington centers on equine services and the University of Kentucky health system, and Bowling Green draws automotive and manufacturing suppliers with large-contract exposure.2

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Don't compare on price alone, since two policies priced the same can carry very different deductibles, defense structures and exclusions. Confirm the policy covers your specific work rather than generic services, and check whether defense costs are paid inside or outside your limit, because a policy that erodes with legal fees leaves less for a settlement than it appears. Review what a policy covers before you decide.

  5. 5

    Research providers beyond price

    Verify the carrier is licensed in Kentucky, then check its claims-handling track record. A low premium from an insurer that disputes claims aggressively costs more in the end. Kentucky professionals can cross-reference carriers through the Kentucky Bar Association, the Kentucky Medical Association and the Kentucky Real Estate Commission's approved carrier list.

  6. 6

    Consider bundling with other business coverage

    Pairing professional liability with general liability or a business owner's policy typically saves Kentucky businesses 10% to 15% on combined premiums. Most insurers writing professional liability also write general liability, so packaging both with one carrier reduces overhead and closes coverage gaps.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Kentucky policies are almost always claims-made, so the policy active when a claim is filed, not when the work was done, is the one that pays. A single day without coverage can leave past work unprotected. If you switch carriers or retire, buy tail coverage to protect claims that surface after the policy ends.

Best Kentucky Professional Liability Insurance (E&O): Bottom Line

The right professional liability coverage in Kentucky comes down to your industry, what your clients put in their contracts and how much financial exposure a single claim could create. ERGO NEXT earns the top overall rating, but it isn't the right fit for every profession. Health care businesses and other professional services providers, for instance, will find better pricing and coverage fit elsewhere. Get quotes from at least three carriers, compare policy terms side by side and confirm your chosen insurer is licensed in Kentucky before signing anything.

Best Professional Liability Insurance Kentucky Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best KY small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance KY: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources