
Best Professional Liability Insurance (E&O) Companies in Minnesota

Our analysis of Minnesota professional liability insurers found three providers that consistently outscored the field on rates, customer experience and coverage breadth.

  1. ERGO NEXT: Ranked first overall in Minnesota with the highest customer experience score (4.47 out of 5) and the top coverage score among all providers in the state, ERGO NEXT earns its position through a buying process that's straightforward from quote to policy and a coverage structure that works across a wide range of professions. It ranks first in 10 of the 18 industries tracked in Minnesota, including health care, construction, real estate, childcare and pet care. That breadth makes it a strong fit for most Minnesota businesses, regardless of sector. No industries in the state ranked it in the bottom tier.
  2. The Hartford: The highest affordability score in Minnesota (4.52 out of 5) belongs to The Hartford, and for consulting firms, financial services businesses and hospitality operators, it's the top-ranked provider in the state. With more than 200 years in the industry, it brings dedicated small-business underwriting, risk management resources and a claims team built for professional services work. The one area to watch: health care providers and other professional services businesses will find better-suited options, as The Hartford ranks ninth in both categories for Minnesota.
  3. Hiscox: Nonprofits and tech businesses in Minnesota get the best fit with Hiscox, which ranks first in both industries statewide. It also ranks second for consulting and financial services, making it a solid option for knowledge-economy businesses across the Twin Cities metro. Hiscox offers coverage to a wide range of professions and a fully online buying experience with support available around the clock.

Ranked providers represent the best fit for most Minnesota businesses, but no single list covers every situation. Comparing business insurance options side by side and pulling quotes directly from multiple carriers gives you a clearer picture of what each policy covers at the price you'll pay.
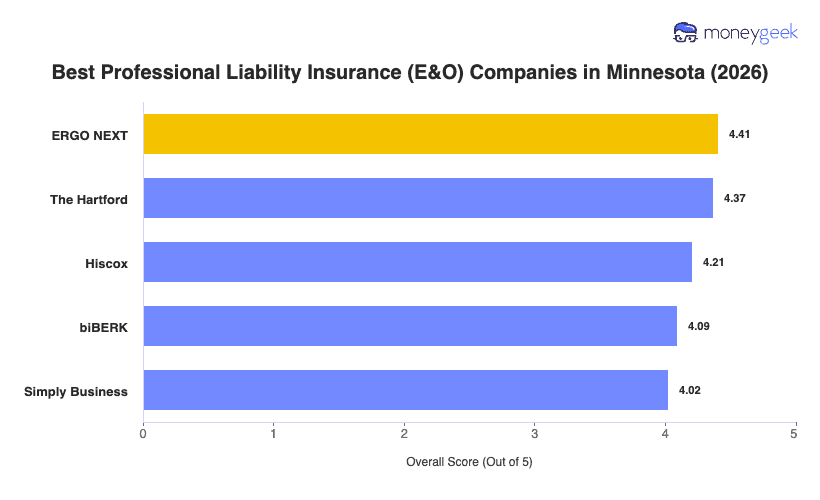
ERGO NEXT4.4111$49
The Hartford4.3734$42
Hiscox4.2147$46
biBERK4.0979$50
Simply Business4.0293$51

How to Get the Best Professional Liability Insurance in Minnesota

The right approach to getting professional liability coverage in Minnesota depends on your profession, your clients and where in the state you operate.

  1. 1

    Check your MN licensing board requirements first

    Find out whether your profession has a mandatory coverage floor before you shop. Minnesota childcare providers must carry liability insurance to be licensed, attorneys must disclose their coverage status annually to the state Supreme Court, and hospitals require malpractice coverage for credentialing. Check your licensing board for thresholds tied to your license type.

  2. 2

    Assess your coverage needs based on your work and clients

    Match your coverage tier to the scale of harm your work could cause and what your contracts require. Smaller consultants and service businesses often sit at $250,000 to $500,000, while IT consultants, attorneys and CPAs commonly need $500,000 to $1 million. Physicians, architects and licensed childcare centers typically need $1 million to $2 million. This is the core of how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the MN market

    Coverage demands vary across the state. Twin Cities tech and financial vendors face enterprise contract limits of $1 million or more, Rochester health care providers deal with Mayo-tier credentialing, and Duluth contractors work under government contract rules. An agent focused on your industry knows what local clients actually require.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Two quotes at the same premium can cover very different things. Check whether defense costs sit inside or outside the policy limit, confirm the retroactive date on any claims-made policy, and make sure exclusions don't carve out your type of work.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Confirm any insurer is licensed to write coverage in Minnesota through the Minnesota Department of Commerce. Look at claims-handling track record for your profession, not just financial strength, and check relevant state associations for sponsored E&O programs.

  6. 6

    Consider bundling with other business coverage

    Combining professional liability with general liability or a business owner's policy from one carrier cuts premiums by 10% to 15% versus buying separately. If you need both, ask about bundling when you request quotes.

  7. 7

    Don't let your coverage lapse, and understand tail coverage

    Minnesota professional liability policies are almost always claims-made, so coverage applies when the claim is filed, not when the work was done. If you switch carriers or lapse without securing tail coverage, claims filed later for prior work go uncovered. Secure tail coverage or a matching retroactive date before canceling an old policy.

Best Minnesota Professional Liability Insurance (E&O): Bottom Line

Choosing the right professional liability policy in Minnesota comes down to your industry, what your client contracts require and how much coverage your work demands. ERGO NEXT earns the top overall rating for the state, but a Minneapolis financial services firm working with enterprise clients and a Rochester childcare operator have very different needs that may point to different providers. Pull quotes from at least three carriers, confirm the retroactive date covers your prior work, and verify the carrier is licensed through the Minnesota Department of Commerce before you bind.

Best Professional Liability Insurance Minnesota Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best MN small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance MN: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources