


I recommend ERGO NEXT for most Minnesota small businesses as it's the best business insurance provider in my analysis. It averages $94 per month, and while it isn't the most affordable provider in my study, it lets you create or update COIs online without waiting on an agent. If keeping premiums down matters more, The Hartford averages $78 and can package liability, property and business income coverage in a BOP.
Best Small Business Insurance in Minnesota
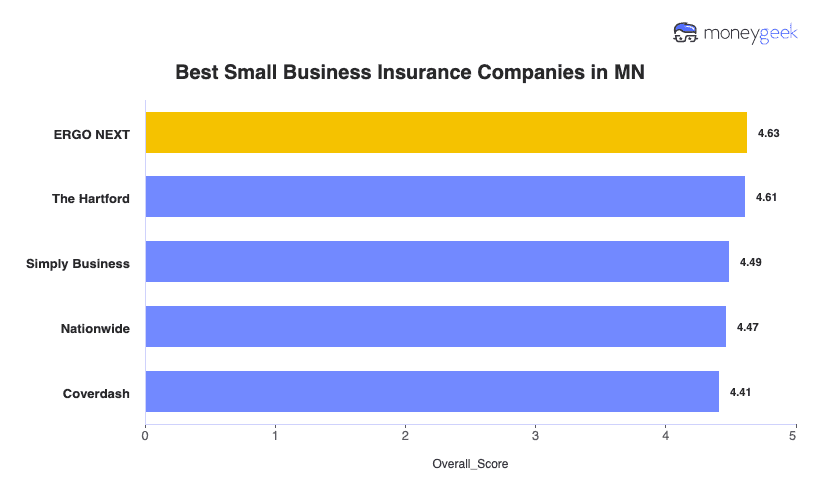
My 2026 analysis found that ERGO NEXT, The Hartford and Simply Business are the best business insurance providers in Minnesota.
Your work and the risks it brings, whether you have employees, your budget and post-purchase support preferences help determine which carrier is best for your businesses.
With our matching tool below, MoneyGeek can help you get Minnesota business insurance quotes from the insurer that best fits your operations.
Select state
Updated: September 6, 2026
Advertising & Editorial Disclosure
Best Small Business Insurance Companies in Minnesota
| ERGO NEXT | 4.63 | $94 | 1 | 2 |
| The Hartford | 4.61 | $78 | 2 | 3 |
| Simply Business | 4.49 | $91 | 5 | 1 |
| Nationwide | 4.47 | $95 | 2 | 4 |
| Coverdash | 4.41 | $95 | 6 | 2 |
| biBERK | 4.39 | $98 | 2 | 5 |
| Progressive Commercial | 4.32 | $93 | 7 | 5 |
| Thimble | 4.30 | $88 | 8 | 5 |
| Hiscox | 4.27 | $101 | 4 | 6 |
| Chubb | 4.26 | $110 | 3 | 4 |
Note: These Minnesota estimates are meant to help you compare coverage costs on equal footing. MoneyGeek’s methodology models a business with two employees across 79 major industries. Your own premium can come out higher or lower depending on your business classification, where you operate and the coverage limits you select.

ERGO NEXT
Best Minnesota Business Insurance
MoneyGeek Rating
4.6/ 5
4.5/5Affordability
4.7/5Customer Experience
4.8/5Coverage Options
Average Monthly Cost of General Liability Insurance
$97This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
$65This rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Survey: Digital Experience
4.8/5 (1st)Our Survey: Likely to Be Recommended to Others
4.8/5 (1st)

The Hartford
Cheapest Minnesota Business Insurance
MoneyGeek Rating
4.6/ 5
4.6/5Affordability
4.6/5Customer Experience
4.7/5Coverage Options
Average Monthly Cost of General Liability Insurance
$77This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
$66This rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Survey: Claims Process
4.5/5 (1st)Our Survey: Agent Service
4.7/5 (1st)

Simply Business
Best Commercial Coverage Options in Minnesota
MoneyGeek Rating
4.5/ 5
4.4/5Affordability
4.2/5Customer Experience
4.9/5Coverage Options
Average Monthly Cost of General Liability Insurance
$90This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
$67This rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Research: Digital Experience
4.5/5Our Survey: Provider Service
4.0/5
How to Get the Best Cheap Business Insurance in Minnesota
The insurance challenges Minnesota businesses encounter are unique. These include universal workers' comp mandates, severe weather and property deductibles. Get business insurance that balances these costs with adequate protection using a strategic approach.
- 1
Assess what coverage your Michigan business actually needs
Start with the rules that apply to the way you operate. Michigan workers’ comp requirements can come into play as you hire, and vehicles used for work need appropriate commercial auto protection. Then look beyond compliance. A manufacturer near Detroit may have costly machinery to protect, while a business along the Great Lakes may need to think separately about flood exposure because standard commercial property policies generally exclude flooding.
Read More: How Much Business Insurance Do I Need?
- 2
Get quotes from affordable providers with strong customer ratings
Ask each insurer to price the same protection so you can compare the premiums fairly. Keep your liability limits consistent, then use the same deductible for every quote. When comparing business insurance quotes, I’d also ask whether the insurer regularly writes businesses like yours. If standard carriers won’t offer workers’ comp coverage, Michigan’s assigned-risk market can provide a fallback.
- 3
Check insurer reliability before committing to save a few dollars
Michigan winters can create losses across a wide area at once, so claims service matters. Ask how quickly the insurer typically arranges an inspection after severe weather and how it handles a surge in business claims. For a company that depends on its location or equipment to generate revenue, a slow claim can cost much more than a small monthly premium difference.
- 4
Cut insurance costs without reducing your protection
You have several ways to lower business insurance costs before you start cutting coverage.
- Check whether a BOP fits: Combining general liability with commercial property may cost less than buying them separately.
- Compare payment options: Paying the full term upfront can help you avoid installment fees if your cash flow allows it.
- Ask about your claims record: A history without recent losses may qualify you for better pricing.
- Show insurers what you’re doing to reduce risk: Documented workplace safety measures can sometimes support discounts.
- 5
Secure coverage that meets client contract requirements
Michigan law isn’t the only place insurance requirements can come from. A commercial lease may set minimum liability limits, while a larger client contract can require more coverage before work begins. Check the agreement first, then make sure your insurer can provide a certificate of insurance (COI) on time. If the other party must be protected under your policy, confirm whether you need an additional insured endorsement.
- 6
Change your coverage when the business changes
Treat coverage changes as part of the business decision itself. Hiring can affect your workers’ comp obligations, so check the policy before the new employee starts. Buying a work truck creates a different insurance need immediately. You may also need higher liability limits when a larger contract comes along, rather than waiting until your next renewal to make the adjustment.
Best Business Liability Insurance in Minnesota: Bottom Line
ERGO NEXT, The Hartford and Simply Business lead Minnesota business insurance with strong service and competitive rates. Your best choice depends on whether you prioritize storm damage claims handling, need MJUA high-risk coverage or want bundled policies that offset Minnesota's rising property insurance costs.

LOOKING FOR THE BEST INSURANCE FOR A SPECIFIC COVERAGE TYPE?
You'll often need multiple coverages in your business insurance policy, and the best provider for each of these could vary. These pages show our recommended insurers.
Business Insurance in Minnesota: FAQ
Small business owners in Minnesota often have questions about finding the right business insurance coverage. We answer the most common questions below:
Start with the coverage tied to how your Minnesota business operates. Hiring can bring workers’ compensation into play, while customer-facing businesses may need coverage for slip-and-fall claims. I’d also check any lease or client agreement before buying coverage, since it may set minimum general liability limits you have to meet.
Business insurance in Minnesota costs $54 to $161 monthly, depending on coverage types. Industry and risk factors drive these price differences. Here are average rates for the four most common business insurance types in Minnesota:
- General liability: $129 per month or $1,552 per year
- Workers' comp: $112 per month per employee or $1,338 per year per employee
- Commercial auto: $161 per month per vehicle or $1,934 per year per vehicle
- Commercial property: $122 per month or $1,467 per year
- Professional liability: $54 per month or $645 per year
- Cyber insurance: $85 per month or $1,013 per year
I’d build the package around what could interrupt your income first. A Minnesota retailer needs general liability and property coverage early because both customer injuries and damage to the premises can stop operations. A consulting firm may care less about physical property and put professional liability higher on the list. Start with the exposures that could create the biggest financial setback.
Review the policy before severe weather arrives, not after a loss. I’d check whether your property limit still reflects current replacement costs and how much you’d pay out of pocket through the deductible. Also look closely at business interruption coverage and any weather-related exclusions so you know what would actually respond if hail, wind or winter storms shut you down.
About Connor Bolton

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.
The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.
Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.
Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.