
Best Professional Liability Insurance (E&O) Companies in Kansas

Our analysis of Kansas professional liability insurers found three providers that consistently outperformed the field on rates, coverage quality and service.

  1. ERGO NEXT: Fully digital from quote to certificate, with a buying process that takes about 10 minutes and no phone calls required. That speed and simplicity earned ERGO NEXT the top spot, backed by rate competitiveness that holds across almost every industry in Kansas, from cleaning services and pet care to construction and financial services. The insurer is backed by Munich Re through its parent ERGO Group, which adds meaningful financial depth behind the policies. Kansas businesses in hospitality should compare closely, as ERGO NEXT ranks fourth in that category in the state.
  2. The Hartford: A 200-plus year track record gives The Hartford something most competitors can't match: deep institutional knowledge of how professional liability claims actually play out. It earns particularly strong marks for real estate and tech professionals in Kansas, ranking first in both industries statewide. The insurer also allows businesses to bundle professional liability directly into a BOP, which simplifies policy management and can reduce combined premiums. Kansas healthcare providers and other professional services businesses should look elsewhere though, as The Hartford ranks ninth in both of those categories for the state.
  3. Hiscox: The strongest option in Kansas for nonprofits, financial services firms and consultants, where it ranks first or second statewide. Hiscox writes coverage across more than 180 professions and keeps underwriters who specialize by industry, which shows up in policy terms that are more tailored than what generalist carriers produce. Its claims team operates with high individual authority levels, meaning straightforward claims move faster than at carriers requiring multiple approval layers.

No ranked list covers every situation a Kansas business might have. Comparing business insurance options side by side and getting direct quotes from each carrier gives you the clearest picture of what you'd actually pay and what you'd actually get.
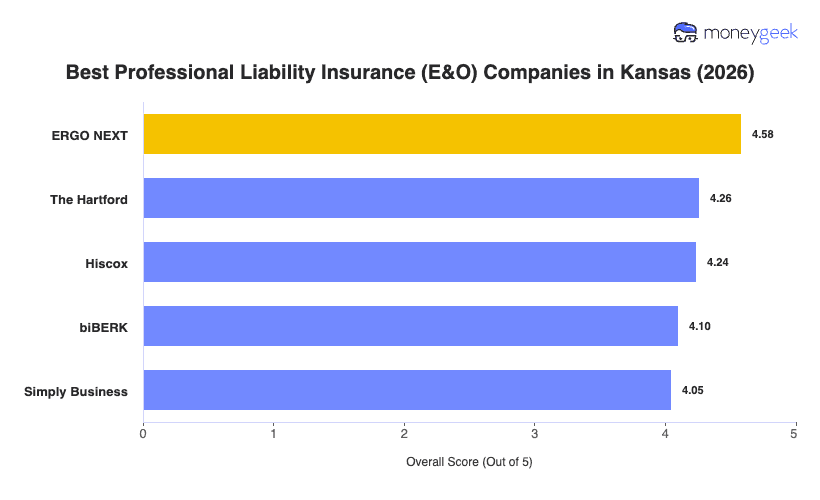

ERGO NEXT4.5811$39
The Hartford4.2634$46
Hiscox4.2447$45
biBERK4.1079$50
Simply Business4.0592$51

How to Get the Best Professional Liability Insurance in Kansas

Kansas businesses have several routes to getting professional liability coverage, and these seven steps walk you through buying a policy that fits your industry, your clients and where you operate.

  1. 1

    Check your KS licensing board requirements first

    Confirm whether your profession faces a mandatory coverage floor in Kansas before you shop. Licensed healthcare providers must carry at least $500,000 per claim and $1.5 million aggregate and enroll in the Kansas Health Care Stabilization Fund to keep their license. 

    Where to check: the Kansas Department of Insurance company search confirms a carrier is authorized in the state.

  2. 2

    Assess your coverage needs based on your work and clients

    Your limit should reflect the financial size of what could go wrong, not just the premium. Lower-exposure freelancers and service businesses often sit at $250,000 to $500,000, while Johnson County enterprise contracts routinely require $1 million and healthcare providers commonly land at $1 million to $2 million. Match the tier to your revenue and contracts when deciding how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the KS market

    Kansas varies by region, so an agent who knows your industry beats a generalist quoting online. Wichita centers on aerospace, healthcare and construction, Overland Park concentrates tech and financial firms that often serve clients across the Missouri line, and Topeka runs on state government and consulting contracts.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Rate is one factor, but policy terms often matter more. Check whether defense costs are paid inside or outside your limit, review each claims-made policy's retroactive date, and confirm which exclusions apply to your specific work, such as IP infringement for software firms.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Confirm any carrier is authorized to write professional liability in Kansas before you bind, then look at its claims track record in your profession. Kansas associations like the Kansas Bar Association, the Kansas Medical Society and the Associated General Contractors of Kansas keep profession-specific carrier recommendations worth checking.

  6. 6

    Consider bundling with other business coverage

    Combining professional liability with general liability or a business owner's policy often cuts your total premium by 10% to 15%. ERGO NEXT, The Hartford and Hiscox all offer bundled options for Kansas businesses.

  7. 7

    Do not let your coverage lapse, and understand tail coverage

    Kansas policies are almost always claims-made, so the policy must be active when a claim is filed, not just when the work happened. If you switch carriers or close your business, buy tail coverage to protect prior work, which typically costs 100% to 200% of your final annual premium.

Best Kansas Professional Liability Insurance (E&O): Bottom Line

The right professional liability coverage in Kansas comes down to your industry, what your clients contractually require and how much financial exposure your work creates. ERGO NEXT earns the top overall rating, but it isn't automatically the right call for every business. A Wichita healthcare provider working through the Kansas Health Care Stabilization Fund has different needs than a Johnson County tech firm whose enterprise clients set their own coverage floors. Confirm your profession's requirements, set limits that match your contracts and compare quotes from at least three carriers before committing.

Best Professional Liability Insurance Kansas Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best KS small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance KS: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources