


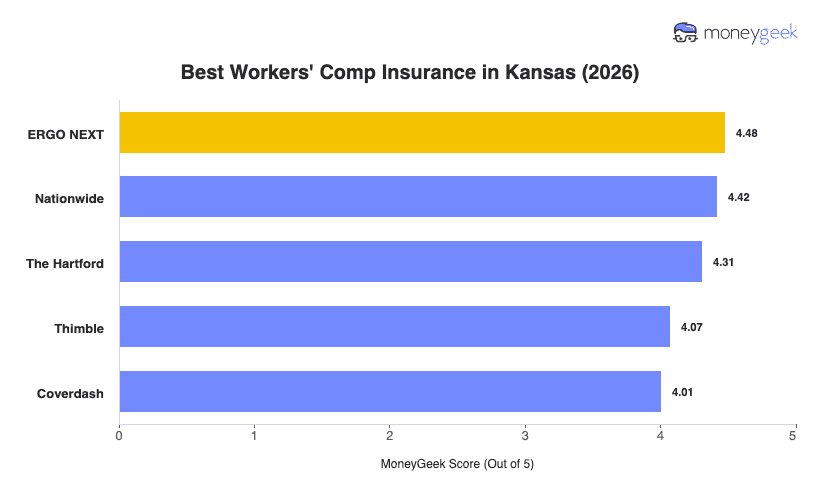
ERGO NEXT is the best workers' compensation insurance provider in Kansas. Although it doesn't have the lowest rates on average, you still save around $19 per month. It lets you quote, purchase and manage your workers' comp policy entirely online, which suits business owners who prefer to manage their coverage on their own.
Best Workers' Comp Insurance in Kansas (2026)
With rates as low as $9 per month, ERGO NEXT, Nationwide and The Hartford have the cheapest and best workers' comp insurance in Kansas.
Use our matching tool to get connected to top Kansas workers' comp insurance providers and find your ideal coverage.
Select state
Safe & SecureVerified and VettedTrusted Brands
Updated: October 1, 2026
Advertising & Editorial Disclosure
Best Workers' Comp Insurance Companies in Kansas
| ERGO NEXT | 4.48 | $55 | 1 | 6 |
| Nationwide | 4.42 | $55 | 6 | 5 |
| The Hartford | 4.31 | $70 | 3 | 3 |
| Thimble | 4.07 | $66 | 8 | 9 |
| Coverdash | 4.01 | $78 | 5 | 1 |
MoneyGeek analyzed workers' comp insurance rates and provider performance across Kansas using small business profiles with one to four employees spanning 408 major industries. Companies earn up to five points in each category in our scoring system. We then use a weighted average of these category scores to calculate an overall MoneyGeek score out of five.
- Affordability (55%): Based on average payroll for the most common employee code per industry and state classification, priced per employee for a one to four employee business.
- Customer Experience (35%): Evaluates buying (20%), which covers quote access, pricing accuracy and sales support; policy management (30%), which covers payroll reporting, audits, billing and loss control; and claims (50%), which covers FNOL speed, adjuster support, medical access, wage replacement and dispute handling.
- Coverage Options (10%): Assesses coverage completeness (35%), including employers' liability and wage and medical reimbursement; policy flexibility and endorsements (25%); eligibility, state and industry breadth (20%); and policy terms, limits and exclusions (20%).

ERGO NEXT
Best Workers' Comp Insurance in Kansas
MoneyGeek Rating
4.5/ 5
4.8/5Affordability
4.2/5Customer Experience
4.1/5Coverage
Average Monthly Cost
$55Claims Processing Score
4/5Policy Management Score
4.1/5Buying Process Score
4.4/5

Nationwide
Best Kansas Workers' Comp Insurance: Runner-Up
MoneyGeek Rating
4.4/ 5
4.8/5Affordability
4/5Customer Experience
4.2/5Coverage
Average Monthly Cost
$55Claims Processing Score
4/5Policy Management Score
3.9/5Buying Process Score
3.8/5
Cheapest Workers' Comp Insurance in Kansas
In our analysis, the cheapest workers' comp rate available in Kansas is $9 a month for Financial Services employers through The Hartford. At the other end, Transportation & Logistics employers pay as much as $163 a month through ERGO NEXT. These are per-provider rates for the cheapest available carrier in each industry, not state averages. Your actual rate depends on your specific class code, payroll size and claims history.
Two carriers, ERGO NEXT and The Hartford, take the cheapest spot in every single category. ERGO NEXT wins 16 of the 25 industries, including the four most expensive: Transportation & Logistics ($163 a month), Construction ($127 a month), Agriculture ($88 a month) and Wholesale & Distribution ($101 a month). The Hartford wins the remaining nine, nearly all of them white-collar or low-risk categories.
| Agriculture & Natural Resources | ERGO NEXT | $88 | $1,056 |
| Arts, Media & Entertainment | ERGO NEXT | $53 | $636 |
| Beauty, Body & Wellness Services | ERGO NEXT | $9 | $108 |
| Childcare Services | ERGO NEXT | $21 | $252 |
| Cleaning Services | ERGO NEXT | $61 | $732 |
| Construction & Contracting | ERGO NEXT | $127 | $1,524 |
| Consulting Services | The Hartford | $11 | $132 |
| Education | ERGO NEXT | $38 | $456 |
| Financial Services | The Hartford | $9 | $108 |
| Fitness Services | ERGO NEXT | $37 | $444 |
| Food & Beverage | ERGO NEXT | $23 | $276 |
| Healthcare & Medical | The Hartford | $26 | $312 |
| Hospitality, Travel & Tourism | The Hartford | $24 | $288 |
| Manufacturing | ERGO NEXT | $81 | $972 |
| Marketing & Communications | ERGO NEXT | $10 | $120 |
| Nonprofit & Associations | The Hartford | $34 | $408 |
| Other Professional Services | The Hartford | $15 | $180 |
| Pet Care Services | ERGO NEXT | $33 | $396 |
| Real Estate & Property Services | The Hartford | $12 | $144 |
| Recreation & Sports | ERGO NEXT | $59 | $708 |
| Repair & Maintenance | ERGO NEXT | $40 | $480 |
| Retail & Product Rental | The Hartford | $29 | $348 |
| Tech/IT | The Hartford | $22 | $264 |
| Transportation & Logistics | ERGO NEXT | $163 | $1,956 |
| Wholesale & Distribution | ERGO NEXT | $101 | $1,212 |
How to Get the Best Workers' Comp Insurance in Kansas
You'll need to consider several factors when you get workers' compensation insurance for your business. I've broken these down into steps to help you through the process.
- 1
Confirm Kansas Coverage Requirements
Start with payroll rather than head count. Kansas requires workers' comp insurance when your total gross annual payroll exceeds $20,000. Certain agricultural operations and business owners follow different rules. Confirm which wages count before you treat your business as exempt. The Kansas Department of Labor outlines these exceptions.
- 2
Match Employees to the Right NCCI Class Codes
Kansas uses NCCI class codes to group employees by the risks associated with their work. These four-digit codes help determine how much you pay per $100 of payroll. Classify employees according to their actual duties. A shared code for office staff and field crews can distort your quote.
- 3
Prepare Payroll and Claims Records
Give each insurer the same projected annual payroll, broken out by class code. You'll also need loss runs, which show your business's previous workers' comp claims. Kansas bases its coverage requirement on payroll, so accurate figures help insurers price your policy. These figures also confirm whether the $20,000 threshold applies to your business.
- 4
Compare Quotes From Kansas-Licensed Insurers
Carriers build their rates from NCCI loss costs, then add their own expenses and pricing adjustments. Premiums for the same business can differ from one carrier to the next. Compare business insurance quotes using identical payroll and class-code information. If insurers decline your business, Kansas' assigned-risk plan provides a fallback for eligible employers that cannot find coverage in the standard market.
- 5
Consider Access to Authorized Medical Care
In Kansas, you or your insurer selects the authorized health care provider who treats an injured employee. Look beyond the premium and weigh whether a carrier's provider network can serve every location where your employees work. Limited access can delay treatment, especially for businesses operating in rural areas.
- 6
Bind Coverage and Establish an Injury-Reporting Process
Confirm the policy's effective date before employees begin covered work. Tell supervisors where to report injuries. Kansas employers must report employee accidents within 28 days. Build your internal process around that window, since the insurer needs time to submit the required information to the state. A late report risks penalties for your business.
- 7
Recheck Payroll and Class Codes at Renewal
Your insurer will measure estimated payroll against actual payroll during the premium audit. Examine the results for misclassified work and unexpected payroll changes before you renew. In Kansas, this audit also helps you determine whether your annual payroll has crossed the coverage threshold.
Best Workers' Compensation Insurance in Kansas: Bottom Line
ERGO NEXT, Nationwide, and The Hartford are the strongest workers' comp options for Kansas employers. ERGO NEXT leads on MoneyGeek score and affordability. Nationwide matches its rate and suits employers with existing broker relationships, while The Hartford offers the deepest coverage breadth for higher-hazard industries. The right choice depends on your industry, payroll size, and claims history.

LEARN MORE ABOUT KANSAS BUSINESS INSURANCE
Workers' comp is only one part of your Kansas business insurance policy. Use the resource below to see top providers for other coverages.
Kansas Workers' Compensation Insurance FAQ
ERGO NEXT earns the top MoneyGeek score among Kansas workers' comp providers. For employers focused on cheapest rates, here are the five lowest-cost options in the state:
- ERGO NEXT: $55 a month
- Nationwide: $55 a month
- Thimble: $66 a month
- The Hartford: $70 a month
- biBERK: $73 a month
Employers with one or more employees must have workers' comp coverage in Kansas, with limited exceptions for certain agricultural and domestic workers. Compliance and enforcement statewide fall under the Kansas Division of Workers Compensation, housed within the Kansas Department of Labor. Civil fines, stop-work orders and personal liability for the full cost of any employee injuries await employers without workers' comp coverage. These penalties apply no matter when an injury happens during the period of non-compliance.
Workers' comp costs in Kansas state average is $74 per employee per month, based on MoneyGeek's analysis across 408 industries, on par with the $74 national average. Costs range from $13 a month for Beauty, Body & Wellness Services to $222 a month for Transportation & Logistics.
Kansas operates a competitive private market with no state fund, so employers purchase coverage directly from licensed private insurers. If your business cannot obtain coverage in the voluntary market, the Kansas Workers Compensation Assigned Risk Pool through NCCI serves as the fallback option. Coverage must be in place before employees begin work.
Workers' comp policies in Kansas cover four core areas:
- Medical expenses: Kansas workers' comp covers all necessary medical treatment for work-related injuries. The Kansas Division of Workers Compensation, under the Kansas Department of Labor, administers the fee schedule that sets reimbursement rates.
- Wage loss benefits: Temporary total disability pays at 66⅔% of the employee's average weekly wage. Verify the 2026 maximum weekly benefit against the Kansas Division of Workers Compensation under the Kansas Department of Labor.
- Vocational rehabilitation: Workers unable to return to their pre-injury occupation can receive retraining and placement services.
- Death benefits: Burial expenses are covered. Qualifying dependents receive compensation based on the deceased's average weekly wage.
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com