
Best Professional Liability Insurance (E&O) Companies in West Virginia

Our analysis of West Virginia professional liability insurers found three providers that consistently outperformed the rest on rates, coverage quality and customer experience.

  1. ERGO NEXT: Part of Munich Re's ERGO Group, it brings the buying speed of a pure digital insurer with the financial backing of one of the world's largest reinsurance networks. The entire process, from quote to certificate of insurance, runs online without a phone call, which matters for West Virginia contractors, consultants and healthcare businesses that need to move fast. It ranks first in West Virginia across 13 of 18 industries and carries no industry exclusion caveats from our data. Businesses in education should look elsewhere, where it ranks 7th in the state.
  2. The Hartford: Its claims-handling depth and agent-supported buying process suit West Virginia businesses that want a licensed professional walking them through coverage decisions rather than figuring it out alone online. It earns top marks in the state for real estate and education professionals. Healthcare and other professional services businesses will find stronger fits elsewhere, as The Hartford ranks 9th for both in West Virginia.
  3. Hiscox: Its professional liability policies cover more than 180 specific industries, making it the right call for West Virginia nonprofits, financial services firms and tech businesses that need coverage built for their specific work. Its E&O forms run broader than what most mass-market carriers offer, and its coverage depth is hard to match at the small-business level.

The three providers above suit most West Virginia businesses well, but no ranked list covers every situation. Comparing business insurance options side by side and getting quotes directly gives you the clearest picture of what fits your business.
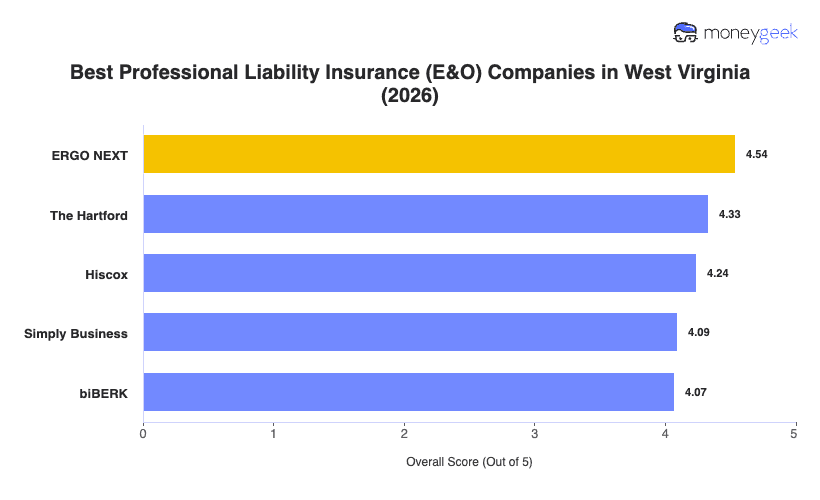
ERGO NEXT4.5411$42
The Hartford4.3334$46
Hiscox4.2447$47
Simply Business4.0992$52
biBERK4.0779$54

How to Get the Best Professional Liability Insurance in West Virginia

Getting professional liability coverage in West Virginia is not one-size-fits-all. Your industry, your location and your clients all shape what you need and what you pay.

  1. 1

    Check your WV licensing board requirements first

    Find out whether your profession carries a mandatory coverage floor in West Virginia. State law doesn't require malpractice coverage, but most hospitals do, attorneys must file an annual Financial Responsibility Disclosure with the West Virginia State Bar, and contractors on projects above $2,500 must be state-licensed.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on your clients, your contracts and what a claim could realistically cost. Smaller-client freelancers often need $250,000 to $500,000 per occurrence, state agency and university contracts routinely require $1 million minimums, and higher-risk fields like medicine and engineering reach $2 million. Use these tiers to gauge how much professional liability insurance you need.

  3. 3

    Work with a local agent who knows the WV market

    West Virginia's business environment varies sharply by region. Charleston and the Kanawha Valley concentrate government contractors, law firms and healthcare organizations, Morgantown's tech sector runs on WVU's research economy, and Huntington leans on healthcare, manufacturing and logistics. An agent who works across these markets will price your risk more accurately than one who doesn't.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Rate comparisons only tell part of the story. Check whether defense costs fall inside or outside your limits, what your deductible is, and which exclusions apply to your specific work. Confirm the claims-made versus occurrence structure, retroactive date and subcontractor coverage before signing.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Verify that any insurer you're considering is licensed in West Virginia through the West Virginia Offices of the Insurance Commissioner. Beyond licensure, look at the carrier's track record for paying claims in your industry. Groups like the West Virginia State Bar, the West Virginia Society of CPAs and the West Virginia Hospital Association maintain insurer resources for members.

  6. 6

    Consider bundling with other business coverage

    Bundling professional liability with general liability or a business owner policy often cuts your combined premium by 10% to 15%. Most contractors, consultants and healthcare businesses need both coverages anyway, so combining them with one insurer captures the strongest savings.

  7. 7

    Do not let your coverage lapse, and understand tail coverage

    Most West Virginia professional liability policies are claims-made, so a claim must be filed while your policy is active to be covered. If you cancel, retire or switch insurers, past work is exposed the moment coverage lapses unless you buy tail coverage. Kanawha, Raleigh and Cabell counties see the most professional claims, so ask a new carrier about prior acts coverage to keep your retroactive date intact.

Best West Virginia Professional Liability Insurance (E&O): Bottom Line

Choosing professional liability insurance in West Virginia comes down to your industry, your client contracts and your budget. ERGO NEXT earns the top spot in our analysis, but it isn't automatically the right fit for every business. A Charleston healthcare practice, a Morgantown nonprofit and a Huntington real estate firm all have different needs and will value providers differently. Get quotes from at least three carriers, confirm each is licensed in the state and compare policy terms rather than price alone.

Best Professional Liability Insurance West Virginia Chart
mglogo icon
LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best WV small business insurance bundle for you will likely include more than professional liability. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance WV: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources