
Best Professional Liability Insurance (E&O) Companies in New Jersey

Our analysis of New Jersey professional liability insurers identified three providers that consistently outperformed the field on coverage quality, customer experience and overall fit for the state's service economy.

  1. ERGO NEXT: A fully digital buying experience and coverage spanning the widest range of New Jersey industries earned ERGO NEXT the top position. The insurer ranks first in the state across arts and media, childcare, construction and contracting, fitness, health care, other professional services, pet care, recreation and tech, making it a strong fit for small businesses across most of New Jersey's service economy.
  2. The Hartford: For New Jersey businesses in consulting, financial services, real estate and marketing, The Hartford ranks first in the state on overall score. Its professional liability policies can be bundled with a business owner's policy, and coverage extends across both the US and Canada, which suits the many New Jersey businesses with clients on both sides of the border. Healthcare and medical professionals should compare other options, as The Hartford ranks ninth in New Jersey for that industry, and the same applies to other professional services.
  3. Hiscox: Founded in 1901, Hiscox brings more than 120 years of specialty insurance experience to New Jersey businesses that need precise, industry-tailored coverage. The insurer covers more than 180 professions and ranks first in the state for nonprofits and associations, with strong performance in consulting, financial services and beauty and wellness.

Ranked providers represent the best fit for most New Jersey businesses, but no single list accounts for every profession, client type or coverage need. Comparing business insurance options side by side and getting quotes directly from carriers gives you the most complete picture before making a final decision.
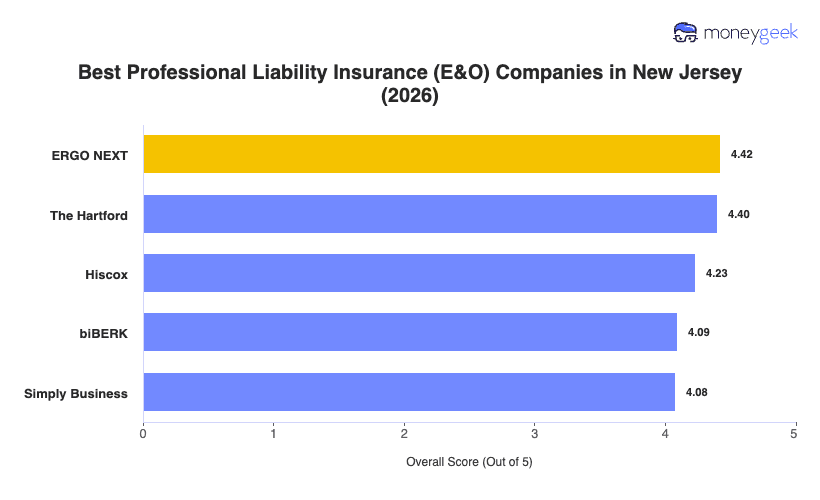
ERGO NEXT4.42$5711
The Hartford4.40$4634
Hiscox4.23$5347
biBERK4.09$5979
Simply Business4.08$5892

How to Get the Best Professional Liability Insurance in New Jersey

Coverage requirements for New Jersey businesses vary by industry, client type and location in ways that make a one-size approach unreliable. A tech consultant in Jersey City managing fintech clients carries a different risk profile and faces different contract demands than a childcare center operator in Trenton or a pharmaceutical consultant in Princeton. These steps walk you through getting professional liability coverage that fits your actual situation.

  1. 1

    Check your NJ licensing board requirements first

    Before buying a policy, confirm whether your profession carries a mandatory professional liability coverage floor set by a New Jersey licensing board. The New Jersey Department of Banking and Insurance maintains a public directory of licensed insurers, and your profession's specific licensing board will publish any mandatory coverage thresholds on its own site.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on who your clients are, what your contracts require and how much a claim could realistically cost your business. Use the tiers below as a starting point for how much professional liability insurance you need.

    • $250,000 to $500,000 per occurrence: Businesses in cleaning, fitness, pet care, beauty and wellness, and nonprofit or creative fields typically fall into this tier, since their work carries lower odds of a costly claim.
    • $500,000 to $1 million per occurrence: Healthcare, consulting, hospitality, and recreation businesses tend to need coverage in this range because their client relationships come with greater financial exposure. This is reinforced by enterprise clients. Companies serving Jersey City's financial district or pharmaceutical firms in the Princeton corridor commonly require $1 million minimums as a condition of doing business.
    • $1 million to $2 million per occurrence: Real estate professionals, tech and IT consultants, educators, design-build contractors, financial advisors, and childcare operators generally need coverage at this level, given the higher potential cost of a claim in these fields. In some cases, the requirement isn't optional. New Jersey physicians, for instance, must carry at least $1 million per claim under State Board of Medical Examiners rules.
  3. 3

    Work with a local agent who knows the NJ market

    New Jersey's business environment varies by region enough that an agent with industry-specific experience in your part of the state can make a real difference in coverage fit. For example, in Jersey City and Newark, financial services firms and tech companies drive a high volume of professional liability purchasing, and agents in those markets know the contract minimums that institutional clients require.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Price is only one dimension of a professional liability policy. When comparing quotes, review each policy's retroactive date, claims-made trigger, defense cost structure (whether defense costs erode the policy limit or are paid in addition to it), deductible per claim and any industry-specific exclusions. For example, a consulting or financial services firm operating out of Jersey City should confirm whether a policy excludes claims arising from securities advice or cryptocurrency-related work, two common exclusions that affect businesses operating in close proximity to Wall Street's client base.

  5. 5

    Research providers beyond price

    Before binding a policy, verify the carrier is licensed to write professional liability insurance in New Jersey through the New Jersey Department of Banking and Insurance's insurer directory. Industry associations with a strong New Jersey presence, including BioNJ for life sciences professionals, the New Jersey State Bar Association for legal professionals and the New Jersey Bankers Association for financial services firms, can point you toward carriers with established track records in the state's specific markets. Claims handling history matters as much as premium, particularly in high-litigation counties where claim frequency runs above the national average.

  6. 6

    Consider bundling with other business coverage

    Bundling professional liability with general liability or a business owner's policy often reduces total premium costs for New Jersey businesses. Most carriers offer discounts of 10% to 15% when policies are combined under one account. For the many small consulting, tech and financial services firms across New Jersey that need both coverage types, bundling through a single carrier also simplifies the certificate of insurance process when clients request proof of multiple coverages.

  7. 7

    Do not let your coverage lapse, and understand tail coverage

    Professional liability policies in New Jersey are almost universally written on a claims-made basis, meaning the policy in force when a claim is filed, not when the underlying work was performed, determines coverage. A gap between policies, even a short one when switching carriers, can leave your business exposed to claims for work completed months or years earlier. If you switch insurers or wind down your practice, purchase prior acts coverage or tail coverage to extend your reporting period and cover claims that arise after your policy ends.

Best New Jersey Professional Liability Insurance (E&O): Bottom Line

ERGO NEXT earns the top rating for professional liability insurance in the state, but your industry, client contract requirements and any coverage floors set by New Jersey licensing boards should drive the final choice. Confirm your profession's requirements through the New Jersey Department of Banking and Insurance and compare quotes from at least three carriers before committing to a policy.

Best Professional Liability Insurance New Jersey Chart
mglogo icon

LOOKING FOR THE BEST INSURANCE FOR OTHER COVERAGE TYPES?

The best NJ small business insurance bundle for you will likely not include only professional liability insurance and will be a mixture of different types. Learn more about the top providers specific to the state and other commonly needed policies below.

Professional Liability Insurance NJ: FAQ

About Connor Bolton


Connor Bolton, Senior SEO and Content Manager (Business & Pet), MoneyGeek

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.

The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.

Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.

Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.


Sources