Cheapest Arizona General Liability Insurance Companies

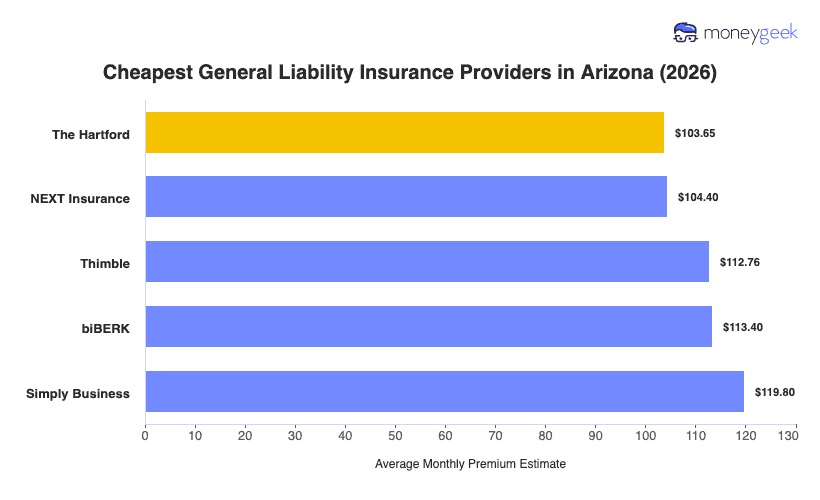
My analysis of 10 major insurers in Arizona and found that across 25 general industries, the four insurers with cheapest general liability insurance for small businesses are:

  • The Hartford: Offers the lowest rates for health care providers and professional service businesses (medical practices, creative professionals, financial services)
  • ERGO NEXT:  Ranks cheapest across trades and customer-facing operations (construction contractors, beauty and wellness, restaurants, retail shops)
  • Thimble: Often provides the most affordable coverage for specialty construction and outdoor service businesses (arborists, excavation, pest control, lawn care, remodeling)
  • biBerk: Cheapest for recreation and wellness businesses (fitness centers, sports facilities, cleaning services)

Treat the providers above as a reference point. It's not a guarantee. To see which insurer offers your business the lowest price, you'll need to compare quotes with the same limits and policy terms. Differences like the work you do, your team size and past claims can all affect the cost of general liability insurance.

The Hartford$104$1,24515%
ERGO NEXT$104$1,25315%
Thimble$113$1,3538%
biBERK$113$1,3617%
Simply Business$120$1,4382%
Coverdash$128$1,536-5%
Progressive Commercial$129$1,552-6%
Nationwide$136$1,631-11%
Hiscox$138$1,659-13%
Chubb$139$1,669-14%

For Arizona, our analysis includes more than 20,000 general liability estimates from 10 major insurers. The dataset covers 408 business types across 25 industries, with businesses ranging from zero to 49 employees. To keep the comparisons consistent, each estimate uses $1 million in coverage per claim and $2 million total for the policy period, with revenue and payroll included in the pricing model.

The statewide rankings focus on average rates for businesses with one to four employees. We keep that employee range the same when comparing industries, while employee-size comparisons look at how rates change as businesses get larger.

These are estimates, not personalized quotes. Your actual premium can differ based on factors such as your business classification, claims history, coverage limits, deductible, revenue or payroll, and endorsements.

Read our full methodology

The Hartford

The Hartford: Cheapest for Health Care and Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford's general liability insurance costs $104 per month, tying with ERGO NEXT for the lowest rate in over half of the business types we analyzed. The Hartford is also the most affordable option for health care providers, creative professionals and businesses offering financial services in Arizona. Its monthly premium is 11% below the state average, saving $19 a month. Pharmacy technicians, firearms instructors and EMTs often see the biggest discounts.

Most often cheapest for these business profiles:

  • General industries: Arts, Media and Entertainment, Education, Financial Services, Health Care and Medical
  • Employee count: Zero to 49 employees

Not a fit? Jump to: ERGO NEXT, Thimble or biBerk

ERGO NEXT

ERGO NEXT: Cheapest for Trades And Customer-Facing Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT ties with The Hartford at an average monthly premium of $104. It's the cheapest option for construction contractors, beauty and wellness services, restaurants and retail shops. It's also the most affordable choice for 181 other business types.

Food service businesses like ice cream shops, pizza restaurants and coffee shops get the biggest savings with ERGO NEXT. Most pay around 15% less than the state average.

Most often cheapest for these business profiles:

  • General industries: Beauty and Wellness Services, Childcare Services, Construction and Contracting, Consulting Services, Food and Beverage, Hospitality and Tourism, Manufacturing, Marketing and Communications, Nonprofit and Associations, Other Professional Services, Pet Care Services, Real Estate and Property Services, Repair and Maintenance, Retail and Product Rental, Tech and IT, Transportation and Logistics

Not a fit? Jump to: The Hartford, Thimble or biBerk

Thimble

Thimble: Cheapest for Specialty Construction and Outdoor Service Businesses

COMPANY HIGHLIGHTS

Thimble is the cheapest general liability insurance company for only 18 business types, but it's the best option for construction specialists like arborists, excavation contractors, pest control and lawn care services. It's also a solid choice for architecture firms, general contractors and roofing contractors, ranking as the second-cheapest carrier. At $113 monthly ($1,353 annually), Thimble runs 4% below the state average.

Most often cheapest for these business profiles:

  • Subindustries: Arborist, Asbestos Contractor, Door and Window Installation, Excavation Contractor, Fire Sprinkler Contractor, Glazier/Glass Contractor, Interior Design, Irrigation Services, Lawn Care Service, Pest Control, Remodeling Contractor, Restoration Contractor, Siding Contractor, Solar Contractor, Tree Service, Brick and Mortar Dog Grooming, Independent Pharmacy, Public School

Not a fit? Jump to: The Hartford, ERGO NEXT or biBerk

biBerk

biBerk: Cheapest for Wellness and Recreation

COMPANY HIGHLIGHTS

biBerk is the most affordable option for just three general industry categories. Fitness centers pay 21% below the state average, followed by cleaning services (19% below), and recreation and sports (18%). It has the second-lowest rates for eight other general industries, including health care, hospitality and pet care services. At $113 monthly ($1,361 annually), most small businesses in Arizona save around 9% with biBerk.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Recreation and Sports

Not a fit? Jump to: The Hartford, ERGO NEXT or Thimble

Is the Cheapest General Liability Insurance Right for Your Arizona Business?

A low-cost policy can work well when your coverage needs are simple. The decision changes if your Arizona business takes on contract work or performs services that some insurers consider higher risk. What matters is whether the policy can keep up with the requirements and day-to-day risks that come with how you operate. In those situations, price is only one part of the decision.

  • Project requirements: If you work in construction or specialty trades, a client may require specific limits, an additional insured endorsement or a certificate before you can start. A cheaper policy only helps if it can meet those requirements without creating delays or extra costs.
  • Outdoor work: Arborists and excavation contractors might find that some carriers limit or exclude certain services. If you're in a similar business, check that the policy covers revenue-generating work before choosing the lowest quote.
  • Customer-heavy businesses: If you run a business where customers regularly come onto your premises, like a fitness center, a low limit might not cover larger injury claims. In that case, the cheapest policy won't be the best fit.
  • Frequent contract changes: Projects require new certificates or policy updates more frequently. Look at how easily the insurer handles those requests because a lower premium loses its value if routine changes are slow or difficult to arrange.

Don't focus on cost alone. The best general liability insurance in Arizona provides real financial protection for your business. If your budget is tight, start with basic limits and fewer add-ons, then increase coverage as your Arizona business grows.

How to Get Cheaper General Liability Insurance in Arizona Without Sacrificing Protection

You can lower what you pay for general liability insurance without reducing financial protection. Make sure insurers price the right type of business and comparable coverage before you change the policy itself.

  • swipe icon

    Compare general liability quotes using the same limits

    When you compare business insurance quotes, use the same coverage limits and deductible with each insurer. Keeping those terms consistent shows you which company actually charges less for the same amount of financial protection.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Your class code tells the insurer what type of work you do and helps determine your rate. If the description doesn’t match your actual services, you might pay a policy that covers risks that don’t apply to your business.

    For Arizona contractors and outdoor-service businesses with several related services, that matters. If your company handles property maintenance, for instance, but doesn’t perform tree removal or excavation, review the business description on your quote and ask the insurer to correct it if it doesn’t match the work you actually do.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    A business working around customers or on commercial job sites often have contracts or leases that require higher liability limits. Those limits can also make more sense when your work is more likely to cause customer injuries or property damage than a remote business with little public contact. You don’t always need the highest limit an insurer offers. The right amount should satisfy general liability requirements while giving you enough coverage for the work you do.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    Look at the full-year cost before deciding how to structure your policy. A higher deductible may lower your premium, but it also means taking on more of the cost when you file a claim. The same tradeoff applies to payment timing. Monthly installments can help with cash flow, while annual payment often reduces fees. Choose the combination that gives you manageable out-of-pocket costs without adding unnecessary expense.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    Bundling is most useful when you need more than general liability in your insurance mix. If you own business equipment or keep inventory at a physical location, a business owner's policy (BOP) may cost less than buying general liability and property coverage separately. Before bundling, though, compare the cost of a BOP with the price of separate policies and make sure you’re not paying for coverage you don’t need.

  • takingNotes icon

    Lower your claim risk in ways Arizona insurers reward

    Safety practices can help insurers see that you’re actively reducing the possibility of a claim. Written procedures and training records can help show that you’re actively reducing the chance of a claim. These examples can get you started:

    • Document safety procedures for outdoor work: If your employees work outside during Arizona’s extreme heat, keep written procedures for hydration and when work should stop because conditions are unsafe.
    • Keep subcontractor insurance records: When you hire subcontractors, verify their insurance and keep current certificates on file so you know whether their coverage is still active.
    • Inspect customer and work areas regularly: Check areas where customers or visitors could be injured, such as walkways or job sites. Record of hazards you found and what you did to correct them.
    • Maintain equipment used around customers: If your work involves ladders or power tools, document routine inspections and repairs so problems are caught before they lead to a claim.

Affordable General Liability Insurance in Arizona: Bottom Line

The Hartford, ERGO NEXT, Thimble and biBerk are among Arizona’s cheapest general liability insurers, but my statewide analysis only shows where you can begin your search. The type of work you do, your team size and your claims history can change which insurer is cheapest for you. After that, look at whether the policy meets your contract requirements and gives you enough protection for the work you actually do.

Cheapest General Liability Insurance in Arizona Chart

Cheap General Liability Insurance in Arizona: Next Steps

If you want your actual cheapest rate, get quotes from multiple insurers using identical limits. Our analysis of Arizona providers gives you a starting point, but your business might see different pricing. Compare apples-to-apples quotes to find your true low-cost option.

Have more questions about business insurance in Arizona? Check out our additional resources on coverage options and requirements for Arizona businesses.

shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

You'll need more than general liability coverage in your policy mix, so getting more affordable rates becomes important to help manage your overall costs. See which providers have the cheapest premiums for other policy types:

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com