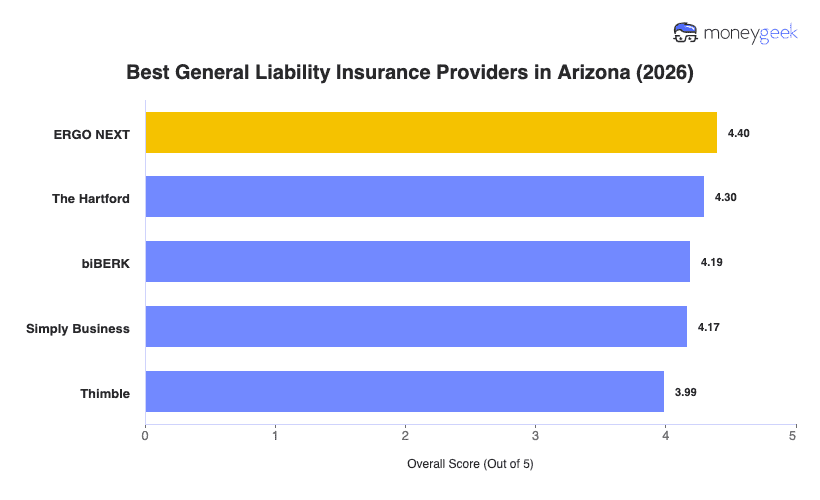
Best General Liability Insurance Companies in Arizona

I determined the best general liability companies in Arizona by looking how insurers capture your business' actual operations, so they're more likely giving quotes and policies that match your work. Another consideration was if insurers provide guidance for preventing GL claims. I then compared average rates across 25 general industries, including professional and technical firms and construction companies.

My top picks are:

  • Choose if you provide hands-on services: ERGO NEXT
  • Choose if affordability is a priority: The Hartford
  • Choose if you're in health and fitness: biBerk
  • Choose if you're in retail or food: Simply Business
  • Choose if you do project-based work: Thimble

For our Arizona general liability insurance ratings, we analyzed pricing, coverage options, and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of Arizona's small businesses, while weighting results to ensure broader industry and location representation across Phoenix, Tucson and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 2,000 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Arizona businesses consistently across different industries and regions. We then rated each company across affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology, and pricing analysis specific to Arizona, see our full methodology.

95%

% of Small Businesses Covered

Over 1 million

Business Profiles Studied

2,231

Customer Experiences Analyzed

ERGO NEXT

ERGO NEXT: Best Overall, Best for Hands-on Service Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT ranks first overall with a 15% savings against the state benchmark. It’s the most affordable for food and beverage businesses, hospitality and repair operations. The digital-first platform approves most applications instantly. Its coverage ranks eighth. The $300,000 sublimit for damage to rented premises sits below what many competitors offer, and the platform doesn't bundle professional liability or liquor liability add-ons. If your leased space exceeds $300K in value, purchase additional policies separately.

Learn More: ERGO NEXT Review

The Hartford

The Hartford: Best Cheap General Liability Insurance

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks second overall for Arizona general liability, with the lowest rates among reviewed insurers. Businesses pay 15% less than the state average, and savings run deeper by industry: education businesses save 32%, health care operations save 26% and financial services save 23%. A local Arizona agent handles policy customization.

Coverage includes a $1 million sublimit for rented premises damage, with liquor liability and professional liability available as bundle add-ons. The one drawback is the quote process, which requires an agent appointment rather than an instant online option.

Learn More: The Hartford Business Insurance Review

biBerk

biBerk: Best for Business in Health and Fitness

COMPANY HIGHLIGHTS

biBerk ranks third overall for Arizona general liability, saving businesses 7% against the state average. A Berkshire Hathaway subsidiary, biBerk works best for hands-on service industries: fitness operations save 21%, cleaning businesses save 19% and recreation companies save 18%. Most applications get approved within 24 hours through its online platform, no agent appointment needed.

Policy servicing is where biBerk trails the top two. Certificates of insurance take days rather than minutes, and the endorsement menu has no liquor liability option, which rules out restaurants and bars from the start.

Learn More: biBerk Review

Simply Business

Simply Business: Best for Small Retail and Food Businesses

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business is an insurance marketplace that connects Arizona businesses with carriers like Travelers, Hiscox and AmTrust. It ranks second for customer experience during the quote process but fifth for affordability, with 2% savings against the state average.

Coverage options vary by the carrier that underwrites your policy.

Learn More: Simply Business Review

Thimble

Thimble: Best for Project-Based Trades

COMPANY HIGHLIGHTS

Thimble ranks fifth overall with coverage you activate using a mobile app. Affordability ranks third, giving you 8% savings, but especially for construction ($267 monthly) and manufacturing ($56 monthly).

Thimble’s pay-as-you-go model emphasizes simple terms. Exclusions include liquor liability, and there aren't many endorsement options.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for Arizona Businesses

Cost isn't the only factor that determined the best general liability insurer for an Arizona business. While it's important to make sure a carrier has rates that won't disrupt your cash flow, you also need to consider if its service keeps up with compressed schedules and its has GL limit options that fit your. Extreme summer heat can reshape construction calendars, while Flagstaff tourism businesses may see demand rise when Valley residents head north.

How to Choose the Best General Liability Insurance in Arizona

To get the general liability insurance that fits your Arizona business, you need to start with how your business operates and understanding the requirements you need to meet. The best policy also goes beyond cost, so use our guide to make sure you cover all angles before deciding.

  1. 1
    Optimize your payment and coverage structure

    Your work setting and contractual obligations determine the general liability requirements you must satisfy. Beyond this, you also need to consider what payment structure works best for your business.

    Ask yourself:

    • Would paying annually preserve money over the full policy term, or would monthly installments better support your cash flow? Compare the total amount you would pay under both arrangements.
    • Do you operate from one location or move between customer properties and project sites? Tell insurers everywhere you work so they can confirm that the policy covers those settings.
    • Do your contracts or leases specify minimum limits or require additional insureds? Treat those terms as minimum requirements rather than optional features.

    A common starting point for Arizona businesses is a $1 million per-occurrence limit (the most the policy pays for one covered incident), and a $2 million aggregate limit (the most it pays for covered claims during the policy term). If you bid on larger commercial projects, you’ll likely  need more protection if their contracts set higher limits.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority

    Think about what would create the biggest problem for your business if an insurer performed poorly. Your answer tells you what you should prioritize.

    • Affordability should lead your decision if your revenue changes throughout the year. Look beyond the opening premium and consider whether you could manage the price through both busy and slower periods.
    • Customer experience deserves more weight when your work depends on prompt insurance documents or policy updates. If you’re a contractor or in events, this might matter more to you.
    • Coverage options become the priority when you expect your operations to change. If you intend to pursue larger contracts or adding services, you’ll need a policy that can adjust with it without moving to another insurer.
  3. 3
    Shortlist two to three providers

    First, eliminate insurers that don’t cover your type of work. A provider might serve small businesses generally but decline operations performed on construction sites, inside customers’ homes or at temporary events. Then, check whether each provider serves businesses of your size and operates where you work in Arizona. Lastly, pare your list down to two or three insurers that meet those basic conditions. Price comparisons, which we’ll do later, won’t help if a carrier can’t insure your regular activities.

  4. 4
    Double-check for dealbreakers before investing more time

    Review the details that could prevent an otherwise promising insurer from working for your business:

    • Read the exclusions to make sure the policy doesn’t remove coverage for a service or activity that contributes to your revenue.
    • Verify that the insurer offers every limit and endorsement required by your current contracts. Missing one requirement could prevent you from accepting the work.
    • Ask how long policy changes and proof-of-coverage requests usually take. The provider’s timeline should support your clients’ deadlines, especially when projects take place within shorter seasonal or heat-adjusted schedules.
    • Check how the insurer accepts claims and provides follow-up. A reporting process that doesn’t work with your schedule can make an already difficult situation harder to manage.
  5. 5
    Compare your finalists using the same three lenses

    Now compare each provider using the same questions. Give your main priority the most influence, but don’t ignore weaknesses in the other areas.

    • Affordability: Which insurer offers the best long-term value once you include policy fees and possible renewal changes? Check whether the payment schedule changes what you pay overall.
    • Customer experience: Which provider gave clear answers and realistic time frames? Its performance before the sale can show how easy it may be to request help later.
    • Coverage options: Which policy can support the next realistic change in your operations? Focus on adjustments you’ll realistically need instead of counting every available feature.
  6. 6
    Use quotes as the final confirmation step

    Request quotes from your finalists using the same business details and coverage limits. Compare business insurance quotes to confirm that each one includes the protection your business requires. If one costs considerably less, find out what caused the difference. Genuine savings come from a better price, not lower limits or a missing endorsement.

Best Small Business General Liability Insurance in Arizona: Bottom Line

ERGO NEXT, The Hartford and biBerk rank highest for Arizona general liability. The right insurer still depends on your industry and location. For example, a Mesa landscaping company has different exposures than a Flagstaff retail shop or a Chandler cleaning service.

Map your actual risks first, then weigh whether price stability, service speed or coverage flexibility matters more for how you operate.

Best General Liability Insurance for Small Business in Arizona Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

General liability is an important part of the best small business insurance in Arizona since it's the coverage most businesses get first. But for comprehensive financial protection, you'll need other coverage types in your mix. I've put together resources that show our recommended providers for other policies you might need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com