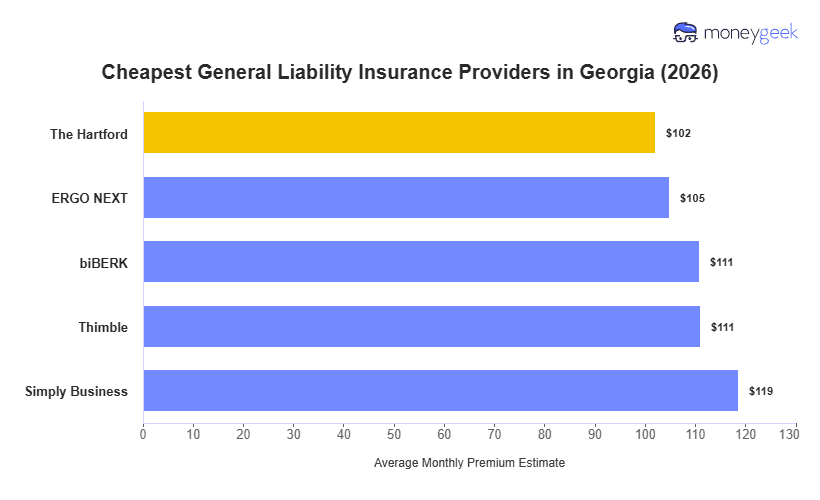
Cheapest Georgia General Liability Insurance Companies

After analyzing top insurers in Georgia, we found these three carriers offer the cheapest general liability insurance across different business types in the state.

  • The Hartford: Best for creative professionals and retail operations (photography services, graphic design, auto parts shops, clothing stores)
  • ERGO NEXT: Best for hands-on service businesses and food establishments (barber shops, electrical contractors, food trucks, restaurants)
  • biBerk: Best for wellness services and cleaning operations (massage therapy, yoga studios, carpet cleaning, janitorial services)

Your general liability insurance premium depends on factors like your business activities, annual revenue and location within Georgia. These three providers offer a reliable starting point for your quote comparisons.

The Hartford$102$1,22516%
ERGO NEXT$105$1,25913%
biBERK$111$1,3298%
Thimble$111$1,3328%
Simply Business$119$1,4232%
Coverdash$126$1,511-4%
Progressive Commercial$129$1,548-7%
Hiscox$134$1,614-11%
Nationwide$135$1,618-11%
Chubb$138$1,655-14%

For Georgia, we compared general liability pricing from 10 major insurers using more than 20,000 standardized estimates. The dataset covers 408 business types across 25 industries and includes businesses with zero to 49 employees. Each estimate reflects a $1 million per occurrence/$2 million aggregate policy, with modeled revenue and payroll built into the pricing.

To rank the cheapest insurers overall, we averaged rates for businesses with one to four employees across industries. Industry-level recommendations use that same one-to-four-employee range so differences reflect business type rather than company size. For employee-size comparisons, we aggregate rates across industries to show how pricing changes as businesses grow.

These figures are estimates, not personalized quotes. Your actual general liability premium in Georgia can change based on your business classification, revenue or payroll, claims history, coverage limits, deductibles and endorsements. Compare quotes using the same coverage terms to get a fair price comparison.

Read our full methodology.

The Hartford

The Hartford: Cheapest for Creative and Retail Businesses

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks as the cheapest general liability insurer across the widest range of Georgia businesses, coming out lowest-cost for 110 out of 408 business types analyzed (27%). It's most often cheapest for creative professionals and retail operations, with small businesses paying an average of $102 per month for basic coverage. That's 19% below Georgia's average and saving around $226 annually compared to typical rates.

Most often cheapest for these business profiles:

  • General industries: Arts, Media and Entertainment, Education, Financial Services, Healthcare and Medical, Retail and Product Rental
  • Employee count: One to 49 employees

Not a fit? Jump to: NEXT or biBerk

ERGO NEXT

ERGO NEXT: Cheapest for Service Businesses and Food Operations

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT leads Georgia's general liability market for affordability, offering the lowest rates for 41% of business types in our study (168 out of 408). Food establishments and hands-on service businesses see the greatest savings, with small operations paying around $105 per month for standard coverage. That's $192 less per year than Georgia's typical rates, or about 14% below average.

Most often cheapest for these business profiles:

  • General industries: Childcare Services, Consulting Services, Food and Beverage, Hospitality, Travel and Tourism, Manufacturing, Marketing and Communications, Other Professional Services, Real Estate and Property Services, Repair and Maintenance, Tech/IT, Transportation and Logistics

Not a fit? Jump to: The Hartford or biBerk

biBerk

biBerk: Cheapest for Wellness and Cleaning Businesses

COMPANY HIGHLIGHTS

Small wellness and cleaning businesses find the lowest general liability rates with biBerk across Georgia. The insurer comes out cheapest for 75 different business types (18% of industries analyzed), with monthly premiums averaging $111 for businesses with one to four employees. That puts biBerk about 10% under the state average, cutting annual costs by roughly $123. It's also the cheapest provider for solo operators, with an average monthly rate of $56.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Pet Care Services, Recreation and Sports
  • Employee count: Solo operators

Not a fit? Jump to: The Hartford or NEXT

Is the Cheapest General Liability Insurance Right for Your Georgia Business?

Bare-bones coverage works fine until something goes wrong. A low premium saves money each month, but it won't help much when a client demands proof of higher limits or a claim eats through your deductible faster than you expected.

Price matters, but so does whether your policy actually protects your business. These factors matter most:

  • Contract requirements set your minimum coverage: Landing commercial work in metro Atlanta or managing properties anywhere in Georgia often means meeting specific insurance thresholds before you start. Buy too little now, and you'll pay more to upgrade when opportunities arrive.
  • Claims hit harder in growing markets: Georgia's business-friendly environment attracts competition, which means tighter margins. A $2,500 deductible after someone gets hurt at your location or alleges your work caused damage can strain cash reserves that most small operations need for payroll and inventory.
  • Your risks change as your business grows: A food truck working festivals in north Georgia carries different liability concerns than a brick-and-mortar restaurant in downtown Savannah. As you add employees, equipment or locations, your coverage should scale with those changes.
  • Summer weather doesn't wait for cheap insurers: Georgia's severe thunderstorm season brings property damage claims that need fast processing. The insurer with the lowest premium might also have the slowest claims department. You could end up covering repair costs out of pocket while it reviews paperwork.

Start with coverage that satisfies current client contracts and handles realistic claim scenarios. Expand your limits as revenue and risk increase to find the best general liability insurance company for your business.

How to Get Cheaper General Liability Insurance in Georgia Without Sacrificing Protection

Smart shopping and active risk management can lower your premium without cutting essential coverage. Focus on accurate quotes, proper business classification and safety practices that Georgia insurers actually reward at renewal.

  • swipe icon

    Compare general liability quotes using the same limits

    Request and compare business insurance quotes using the same policy limits, deductibles and coverage features from each insurer. A Marietta landscaping company asking one insurer for $1 million coverage with a $1,000 deductible and another for $2 million with a $2,500 deductible won't know which insurer actually charges less for equivalent coverage. Keep your general liability quote requests identical so you're comparing real pricing differences, not different coverage packages.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Insurers assign premiums based on industry classification codes, and small errors add up. A landscaping company in Gwinnett County classified as “tree service” or "arborist" pays more than one coded as "lawn maintenance," even when the business only handles mowing and trimming. Tree work involves climbing and heavy equipment, which drives higher premiums. Check that your agent uses the code that accurately reflects your actual operations.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    Most Georgia general liability policies start at $1 million per occurrence with $2 million aggregate coverage. Metro Atlanta commercial property managers and state agency contracts often have general liability requirements with these amounts as minimums before you can start work. Meet those thresholds and cover your realistic liability exposure, but paying for $5 million in coverage when your contracts cap at $2 million and your business has limited assets wastes premium dollars.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    A higher deductible lowers your premium, but Georgia businesses need to consider their revenue patterns before choosing this route. An established Savannah tour company with strong spring and summer cash flow can absorb a $5,000 deductible if a claim happens during peak season. A new food truck in Athens operating on thin margins or a Jekyll Island beach rental business that only makes money May through September might struggle to cover even $2,500 without disrupting operations. Choose a deductible your business can afford when claims happen.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    Many Georgia small businesses need both general liability and property coverage for their leased space or owned buildings. A business owner's policy combines both, and the cost of a BOP usually runs less than buying each policy separately. But only bundle if you actually need both coverage types and the package price saves money. Don't add property insurance just because it's included with general liability if you work from client locations or your home.

  • takingNotes icon

    Lower your claim risk in ways Georgia insurers reward

    Insurers reduce premiums for businesses that demonstrate active risk management. What counts varies by industry, but these practices signal lower liability exposure across Georgia operations:

    • Written safety protocols for winter weather (salting schedules, entrance mat placement, ice melt procedures for November through March when Georgia gets freezing temperatures)
    • Employee training documentation for high-risk work (proper lifting techniques for warehouse operations, safe food handling procedures for restaurants, customer service protocols during peak retail seasons)
    • Regular facility maintenance logs that address Georgia's climate (HVAC inspections before humid summers, plumbing checks before winter freezes, roof drainage checks before spring storm season)
    • Customer contract templates with liability waivers that comply with Georgia law and clearly define scope of work for each service call
    • Certificate of insurance tracking for subcontractors if you hire other businesses to complete portions of your work, which is common in Georgia's construction and event planning industries

    You don't need expensive consulting. Consistent documentation shows insurers you're managing the risks they price into your premium.

Affordable General Liability Insurance in Georgia: Bottom Line

There's rarely one cheapest insurer for every Georgia business since rates shift based on your industry, business size and whether you operate in metro Atlanta, coastal Savannah or rural counties. The lowest price only makes sense when the policy covers your actual liability exposure and meets the requirements set by your contracts, clients or Georgia commercial landlords. It helps to use the provider comparisons and industry guides on this page to narrow your options, then request quotes with identical policy terms to see who charges less for your profile. 

The goal isn't the absolute cheapest premium. It's getting the lowest cost that still protects your business and satisfies the coverage standards your work requires.

If you're ready to get quotes: Get matched

Cheapest General Liability Insurance in Georgia Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

The more complex your coverage needs become, the more policies you need in your insurance mix. Having comprehensive financial protection can quickly become expensive, so knowing which providers offer the cheapest rates on average can help you keep insurance costs manageable. I've provided you with resources to show our provider recommendations.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com