Cheapest Colorado General Liability Insurance Companies

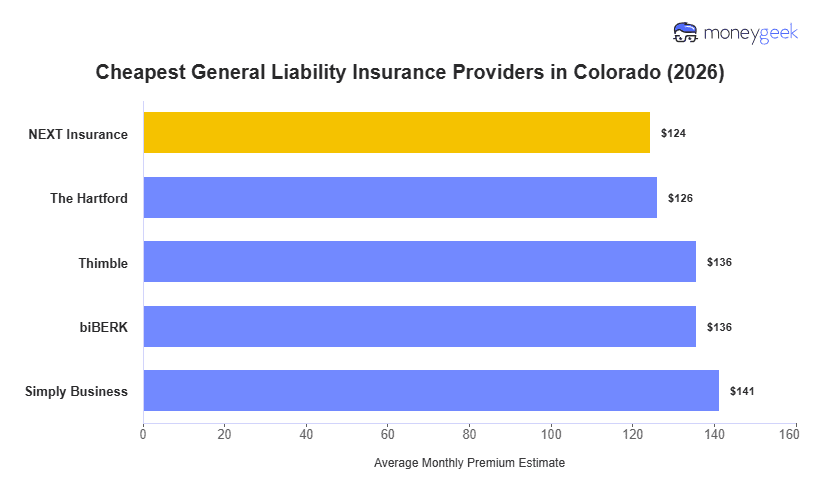
My analysis of quotes from major insurance carriers across over 400 business types in Colorado and found these four providers offer the most affordable general liability rates for small businesses:

  • ERGO NEXT: Ranks cheapest across trades and customer-facing operations (construction contractors, beauty and wellness, restaurants and bars, retail shops)
  • The Hartford: Offers the lowest rates for health care providers and professional service businesses (medical practices, creative professionals, financial services)
  • Thimble: Often provides the most affordable coverage for specialty construction and outdoor service businesses (arborists, excavation, pest control, lawn care)
  • biBerk: Cheapest for recreation and wellness businesses (fitness centers, sports facilities)

Two Colorado craft breweries can get very different quotes even with the same coverage limits. One may have more annual revenue or a larger staff, while the other may have a cleaner claims history. Those differences change general liability insurance rates, so use my findings as a starting point, not a prediction. Then compare equivalent quotes to see which insurer is cheapest for your business.

ERGO NEXT$124$1,49315%
The Hartford$126$1,51314%
Thimble$136$1,6287%
biBERK$136$1,6297%
Simply Business$141$1,6943%
Coverdash$152$1,821-4%
Progressive Commercial$153$1,839-5%
Hiscox$164$1,969-12%
Nationwide$164$1,972-12%
Chubb$166$1,994-14%

For Colorado, we start with how the rankings are built. Statewide results use average pricing for businesses with one to four employees, while industry recommendations keep that same employee range so the comparison stays consistent. Separate size-based comparisons look at how pricing shifts as employee count changes.

The underlying data includes more than 20,000 standardized estimates from 10 major insurers, covering 408 business types across 25 industries and businesses with zero to 49 employees. Each estimate assumes $1 million per claim and $2 million total policy limits, with modeled revenue and payroll factored into pricing.

These figures are estimates, not personalized quotes. Your actual premium may differ based on your business classification, claims history, deductible, coverage limits, endorsements and revenue or payroll.

Read our full methodology

ERGO NEXT

ERGO NEXT: Cheapest for Trades and Customer-Facing Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT is the cheapest option for more Colorado business types than any other provider, according to MoneyGeek's analysis. Most businesses pay about $124 a month, 16% below the state average. Construction contractors, beauty salons, restaurants, retail shops and repair services get the largest savings. If your business falls into one of these categories, ERGO NEXT is worth getting a quote from first.

Most often cheapest for these business profiles:

  • General industries: Agriculture and Natural Resources, Beauty, Body and Wellness Services, Childcare Services, Construction and Contracting, Food and Beverage, Hospitality, Travel and Tourism, Manufacturing, Marketing and Communications, Nonprofit and Associations, Other Professional Services, Pet Care Services, Real Estate and Property Services, Repair and Maintenance, Retail and Product Rental, Tech/IT, Transportation and Logistics
  • Employee count: One to four employees

Not a fit? Jump to: The Hartford or Thimble or biBerk

The Hartford

The Hartford: Cheapest for Health Care Providers and Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

With a monthly premium of $126, The Hartford's general liability coverage runs about 10% below Colorado's average for most small businesses. Medical practices, financial advisors, consultants, creative professionals and educators see even stronger savings, with premiums 30% to 40% below the state average.

Most often cheapest for these business profiles:

  • General industries: Arts, Media and Entertainment, Consulting Services, Education, Financial Services, Health Care and Medical
  • Employee counts: Five to 49 employees

Not a fit? Jump to: ERGO NEXT or Thimble or biBerk

Thimble

Thimble: Cheapest for Specialty Construction and Outdoor Services

COMPANY HIGHLIGHTS

Thimble offers the lowest rates for 16 business types in our Colorado study, and all of them fall under construction and outdoor services. Specialty contractors get the most savings: pest control, flooring installation, welding, electrical work and lawn care businesses pay 28% to 38% less than Colorado's average rates. Most small businesses outside this niche pay 3% less than the state average, at $136 per month.

Most often cheapest for these business profiles:

  • Subindustries: Artisan Contractor, Carpentry, Concrete Contractor, Electrical Contractor, Flooring Installation, Glazier/Glass Contractor, HVAC Contractor, Interior Design, Lawn Care Service, Pest Control, Restoration Contractor, Roofing Contractor, Sandblasting Contractor, Snow Removal Service, Tile Contractor, Welding Contractor/Shop

Not a fit? Jump to: ERGO NEXT or The Hartford or biBerk

biBerk

biBerk: Cheapest for Recreation and Wellness Businesses

COMPANY HIGHLIGHTS

At $136 monthly ($1,629 annually), only three general industries have biBerk as their cheapest general liability provider: cleaning services, fitness centers and recreation facilities. This provider is among the three most affordable options for 10 more. With rates 18% to 21% lower than Colorado's average, cleaning companies, gyms, yoga studios, sports leagues and recreation venues enjoy the most savings.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Recreation & Sports
  • Employee count: Sole proprietors

Not a fit? Jump to: ERGO NEXT or The Hartford or Thimble

Is the Cheapest General Liability Insurance Right for Your Colorado Business?

Before treating the lowest quote as the best deal, look at what you’re getting for that price. A cheaper policy may work if it already meets your coverage needs. But if you need higher limits or frequent policy updates, the lowest-priced option might not be the best option. Consider these situations:

  • Minimum coverage for commercial leases: Your lease may require specific liability limits or additional insured coverage if you rent storefront or office space. A cheap policy is only useful if it meets those terms without pushing the final cost much higher.
  • Flexibility for seasonal businesses: If your Colorado business gets busier during ski season or summer tourism, your insurance needs shift with your operations. A low-cost policy becomes less attractive it's difficult to change your coverage or get certificates.
  • Premises protection for customer-facing businesses: Slip-and-fall or property-damage claims are more likely for businesses that have customers coming to their locations regularly than a business that works remotely. In these cases, the lowest available limits might not be enough.
  • Service speed for contract work: A slightly higher-priced insurer may be a better fit if it handles those requests reliably. Slow policy changes can hold up work if jobs require updated certificates or endorsements before you can start.

If your coverage needs are simple and the policy fits the work you do, you can give price more weight. Once contracts or day-to-day operations create more insurance demands, the best general liability insurers for your business may not be the ones with the lowest premium.

How to Get Cheaper General Liability Insurance in Colorado

A good way to avoid giving up important protection just to get a lower general liability rate is to first figure out how much coverage your business actually needs. Then look for ways to lower the cost without cutting that protection.

  • swipe icon

    Compare general liability quotes using the same limits

    Price comparisons only work when the policies are similar. Keep your liability limits and deductible consistent when you compare business insurance quotes. Otherwise, the cheaper quote just gives you less financial protection. Pay attention to what each quote includes as well. If an insurer has added coverage you didn’t request, separate that cost before deciding which provider is genuinely more affordable.

  • loanReview icon

    Confirm your business classification (class code) is correct

    Insurers assign your business a class code based on the type of work you do, and that classification helps determine your rate. If the description doesn’t match your actual operations, you may be paying for risks that aren’t part of your business. Read your quote carefully to make sure the business description matches your work. If it doesn’t, ask the insurer to correct it before accepting the price.

  • signupBonus icon

    Only pay for the general liability limits you need

    Your limits should reflect what your business needs, not the highest amount available. A lease or client contract may set a minimum, so check those documents before reducing coverage.

    If there aren’t any other general liability requirements, consider how your business operates. If you regularly work on customer property, such as residential remodeling or landscaping jobs, higher limits may make more sense than they would for a Colorado business that operates remotely with little public contact. The goal is enough coverage for your exposure without automatically paying for a higher limit.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    A higher deductible lowers your premium because you agree to pay more yourself if you have a covered claim. That only helps, however, if you can comfortably afford the deductible when something happens. If you run a construction company, which has higher risks, raising it just to get a cheaper rate could leave you with a larger bill after a claim.

    How you pay can affect the total cost too. Monthly installments are easier to manage, while an annual payment reduces fees. Compare the yearly totals to see whether the savings are worth the bigger upfront payment.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    If you need several business policies, check what happens to the total price when you buy them from the same insurer. Some carriers offer multipolicy savings even when each coverage stays separate. A business owner's policy (BOP) is another bundling option if you need commercial property coverage on top of GL. 

    Don’t assume either approach automatically saves money. Compare the cost of a BOP with separate policies and look at any multipolicy discount available for the coverages you already need.

  • takingNotes icon

    Lower your claim risk in ways Colorado insurers reward

    The best safety practices are the ones that address the risks in your day-to-day operations. In Colorado, that could mean paying closer attention to weather and outdoor working conditions when they affect your business. I suggest starting with these:

    • Stay ahead of snow and ice around customer areas: If people visit your location, keep entrances and walkways clear during winter weather. Use a consistent process for checking and treating slippery areas before someone gets hurt.
    • Reduce wildfire hazards around your property: Businesses in wildfire-prone areas can remove combustible material near buildings and keep surrounding areas maintained so a fire has less fuel to spread.
    • Adjust outdoor work for elevation: If your crews work at higher elevations, account for the conditions rather than treating the job like one at lower altitude. Give workers time to adjust and make sure supervisors know when someone should stop working.
    • Set clear safety rules for recreational activities: If customers take part in outdoor activities, explain the rules before they begin and make sure your staff applies them consistently.

Affordable General Liability Insurance in Colorado: Bottom Line

ERGO NEXT, The Hartford and Thimble are among Colorado’s cheapest general liability insurers, but that doesn’t mean one of them will always be cheapest for you. The price a provider quotes you can change based on the work you do and the size of your business. A lower rate is only useful if the policy still gives you the coverage you need and meets any insurance requirements tied to your work.

Cheapest General Liability Insurance in Colorado Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

Use these resources to see which providers have the cheapest business insurance for Colorado small businesses when you're looking for other policy types. The savings become more important once you add more coverages in your mix.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com