Cheapest Connecticut General Liability Insurance Companies

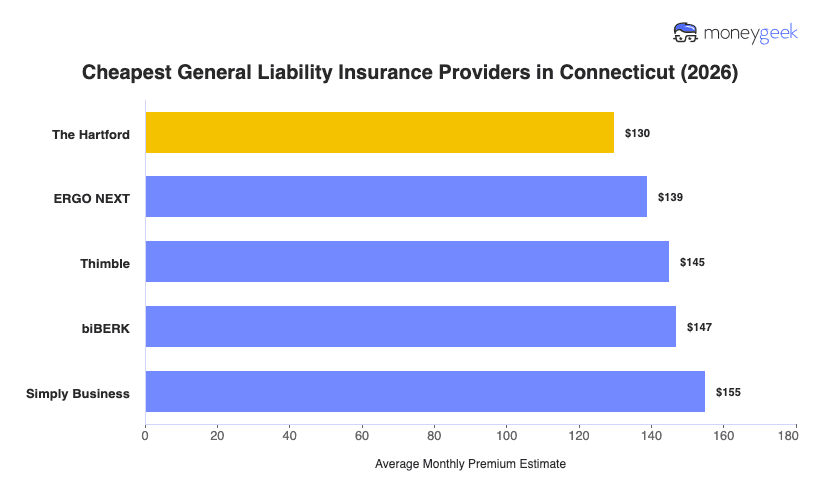
Based on my analysis, the cheapest general liability insurance providers across over 400 business types in Connecticut are:

  • The Hartford: Lowest rates for health care providers, professional services, creative businesses, tech companies and restaurants (medical practices, consulting firms, photography studios, web development, full-service dining)
  • ERGO NEXT: Cheapest across construction trades, agriculture operations, personal services, food vendors and transportation (electrical contractors, plant nurseries, beauty salons, food trucks, towing services)
  • Thimble: Most affordable coverage for general contractors, specialty trades, outdoor services and property maintenance (carpentry, masonry, lawn care, handyman services)
  • biBerk: Cheapest for cleaning operations, fitness businesses, medical specialists, hospitality and repair shops (janitorial services, gyms, urgent care clinics, hotels, auto repair)

The cheapest insurer in my analysis won’t necessarily give every business the lowest quote. Your general liability insurance costs can change based on what you do and your claims record, even among businesses in the same industry. My analysis is good for narrowing your options, but getting quotes with the same coverage terms shows which insurers are genuinely cheaper.

The Hartford$130$1,55818%
ERGO NEXT$139$1,66613%
Thimble$145$1,7419%
biBERK$147$1,7637%
Simply Business$155$1,8602%
Coverdash$168$2,019-6%
Progressive Commercial$169$2,027-6%
Hiscox$176$2,113-11%
Nationwide$179$2,150-13%
Chubb$180$2,160-13%

Our Connecticut analysis draws on more than 20,000 standardized estimates from 10 major insurers. The dataset covers 408 business types across 25 industries and businesses with zero to 49 employees. Each estimate assumes $1 million per claim and $2 million total policy limits, with modeled revenue and payroll included in the pricing.

For the statewide rankings, we average rates for businesses with one to four employees. Industry recommendations use that same employee range, while separate comparisons show how pricing changes as businesses grow. These are estimates rather than personalized quotes, so your actual premium can still differ based on your classification, claims history, deductible, endorsements and coverage amount. 

Read our full methodology.

The Hartford

The Hartford: Cheapest for Health Care Providers and Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks cheapest across the widest range of Connecticut businesses, leading in 32% of all businesses analyzed. Health care providers, professional services, creative businesses, tech companies and restaurants get the biggest savings, though businesses outside these industries still save around 15% compared to the state average. At $130 per month, you save $29 that can go toward other business priorities.

Most often cheapest for these business profiles:

  • General industries: Arts, Media & Entertainment, Education, Financial Services, Health Care and Medical, Marketing and Communications, Nonprofit and Associations, Retail and Product Rental, Tech/IT
  • Employee count: Zero to 49 employees

Not a fit? Jump to: ERGO NEXT or Thimble or biBerk

ERGO NEXT

ERGO NEXT: Cheapest for Construction Trades and Agriculture

On ERGO NEXT's site
COMPANY HIGHLIGHTS

Construction contractors, farmers and food service operators find ERGO NEXT beats competitors more often than any other provider in Connecticut. It ranks first across 140 business types, from electrical work and plant nurseries to food trucks and towing services. Tour operators save 40% below market rates, while cabinet makers and food truck owners cut costs by 39%. Businesses pay an average of $139 monthly, about $20 less than competitors charge for identical coverage.

Most often cheapest for these business profiles:

  • General industries: Agriculture and Natural Resources, Childcare Services, Consulting Services, Food and Beverage, Hospitality, Travel and Tourism, Manufacturing, Other Professional Services, Repair and Maintenance, Transportation and Logistics, Wholesale and Distribution

Not a fit? Jump to: The Hartford or Thimble or biBerk

Thimble

Thimble: Cheapest for Specialty Construction and Property Services

COMPANY HIGHLIGHTS

Connecticut contractors working on ladders, roofs and clients' properties get the best rates from Thimble. The insurer specializes in construction trades: handymen save $108 monthly, tree services save $118, and general contractors save $193 on general liability costs. 23 construction specialties rank Thimble cheapest, from carpentry and masonry to pest control and waterproofing. Monthly costs run $145 for small operations.

Most often cheapest for these business profiles:

  • General industry: Construction and Contracting

Not a fit? Jump to: The Hartford or ERGO NEXT or biBerk

biBerk

biBerk: Cheapest for Cleaning and Fitness Operations

COMPANY HIGHLIGHTS

Our analysis found biBerk dominates service businesses where physical premises create the most liability exposure. Cleaning companies pay $111 monthly with biBerk, below Connecticut's $138 average, a $28 monthly savings that adds up fast for businesses operating on thin margins. The pattern holds across 82 specialties: fitness studios, pet care services and real estate professionals all see double-digit monthly savings. 

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Pet Care Services, Real Estate & Property Services, Recreation & Sports
  • Employee count: Solo operators

Not a fit? Jump to: The Hartford or ERGO NEXT or Thimble

Is the Cheapest General Liability Insurance Right for Your Connecticut Business?

A low quote stops being cheap once you increase the limits or encounter an insurer that charges for policy changes your business actually needs. Before you focus on the premium, check whether the policy already fits the way you work. That matters more for Connecticut businesses with leases, client contracts or services that insurers may treat differently.

  • Your lease may set the coverage floor: If you rent a storefront, office or clinic, the landlord may require certain liability limits or ask to be added to your policy. A cheaper option loses its advantage if meeting those terms raises the final price.
  • Contract work can add insurance requirements: Commercial clients may ask for proof of coverage before you can start work. If you regularly need certificates or policy changes, make sure the insurer can handle them without delays or unexpected fees.
  • Some business activities may be harder to insure: Connecticut businesses such as towing companies or food vendors may perform work that not every insurer treats the same way. A low premium does little for you if part of your regular work is excluded.
  • Customer traffic can change how much protection makes sense: If people regularly visit your business, an injury on the premises is more likely than it would be for a home-based operation. In that case, the cheapest available limits may leave you with less protection than you’re comfortable carrying.

If the lowest-priced policy already covers your work and meets the requirements tied to your business, price can carry more weight in your decision. When you need more flexibility from the policy or insurer, the best general liability providers for you may not be the ones with the lowest initial quote.

How to Get Cheaper General Liability Insurance in Connecticut

Connecticut's tight business margins, whether you're running a Norwalk marketing agency or a New Britain machine shop, make every dollar count. These strategies cut your general liability costs without leaving gaps in coverage when you need it most.

  • swipe icon

    Compare general liability quotes using the same limits

    Most Connecticut business owners request quotes slightly differently from each insurer: one gets $1 million per occurrence, another $2 million aggregate, a third includes add-ons. If you do this, you can't identify the cheapest option, even if you compare business insurance quotes side-by-side.

    Our rankings show The Hartford cheapest statewide, but a Stamford consulting firm might pay less with ERGO NEXT depending on revenue and location. The only way to know is identical quote parameters across all carriers: same limits, same deductibles, same policy terms.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Classification codes exist because a Hartford insurance brokerage doesn't carry the same risks as a Waterbury metal fabricator. If your policy's business description doesn't match what you do, you either overpay for coverage you don't need or risk claim denials for work you perform.

    Check your current policy's business description to see if it matches what you do. If it doesn't, call your insurer immediately.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    Higher limits cost more, and not every Connecticut operation needs $2 million in coverage. A Fairfield County financial planner working from a home office carries minimal slip-and-fall liability and minimal property damage risk, so $500,000 limits create enough cushion. A New Haven construction firm might need $2 million because client contracts require it.

    Check what your general liability requirements from clients, vendors and landlord before choosing limits. If no one mandates higher coverage, choose lower limits and put the savings toward other business needs.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    Raising your deductible from $500 to $2,500 cuts premiums, but only makes sense if you have cash to cover claims. A Bridgeport landscaping company with $15,000 in reserves can absorb a $2,500 hit and pocket the monthly savings, while a startup Hartford tech firm running lean needs that same cash for payroll. The premium reduction means nothing if a claim wipes out your operating funds mid-quarter.

    Connecticut insurers discount upfront payments 5% to 8%. Pay annually if your cash flow can handle it, since your bank balance matters more than the discount.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    Bundling general liability with other coverages often cuts your total premium. A Greenwich retail shop bundling general liability and property into a business owner's policy (BOP) saves money compared to buying each separately. A Danbury IT consultant bundling general liability with cyber coverage and professional liability gets the same discount.

    Ask insurers for the cost of a BOP, as well as separate quotes for each coverage. Compare the totals. If bundling saves money, take it. Just confirm you need all the coverage types in the bundle first.

  • Loading...

    Lower your claim risk in ways Connecticut insurers reward

    Connecticut's environment creates claim exposures that insurers price into your premiums, so reducing those risks cuts your rates. Document your risk management efforts and share them during renewal to get credit:

    • Maintain documented snow and ice removal schedules: Connecticut's winter, from December to March, creates slip-and-fall liability. Businesses that log removal times and surface treatments reduce premises claims during peak hazard months.
    • Install updated electrical and HVAC systems: Older buildings in Hartford, New Haven, and Bridgeport carry a higher fire risk. Document system upgrades and regular maintenance inspections to lower property damage liability.
    • Implement cybersecurity protocols for client data: Connecticut's insurance and financial services concentration exposes clients to data breaches. Businesses with documented encryption, access controls and employee training reduce professional liability claims.
    • Use participant liability waivers for recreation businesses: Gyms, fitness studios, sports facilities and outdoor instructors that use legally reviewed waivers reduce their injury claim exposure.

Affordable General Liability Insurance in Connecticut: Bottom Line

No single insurer offers the lowest rates across Connecticut's diverse business market. A Stamford financial advisor, a Waterbury machine shop and a Mystic charter boat operator each carry different liability exposures, and your cheapest option depends on how insurers price your specific industry, size and location.

Use our rankings to see which insurers offer the most savings in your industry, then request quotes with identical limits from your top three options. This method shows you which insurer actually offers the lowest premium for your business and helps you avoid overpaying for coverage.

If you're ready to get quotes: Get matched

Cheapest General Liability Insurance in Connecticut Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

We've analyzed the cheapest providers for other coverage types so you have reasonable starting points when start building your insurance mix. You can use the resource I've provided below.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com