


Choose where to jump to next based on your needs:
Average General Liability Insurance Cost in Maryland (2026 Report)
General liability insurance in Maryland typically costs $30 to $444 per month, with your industry and employee count having the greatest impact on where your premium falls within that range.
If you're ready for a quote, get matched to the right general liability carrier for your Maryland business with our tool below.
Select state
Updated: September 8, 2026
Advertising & Editorial Disclosure
How Much Does General Liability Insurance Cost in Maryland?
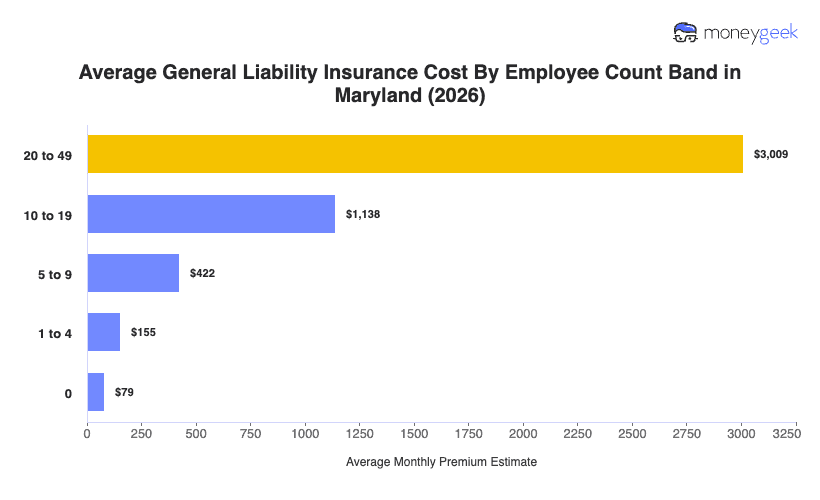
Maryland small businesses with one to four employees pay an average of $155 a month, or $1,859 a year, for general liability insurance. That benchmark is 26% above the national average, putting Maryland 44th for affordability.
Actual premiums vary by industry classification, revenue, coverage limits and claims history. A quote near the Maryland average signals standard exposure for a small operation, while a meaningful gap in either direction means one factor is pulling the number. The breakdowns below show how costs shift by industry and business size within the state.
To estimate average general liability insurance costs in Maryland, we analyzed quote data from 10 major U.S. small business insurance providers and modeled over 20,000 standardized premium estimates across 25 general industry categories and five employee count bands (zero through 20 to 49). All estimates assume a standard $1 million per occurrence/$2 million aggregate policy. We incorporated modeled average revenue and payroll across all combinations of Maryland regions, industry and employee counts using CBP, QCEW and Economic Census/SUSB data, calibrated against private compensation databases and IRS SOI totals.
The Maryland state average reflects the modeled premium for a standardized one-to-four-employee small business across all industries. Segment averages isolate for employee count and general industry category so readers can compare how premiums shift across business types within Maryland. These are benchmarks for market orientation, not personalized quotes. Read full methodology.
What Factors Affect General Liability Insurance Costs in Maryland?
General liability premiums in Maryland reflect a combination of universal pricing drivers that apply in every state and local conditions specific to Maryland's legal, geographic and economic environment.
Maryland Agnostic General Liability Insurance Cost Factors
These two factors produce the widest premium variation for Maryland businesses regardless of location.
 Business size
Sole proprietors pay around 49% below the Maryland state average, while businesses with 20 to 49 employees pay an average of 1,842% above it. More staff means more customer interactions, more job sites and more exposure to claims. Plan for a substantial cost increase each time you cross into a new employee band.
 Industry classification
Construction and contracting businesses pay 187% above the Maryland average, reflecting high injury risk and severe claim potential. Tech and IT firms pay the least at 80% below average, because office-based work limits physical exposure. A landscaping company and a web developer will receive fundamentally different quotes even with identical revenue and employee counts, because the physical nature of the work drives the underwriting assessment.
Maryland-Specific General Liability Insurance Cost Factors
Beyond universal pricing drivers, Maryland's legal framework, geography and economic mix create conditions that push premiums higher than most neighboring states.

Maryland's Contributory Negligence Doctrine
Maryland is one of only four states where any fault by the injured party bars recovery entirely. That all-or-nothing rule produces unpredictable litigation outcomes. Insurers price in the possibility that businesses will face aggressive claims even when the claimant shares fault for the incident.

Maryland's Urban Concentration and Legal Climate
The Baltimore-Washington corridor generates high foot traffic and frequent customer interactions, which raises claim frequency. Baltimore City and Prince George's County rank among the most plaintiff-favorable venues in the country, with juries that tend toward higher settlements. Insurers price that elevated severity into premiums for businesses in these areas.

Maryland's Regulatory and Contractual Coverage Mandates
State law requires home improvement contractors to carry at least $500,000 in general liability coverage. Federal and government contracts are common in Maryland's $42 billion procurement economy and frequently require $1,000,000 or more in limits. Businesses pursuing public-sector work face higher baseline premiums as a result.

Maryland's Seasonal Slip-and-Fall Exposure
Maryland's humid climate and variable seasons create year-round hazards, including ice, wet leaves and storm debris. Slip-and-fall claims are one of the most common general liability loss types, and retail, hospitality and service businesses with customer-facing operations see the highest concentration of them.

Maryland's Chesapeake Bay Storm and Flooding Exposure
Coastal and tidewater businesses face hurricanes, nor'easters and tidal flooding that can damage customer property or create hazardous conditions. Insurers price in this geographic exposure for operations near the Bay or in flood-prone areas of the Eastern Shore.

Maryland's Tourism and Hospitality Traffic
Baltimore's Inner Harbor, Annapolis, Ocean City and other destinations draw heavy visitor volume, raising customer interaction and injury exposure for restaurants, hotels and retail businesses. Higher foot traffic correlates with more frequent claims, and insurers price that into general liability premiums for these sectors.
Get a MD General Liability Insurance Cost Estimate
Based on the industry you work in and your employee count, we can estimate your costs using the general liability insurance calculator below. All estimates are for a standard $1 million per occurrence and $2 million aggregate policy. You can also click Get Quotes to be matched to your insurer fit based on what you enter for estimates.
Maryland General Liability Cost Estimate Calculator
Select your state and industry to view average business insurance premiums in your area. Rates are calculated based on a business with 5 employees and $500,000 in annual revenue.
Select General Industry
Select Employee Count
Monthly rate estimate—
Select General Industry
Monthly rate estimate—
Select Employee Count
How to Lower General Liability Insurance Costs Without Sacrificing Coverage
Maryland businesses do not need to reduce protection to pay less for general liability insurance. Several strategies can lower premiums at purchase, at renewal or over multiple policy cycles without creating coverage gaps.
Maryland does not currently have a dedicated cheapest general liability insurance page, but the approaches below can help you find more affordable coverage in the state.
Quick General Liability Cost Lowering Methods
These immediate actions can reduce what you pay for general liability coverage in Maryland starting with your next quote or renewal.
 Provide clean, accurate underwriting information
Insurers price policies based on revenue, employee count, operations and claims history. A Bethesda IT consultant who misreports annual billings or a Columbia fitness studio that omits personal training services may face mid-term premium adjustments. Gather current financials, payroll records and a clear scope of operations before requesting quotes so underwriters assess your actual risk rather than making worst-case assumptions.
 Compare multiple insurers
Requesting general liability quotes from several carriers reveals how differently insurers price the same risk. A Frederick landscaping company might see quotes range from $320 to $480 per month depending on each carrier's appetite for outdoor labor exposure. Review policy terms carefully when comparing business insurance quotes, since pricing gaps sometimes reflect exclusions that could leave key services uncovered.
- Bundle general liability into a business owner's policy (BOP)
A business owner's policy combines general liability with commercial property coverage at a lower combined rate than buying each separately. An Annapolis gift shop owner with retail inventory and storefront fixtures could save 10% to 15% by bundling. Compare the cost of a BOP against standalone policies to confirm the discount applies to your situation.
 Pay annually instead of monthly
Most insurers apply a financing markup to monthly payment plans. Switching to an annual payment removes that fee and often includes a small discount, saving 5% to 10% compared to monthly billing. Maryland businesses with predictable cash flow and the ability to cover the full annual premium at policy inception benefit the most from this approach.
 Increase your deductible (if you can afford it)
Raising your deductible lowers your premium by shifting more upfront cost to you when you file a general liability claim. A Rockville accounting firm with steady cash flow and no recent claims might benefit from a $2,500 deductible. Avoid this approach if an unexpected payout would strain a seasonal operation like an Ocean City rental business during the off-season.
 Adjust your coverage limits
Premiums scale with limits. If your contract requirements allow it, lowering limits can reduce costs. However, make sure your limits match your actual client expectations and exposure before reducing them, since underinsuring creates a bigger financial risk than the premium savings.
Read More: How Much General Liability Insurance Do You Need?
Long-Term General Liability Cost Lowering Methods
These strategies take more than one policy period to affect rates but produce durable savings over time.
General Liability Insurance Cost in Maryland: Bottom Line
Maryland's general liability market blends government contracting, professional services, retail corridors and tourism into a single statewide average that masks significant variation underneath. Three questions pinpoint what drives your rate:
- Where does my industry fall in the pricing distribution? Desk-based professional services cluster 60% to 80% below the state average, while physical labor and high-interaction sectors like construction and healthcare exceed it. A quote outside your industry's typical range raises a useful question about what is driving the gap.
- How do Maryland-specific factors shape my baseline? Contributory negligence rules, plaintiff-favorable courts in Baltimore and Prince George's County, government contract mandates and seasonal weather exposure all push Maryland premiums above most neighboring states. These conditions affect some businesses more than others depending on location and client base.
- Which factors in my quote can I actually control? Industry and employee count are fixed. Claims history, deductible choices, payment structure, documentation accuracy and coverage limits are not. Focusing on the controllable drivers is where Maryland businesses find the most room to manage costs.
Understanding which of these drivers applies to your operation matters more than matching the statewide benchmark of $155 per month.
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com
Sources
- Maryland Court of Appeals. "Coleman v. Soccer Association of Columbia, No. 9, September Term 2012." Accessed September 23, 2026.
- Maryland General Assembly. "Business Regulation Article, §8-302.1: Contractor General Liability Insurance Requirement." Accessed September 23, 2026.
- Maryland Office of the Comptroller. "State of the Economy Report." Accessed September 23, 2026.
- Maryland Legislature. "Title 5, §207: Unlawful Acts and Conduct." Accessed September 23, 2026.
- Maryland Legislature. "Title 14, §752: Six Years." Accessed September 23, 2026.