


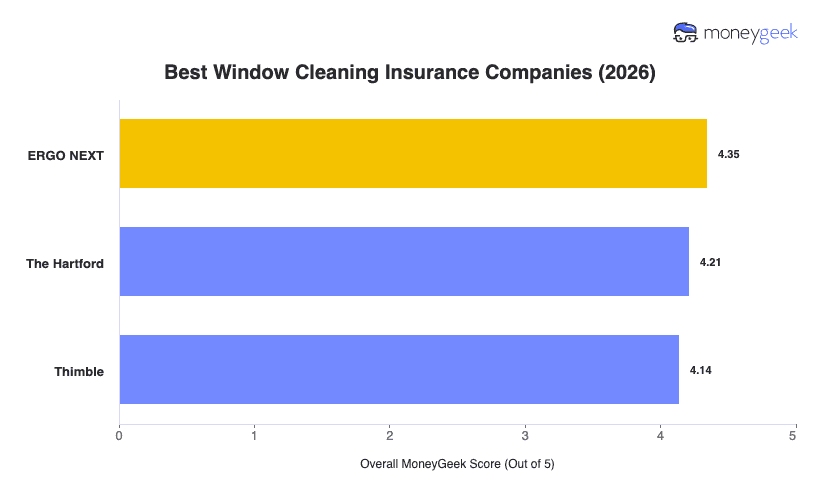
My analysis found that for window cleaners, the three best business insurance providers are:
Best Window Cleaning Insurance
ERGO NEXT, Thimble and biBerk are the best business insurance companies for window cleaning crews in my analysis.
MoneyGeek helps you compare the best window cleaning carriers, coverage types and costs, so you can find the protection you need.
Ready to shop? Use our tool below to get matched with your top provider and start your contractor insurance quote.
Select state
Updated: October 2, 2026
Advertising & Editorial Disclosure
Best Business Insurance Companies For Window Cleaners
Window cleaners work on other people’s property, often with ladders, lifts or employees exposed to falls. A broken pane can create a claim, while a larger job may come with insurance requirements of its own. I built the ranking around price first, then looked at how well each insurer handles the day-to-day needs of a growing window cleaning business.
I used AI to support parts of the research, but I made the final editorial decisions on provider fit and ranking.
- Affordability (50%): Price carries the most weight in my ranking. I used the same window cleaning profile for every insurer, then considered whether higher premiums came with benefits that could justify the difference, such as better service or easier policy management.
- Customer Experience (30%): A window cleaner may need a COI before stepping onto a property or an additional insured added for a new contract. I gave more credit to insurers that make those tasks easy and give you a clear path to help when self-service isn’t enough.
- Coverage Options (20%): A basic setup may work while you’re cleaning windows on your own. Hiring a crew, adding a work vehicle or moving into jobs with tougher insurance requirements can change that quickly. I looked for insurers that give you room to add protection as the business changes.
See our full methodology.

ERGO NEXT: Best for Straightforward Coverage Needs and Same-Day Coverage
pros
Fewer decisions for straightforward coverage needs
Strong COI tools for client requests
Easy online policy updates
cons
Higher pricing for solo owner-operators
Limits may not suit high-rise work
COMPANY HIGHLIGHTS
ERGO NEXT is my top choice for small operators cleaning homes and low-rise storefronts who mostly need standard liability coverage and show clients proof of insurance. ERGO NEXT’s preset packages and online buying process let you handle a simple setup without spending much time configuring the policy. It’s also the cheapest insurer in my analysis, saving you about $248 per year compared with the industry average, which you could put toward equipment upkeep or other day-to-day costs. I’d also consider ERGO NEXT if you work for multiple property managers or storefront clients that regularly request customized COIs. Its app lets you issue and update certificates on the go, while the COI Analyzer can use a client’s sample certificate to help match their requirements.
Learn More: ERGO NEXT Business Insurance Review

Thimble: Best for Seasonal Work and Flexible Coverage Terms
pros
Flexible terms for uneven work schedules
Easy COI and additional insured handling
Monthly GL can pause for true work breaks
cons
Some coverages only come with annual terms
Liability limits may not meet larger contracts
COMPANY HIGHLIGHTS
If you mostly clean residential windows where snow and freezing temperatures can stop outdoor jobs for part of the winter, I’d recommend Thimble. You can buy coverage for a single job or keep it for a full year, so the policy term can follow how often you’re actually working. If you choose Thimble Monthly for general liability, you can pause coverage once for up to 30 days and restart it early if work picks back up. You won’t be covered for new jobs during the pause, so it's more suited for periods when you know you're really not working new contracts than a slower-than-usual month.
Learn More: Thimble Business Insurance Review

biBerk: Best for More Established Cleaning Crews and Support from Licensed Agents
pros
Direct buying for owners who know their needs
Licensed expert help when you want it
Up to 20% savings through direct sales
cons
No broker comparison across multiple insurers
Specialty window cleaning work don't qualify for some coverages
COMPANY HIGHLIGHTS
If you’ve built a steady book of clients and already have a good handle on the coverage you need, I’d consider biBerk. It sells directly to small businesses without a broker in the middle, so an experienced owner can move through the quote and purchase process online without waiting for someone else to shop the policy. That said, biBerk still gives you access to licensed insurance experts if you have a question or if you want help checking whether a policy fits before you buy. That hybrid setup works well if you’re comfortable handling most of the process yourself but don’t want to give up human support completely.
Learn More: biBerk Business Insurance Review
What Types of Insurance Do Window Cleaners Need?
For most window cleaners, general liability should be the first policy in your insurance mix. Since you spend each job working directly on someone else’s property, it covers you if you crack a pane or leave water where a customer slips. The gear you use, however, needs a different kind of financial protection. Theft is one of the biggest risks for mobile equipment, so tools and equipment insurance is another core coverage because your gear travels with you and can be costly to replace if it disappears from a vehicle or jobsite.
Beyond these, add coverages based on how your run your business.
Pays for third-party injuries or property damage tied to your work. That could mean cracking an expensive pane or a customer slipping near your work area. | Start here, even if you work alone. Clients may also require GL before letting you onto a property. | You spend most jobs working directly on someone else’s property, so a small mistake can become your financial responsibility. GL gives you a first line of protection against those everyday customer-facing claims. | |
Tools & Equipment | Covers portable business equipment if a covered event damages or steals it. That includes gear like water-fed systems and poles. | Once replacing your gear out of pocket would hurt. | Window-cleaning equipment gets expensive quickly. A XERO residential water-fed kit sells for about $3,198, before you account for every piece of gear you may own. |
Janitorial Bond | Protects your customer if you or an employee steals money or property while working on their premises. Unlike liability insurance, the bond protects the client. | When a customer requires bonding or gives you unsupervised property access. | Small businesses aren’t immune to employee dishonesty. ACFE found check and payment tampering in 23% of occupational-fraud cases involving organizations with fewer than 100 employees. |
Covers vehicles used for the business, including liability when you cause a crash while driving between jobs. Physical damage coverage can protect the vehicle itself if added. | Use it when the business owns a vehicle. Also review your coverage if you regularly use a personal vehicle for work. | Window cleaners often rely on pickups or vans to move between jobs with their equipment. In 2024, 8,953 pickups and 1,831 vans were involved in fatal crashes, according to NHTSA. | |
Pays benefits for employee injuries or illnesses caused by work, including medical care and part of lost wages. | Once you hire, though employee thresholds vary by state. | Falls make this especially relevant for window-cleaning crews. OSHA’s accident database showed 19 window washing incidents from 2020 through 2024, including fatal falls from elevation. | |
Pollution Liability | Covers certain pollution-related claims that standard GL may exclude, such as cleanup costs or damage tied to chemicals released during your work. | Consider it if your cleaning methods create meaningful chemical runoff or disposal exposure. | Cleaning products can enter the environment during normal rinsing, and EPA notes that some ingredients can harm aquatic life or affect water quality. |
How Much Does Window Cleaning Insurance Cost?
Window cleaning business insurance costs an average of $97 per month, or $1,165 per year, across five common coverage types. Individually, policies cost from $13 per month for tools and equipment insurance to $223 for pollution liability. Your final rates could change depending on whether you use extension ladders or lifts. Client type is also another factor. Cleaning storefront window usually lead to higher rates than if you mostly deal with residential clients.
How much you spend on coverage in total depends on the policies your insurance mix. On average, estimates are:
- General liability: $81 per month or $969 per year
- Tools and equipment: $13 per month or $156 per year
- Janitorial bond: $19 per month or $228 per year
- Commercial auto: $199 per month or $2,391 per year
- Workers' comp: $102 per month or $1,220 per year
- Pollution liability: $223 per month or $2,676 per year
- Commercial property: $21 per month or $258 per year
- Cyber insurance: $82 per month or $985 per year
What Are These Costs Based On?
These figures give you a practical budgeting baseline for a small window cleaning business, not a guaranteed quote. Our main averages use businesses with one to four employees across all 50 states and Washington, D.C., with the following assumptions:
- General liability: $1 million per occurrence / $2 million aggregate
- Workers’ comp and commercial auto: State minimum requirements
- Commercial property: Based on insured property value
- Cyber insurance: $1 million limit
Our main dataset doesn’t include tools and equipment, janitorial bonds or pollution liability, so I used published small-business pricing from outside sources for those three coverages.
What you actually pay depends on the work you take on. A cleaner handling ground-level storefronts presents a different risk than a crew working from ladders or lifts. Hiring employees, carrying more expensive gear or moving into larger commercial jobs can also raise your insurance costs.
Use the business insurance calculator to get an estimate based on your crew size and the kind of window cleaning jobs you take on. If you want to see what an insurer would charge, click Get Quote and we’ll match you with one for a personalized quote.
Window Cleaning Insurance Cost Calculator
Select Coverage Type
Select State
Select Employee Cand
Select Vehicle Type
Average Monthly Cost—
Select Coverage Type
Average Monthly Cost—
Select State
Select Employee Cand
Select Vehicle Type
How To Buy The Best Window Cleaning Insurance
Don't think of buying window cleaning insurance gets as a one-and-done purchase. It's better to you work through the decisions in order, so I’ve mapped out the steps to make it easier. You can also use the downloadable buying checklist alongside this guide as you shop for the best window cleaning insurance for your business.
- 1
Start with coverage you’re required to carry
Before you shop, separate the insurance you must have from coverage you may want later. Check your state’s workers’ comp rules as soon as you hire, and plan on commercial auto if the business owns a vehicle. Then read any client contract before choosing a policy. Commercial property managers may require general liability with specific limits, while some also ask for a janitorial bond.
If a client gives you an insurance requirements sheet or vendor packet, use it while you shop. Once the policy is in place, you’ll usually prove coverage with a certificate of insurance (COI), and some clients may also ask to be added as an additional insured. Building those requirements in upfront helps you avoid buying a policy that still doesn’t qualify you for the job.
Read More: Business Insurance Requirements
- 2
Add Coverage for Risks Your Required Policies Don’t Handle
Once you’ve handled the insurance you’re required to carry, look at what you’d still have to pay for yourself. Tools and equipment coverage can protect the gear that moves with you from job to job, especially higher-value items like water-fed systems. If that equipment gets stolen or damaged, you’re dealing with the replacement cost and potentially a day you can’t work.
Coverage like pollution liability is more situational. I’d consider it if you use cleaning chemicals that could run off worksites or require cleanup after an accidental release. The more your jobs involve stronger solutions or sensitive surrounding property, the more important that protection becomes.
- 3
Choose Limits and Deductibles Based on What You Could Actually Lose
Start with any limit your client requires, then treat that as the floor. For general liability, think about the size of a realistic claim and how much of it you could afford to absorb. Use the same logic for property you own. Add up what it would cost to replace your insured equipment, then choose a tools and equipment limit that gets reasonably close to that value. For the deductible, pick an amount you could pay without scrambling for cash after a claim. Higher deductibles can lower your premium, but you’ll have to cover more of the cost yourself when you file a claim.
Read More: How Much Business Insurance Do I Need?
- 4
Look Beyond Price When You Choose an Insurer
The cheapest insurer won’t help much if it doesn’t fit the way you work. Using subcontractors or taking on specialty cleaning work can change how a carrier views your risk and may limit which insurers will quote you.
Then look at what happens after you buy. If clients regularly ask for COIs or policy changes, strong self-service tools can save you time between jobs. I’d also check who handles claims and what kind of support you can expect when you need help. Some owners prefer to manage most things online, while others may want a licensed expert they can call before making a coverage decision.
- 5
Compare Quotes on Equal Terms
Once you have a few options, compare business insurance quotes using the same limits and deductibles. Make sure each insurer is covering the same type of window cleaning work, so a lower price isn’t simply coming from thinner protection. If one quote still costs more after you line everything up, then you can decide whether the extra cost buys something genuinely useful.
- 6
Read the Policy Before You Buy
Read past the coverage names and limits before you pay. For window cleaners, I’d check whether general liability still protects you if you damage the glass or frame you’re working on, and whether a problem that shows up after you leave can fall under completed-operations coverage. For tools and equipment, check your policy covers theft from a locked vehicle and if it requires signs of forced entry.
If you buy pollution liability, look closely at what the policy considers a pollutant and which cleanup costs it will shoulder. The goal is to catch restrictions that could leave you paying out of pocket for a claim you thought the policy covered.
- 7
Review Your Coverage When the Business Changes
When you hiring a crew or take on higher-risk jobs, it may increase the financial protection you need. That warrants a review of your policies. I’d also reassess coverage if you stop offering certain services or your equipment value changes. This way, you can confirm you're not paying for protection that you don't need anymore or carrying too little for the work you still do.
Window Cleaning Insurance: FAQ
You might have other questions about window cleaning insurance beyond what I've covered, so I gathered commonly asked questions to provide you with more information.
Window cleaning insurance is a group of policies that protect your business from risks tied to the work you do. Depending on the coverage you buy, it can help if you damage a customer’s glass or if someone gets hurt because of your work. It can also respond to other losses tied to your equipment or business operations.
Yes, you may still need it even without employees. A solo window cleaner can still damage customer property or cause injury to someone near the work area. Some commercial clients also require proof of insurance before they let you start a job.
Document the condition of the glass before you start, especially on expensive or specialty windows. A few clear photos can help show whether damage was already there if the customer later blames your work. If they file a claim, your insurer can review the evidence and decide whether the policy applies.
Not automatically. Adding services can change how an insurer classifies your business, and your current policy may not cover the new work the same way. Tell your insurer before you expand what you offer so you can confirm whether you need to adjust the policy.
Often, yes. Your policy may not automatically cover independent subcontractors, and some clients may require every contractor on the job to carry insurance. Ask for a certificate of insurance before work begins and make sure your own policy allows for subcontracted work.
Contact your insurer as soon as possible and follow its claims process. Keep any photos or job records that help explain what happened, along with the customer’s complaint. Avoid promising payment or accepting responsibility before the insurer reviews the claim.
Best Window Cleaning Insurance: Bottom Line
The best window cleaning insurance should match the way you work now and give you room to adjust when that changes. Start with the coverage you’re required to carry, then fill the gaps based on your actual risks. Use client requirements as your floor for limits, but don’t stop there if a realistic loss could cost more than you could comfortably absorb. Before you buy, check the policy for exclusions or conditions that could matter on a real job.
Among the providers I reviewed, ERGO NEXT fits straightforward coverage needs and fast self-service, while Thimble gives seasonal operators more flexibility around policy terms. biBerk suits established crews that want to buy direct but still have access to licensed support. Compare quotes on the same terms, then revisit your coverage whenever the business changes in either direction.
Get Window Cleaning Business Insurance Quotes
Use our quote tool to see what insurers may fit your window cleaning business. Once you have a few options, compare what each one actually offers before you focus on price.
About Connor Bolton

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.
The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.
Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.
Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.
Sources
- Association of Certified Fraud Examiners (ACFE). "Occupational Fraud 2024: A Report to the Nations." Accessed October 11, 2026.
- National Highway Traffic Safety Administration (NHTSA). "Vehicles Involved in Fatal Crashes by Vehicle Type." Accessed October 11, 2026.
- Occupational Safety and Health Administration (OSHA). "Accident Search Results — Window Washer." Accessed October 11, 2026.
- WindowCleaner.com. "XERO Ultimate Residential Kit." Accessed October 11, 2026.