

I recommend these three providers for the best business insurers for welders and welding shops:
Best Welding Contractor Insurance
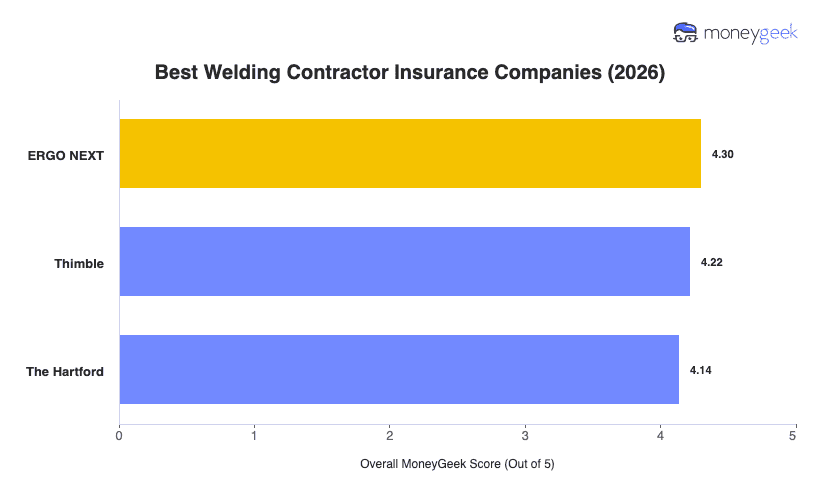
The best business insurance companies for welding contractors and shops are ERGO NEXT, Thimble and biBerk.
MoneyGeek helps you compare the best welding contractor providers, coverage types and costs, so you can find the protection you need.
Ready to shop? With our matching tool below, you can get connected with your top provider and start your welding contractor insurance quote.
Select state
Safe & SecureVerified and VettedTrusted Brands
Updated: October 8, 2026
Advertising & Editorial Disclosure
Best Business Insurance Companies For Welding Contractors
Welding businesses look very different from one another, and that changes what they'd value in an insurer. A mobile welder often most about fast proof of insurance and straightforward liability coverage. A fabrication shop may need broader protection for employees, vehicles, equipment and ongoing operations. My methodology accounts for those differences instead of treating every welding business as if it has the same insurance needs.
- Affordability (50%): Price carries the most weight in the score. I compare insurers using the same welding contractor profile and assumptions so differences in premium come from the provider, not from changes in the business being modeled.
- Customer Experience (30%): Insurance often becomes a practical issue when work is already moving. I give more credit to providers that make it easier to issue COIs, update policies or get help when a claim affects an active job.
- Coverage Options (20%): Basic liability may be enough for a simpler operation, but needs can expand as the business changes. I look at whether the insurer can support things like employees, commercial vehicles, higher-value equipment or more complex welding work.
I used AI to support parts of the research, but I made the final calls on which providers fit welding contractors best.
See our full methodology.

ERGO NEXT: Best for Lower-Risk Welding Work and COIs with Specific Wording Requirements
pros
40% savings for 10–19 welder shops
Fast online quoting and buying
Unlimited customized COIs at no extra cost
cons
$30,000 tools and equipment limit
Stricter fit for businesses with recent claims
COMPANY HIGHLIGHTS
If you do light fabrication or nonstructural repair work, I’d recommend ERGO NEXT. It only takes around 10 minutes to quote and buy coverage online, and you can manage core policies like general liability and tools and equipment from the same account. Its COI setup is useful when commercial clients have specific requirements. ERGO NEXT's proprietary COI Analyzer works from a sample certificate to identify the client's requirements and help generate a COI that matches them, and you can request unlimited customized COIs without spending anything extra.
ERGO NEXT also has the lowest average rate in my analysis. Its rates are around 20% below the industry average, resulting to about $561 in annual savings. You could use that amount to offset part of what you spend on consumables such as welding wire and shielding gas over the year.
Learn More: ERGO NEXT Business Insurance Review

Thimble: Best for Per-Project Coverage and Fluctuating Work Schedules
pros
Flexible coverage terms that match changing workloads
Monthly GL can be paused for 30 days
Instant COIs with unlimited certificates
Strong savings for 20 to 49 employee shops
cons
Business equipment coverage tops out at $5,000
GL caps at $2 million per occurrence
COMPANY HIGHLIGHTS
Thimble is my top choice if your welding work comes in bursts instead of staying steady all year. Say you mainly handle custom railings and repair jobs during the warmer construction months, then have very little field work once winter slows local projects. Thimble lets you buy general liability coverage by the job, month or year, so you can choose a term that better matches when you’re actually working.
It also fits welders whose schedule changes unexpectedly. If a large fabrication project ends and your next contract doesn't start for several weeks, Thimble Monthly lets you pause the policy once for up to 30 days. You can resume it sooner if work comes back, or you can let the pause period run its course and coverage restarts automatically once the 30 days are up. New work isn't covered when you pause your policy, so this works best for a period of genuine downtime rather than a slower month with occasional jobs.
Learn More: Thimble Business Insurance Review

biBerk: biBerk Best for More Established Welding Shops and Hands-On Support During Buying and Claims
COMPANY HIGHLIGHTS
biBERK makes the most sense for a more established welding shop with several moving parts to insure. Picture a fabrication business with employees in the shop, a company truck making deliveries and higher-value equipment that stays in use year-round. biBERK can support that setup with general liability, workers’ comp, commercial auto and a BOP, while tools and equipment protection can be added by endorsement. That gives a growing shop more room to keep several core needs with one insurer.
Its direct-to-business model is another reason to consider this provider. If you already have a good handle on what coverage you need and don't want to buy through a broker who shops among carriers, you deal directly with biBERK. You can do this online or with one of its licensed insurance experts. biBERK says cutting out that middleman can reduce premiums by up to 20%
Learn More: biBerk Business Insurance Review
What Types of Insurance Do Welding Contractors Need?
Welding contractors carry risks not only when they're working, but even after they're done. A spark could damage a customer's property during a job, or a failed weld could cause damage after the work is complete. General liability responds to both timelines through property damage liability and products-completed operations coverage. Tools and equipment insurance protects a different part of the business. Theft is one of the biggest risks contractors face when gear moves between jobs or stays in a work vehicle, and the policy helps pay to replace stolen welding equipment.
Third-party injuries and property damage tied to your business. For a welder, that could mean a customer getting hurt near your work area or sparks damaging property during a job. | Before taking on client or commercial jobs. | Welding puts heat, sparks and heavy equipment close to property you don’t own. If something gets damaged or someone gets hurt around your work area, GL can help cover the resulting claim. | |
Tools and Equipment | Portable equipment while it travels or sits away from your main location. This can include welding machines and other gear you bring between jobsites. | Once your welding gear starts traveling with you. | Replacing even one major tool can get expensive. A Lincoln Weld-Pak 140 MIG welder currently sells for about $631, before you account for the rest of your setup. |
Injuries and property damage from accidents involving a business-owned vehicle, such as the pickup or van you use to haul welding equipment. | A pickup or van is part of the business. | If you’re driving between jobs with welding gear in the back, road risk becomes part of the business too. In 2024, 4,034 pickup occupants died in crashes, with 54% of those deaths occurring in single-vehicle crashes. | |
Medical care and part of lost wages when an employee gets hurt or sick because of work, including injuries from welding or material handling. | Your first hire can trigger the need. | Once someone else is doing hands-on work for you, an injury can affect both that employee and the business. Construction recorded 167,100 workplace injuries and illnesses in 2024. | |
Business property kept at your shop, including welding equipment and materials damaged by a covered event. | When you move into a dedicated shop. | A shop puts much of what keeps your business running under one roof. U.S. nonresidential building fires caused about $3.47 billion in property losses in 2024, which shows how large a single property event can become. | |
Installation Floater | Materials or fabricated components while they’re being transported or awaiting installation before the job is finished. | For fabricated work that isn’t installed yet. | Say you finish a custom steel staircase and it gets damaged on the way to the site. An installation floater can protect materials during transport, temporary storage or installation before the customer takes possession. |
How Much Does Welding Contractor Insurance Cost?
You'll spend around $233 per month or $2,792 per year, as that's the average rate of welding contractor insurance costs. Decorative or light repair work often leads to lower rates than if you do structural or pressure-vessel welding. Besides the type of work you do, factors like hot-work exposure or location also affect your actual rate.
Welding coverage costs by policy type are as follows:
- General liability: $510 per month or $6,123 per year
- Tools and equipment: $48 per month or $576 per year
- Commercial auto: $194 per month or $2,328 per year
- Workers' comp: $142 per month or $1,700 per year
- Commercial property: $249 per month or $2,991 per year
- Installation floater: $54 per month or $648 per year
- Cyber insurance: $68 per month or $817 per year
What Are These Costs Based On?
These estimates reflect a welding business with one to four employees. I used the same business profile across all 50 states and Washington, D.C. so the cost differences come from the coverage being priced rather than changes in company size or other business details.
For general liability, I used limits of $1 million per occurrence and $2 million aggregate. Workers’ comp and commercial auto follow each state’s minimum requirements. Commercial property costs reflect the value of the property being insured, while cyber assumes a $1 million limit. The tools and equipment and installation floater estimates come from separate external research focused on small welding contractors, so they aren’t part of the same dataset.
Your welding insurance mix can change what you pay, especially if you split time between shop fabrication and field work. Our business insurance calculator gives you a more tailored estimate.
Welding Contractor Insurance Cost Calculator
Select your state and industry to view average business insurance premiums in your area. Rates are calculated based on a business with 5 employees and $500,000 in annual revenue.
Select Coverage Type
Select State
Select Employee Cand
Select Vehicle Type
Average Monthly Cost—
Select Coverage Type
Average Monthly Cost—
Select State
Select Employee Cand
Select Vehicle Type
How To Buy The Best Welding Contractor Insurance
Going for the insurer with the lowest premium doesn't guarantee you get the best insurance for your welding business. I've mapped out the steps and prepared a downloadable buying checklist. Use these in tandem to make sure your bases are covered.
- 1
Identify the Insurance You’re Required to Carry
Some coverages, you can’t negotiate away. Hiring your first employee often triggers workers’ comp under state law, and you’ll need the appropriate commercial auto coverage if you have a business-owned vehicle. Commercial clients and general contractors also add another layer of requirements. A contract may set specific general liability limits or require additional insured status before you’re allowed on the job. You may also need to provide a certificate of insurance (COI) as proof that the required coverage is in place.
Read More: Business Insurance Requirements
- 2
Match Your Welding Risks to the Right Coverage
Now, look at which parts of your operation could create a financial loss, then match those exposures to the right policies. If your welding machines travel from job to job, tools and equipment coverage is something worth considering. A fabrication shop creates a different need because equipment and materials stay in a single location, and makes commercial property necessary. If you build something before installing it at a client’s site, an installation floater can cover the fabricated materials while they’re still in your care.
- 3
Set Limits Around What You Could Actually Lose
A contract might tell you the minimum limit you need, but that’s only your starting point. For general liability, think about the most expensive realistic incident on the jobs you take. Damage at a customer’s facility, for example, will likely call for a higher liability limit than light repair work. For equipment or shop property, use what it would cost to replace it today, not the original purchase price. Welding machines and tools could cost more now than when you bought them, so outdated values can leave you underinsured after a major loss.
Read More: How Much Business Insurance Do I Need?
- 4
Check Whether a Provider Fits the Work You Actually Do
Not every insurer will cover every type of welding work. Light fabrication or repair may fit one carrier’s guidelines, while structural or pipeline jobs may need a different insurer. Tell the insurer exactly what kind of welding you do before requesting a quote. That way, you can find out early whether it covers those jobs.
If they do, it’s time to look at how you’ll actually work with them post purchase. Check how easy it’ll be to make changes on your policy and COIs and what happens when you file a claim. Another thing to consider is whether an insurer’s coverage menu can keep up with your needs if your business starts to grow.
- 5
Compare Quotes on the Same Terms
When comparing business insurance quotes, keep the limits and deductibles consistent. Then, check that each quote includes the same coverage types before you compare price. A lower premium only means something if the quotes are built on the same assumptions.
- 6
Read the Policy for Restrictions That Affect Your Work
Before you buy, check the exclusions and definitions. For general liability, pay close attention to completed-operations wording so you know how claims are handled after a welding job is finished. Check whether the policy excludes any welding work you perform, such as structural or pipeline jobs. If you use subcontractors, confirm whether the policy covers their work or whether they need their own insurance.
Also check where your equipment coverage applies. Some policies treat gear differently when it’s in a vehicle or at a jobsite. Review the cancellation terms too, especially if losing coverage could put an active contract at risk.
- 7
Revisit Your Coverage When the Business Changes
Your insurance should change when your operation does. Review your policies when the way you work changes, not only at renewal. You’ll need different coverages or limits if you start taking on structural welding after years of light repair work. If you sell a work truck or move out of a shop, it could mean you’re paying for protection you don’t need anymore.
Welding Contractor Insurance: FAQ
I've covered the basics but you might still need more information. These questions provide more information to help you with your insurance choices.
Welding contractor insurance is a group of policies that protects different parts of your operation. A spark might damage a customer’s property, or someone could steal your welder from a work truck. If you employ other welders, an injury on the job creates another risk. Your insurance mix should reflect how and where you work.
A faulty weld by itself usually isn’t enough for general liability to pay for the repair. The policy becomes more relevant when that work causes separate damage or injury. If a welded railing fails and damages surrounding property, for example, products-completed operations coverage may respond to the resulting loss. The cost of fixing the bad weld itself may still fall on you.
Hiring another welder doesn’t automatically bring them under your policy. Your insurer may expect subcontractors to carry their own coverage and may ask you to collect proof before they start. If you use subs, find out what your policy requires so their work doesn’t create an avoidable coverage gap.
Using your own pickup occasionally for work is different from relying on it every day to haul equipment and travel between jobs. Personal auto insurance may not cover the same business use as a commercial policy. Describe how you use the vehicle to your insurer and confirm which policy should cover it before a claim tests that distinction.
Coverage depends on how your tools and equipment policy treats property you don’t own. Some policies can cover rented or borrowed gear, but the available limit may differ from what applies to your own equipment. Before renting an expensive welder or generator, confirm the limit and whether a loss would be settled at replacement cost or after depreciation.
If a weld simply fails inspection and needs to be redone, general liability generally won’t pay for the rework. There hasn’t necessarily been third-party injury or property damage, which is what GL is designed to address. In that situation, the repair cost may stay with your business even though a later resulting loss could be treated differently.
Welding fumes can fall into a gray area because standard general liability policies may restrict pollution-related losses. That matters more if you work in enclosed areas or industrial environments where fumes could affect other people. If that exposure is part of your jobs, review the pollution exclusion and see whether separate contractor pollution coverage makes sense.
Best Welding Contractor Insurance: Bottom Line
For welding contractors, the right insurance starts with the kind of work you take on. A solo welder doing light field work may only need a few core policies, while a fabrication shop with employees or vehicles has more to protect. Your provider should fit that reality too. ERGO NEXT works well for lower-risk operations with frequent COI needs, while Thimble gives you more flexibility when work comes and goes. biBERK is better suited to established shops that want broader ongoing support.
Those same differences also shape what you pay. A mobile welder with a simpler setup will usually insure a different mix of risks than a shop with employees, vehicles or higher-value property. Once you know what coverage fits your operation, check contract requirements and set limits around realistic losses. Then compare providers using the same coverage setup so the price differences actually mean something.
Get Welding Contractor Insurance Quotes
Get welding contractor insurance quotes from multiple providers, then compare them using the same coverage and limits.
About Connor Bolton

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.
The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.
Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.
Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.
Sources
- Home Depot. "Lincoln Electric 140 Amp Weld-Pak 140 HD MIG Wire Welder w/Magnum 100L Gun, Sample Spools MIG Wire and 2 Flux-Cored Wire 115V Starter Kit.." Accessed November 6, 2026.
- Insurance Institute for Highway Safety. "Fatality Facts 2024: Passenger Vehicle Occupants. ." Accessed November 6, 2026.
- U.S. Bureau of Labor Statistics. "Number and Rate of Nonfatal Work Injuries and Illnesses in Private Industries." Accessed November 6, 2026.
- U.S. Fire Administration. "Nonresidential Fire Estimate Summaries (2015–2024)." Accessed November 6, 2026.