Best Texas Business Insurance Companies

I compared Texas business insurance providers across the sectors that anchor the state's economy, including construction, energy, healthcare and retail, looking at what each policy costs, how much it actually covers and how easy it is to buy, manage and file a claim. The best small business insurance provider depends on how your business runs, so I've split my picks by what you're after:

  • Choose if you want best value and fast coverage: ERGO NEXT
  • Choose if you want deep coverage with agent support: The Hartford
  • Choose if you want low-cost coverage you manage yourself: biBerk
  • Choose if you want to pay only when you're working: Thimble
  • Choose if you run a professional or consulting firm: Hiscox
Featured Partner
The Hartford
The Hartford
  • The Hartford ranks first for coverage depth in MoneyGeek's 2026 Texas business insurance research, with the highest limits and the widest set of endorsements, at an average of $116 a month.
  • In Texas, the only state where private employers can decline workers' compensation, The Hartford recommends starting with general liability and a business owner's policy.
  • AM Best has given The Hartford an A+ (Superior) rating for financial strength.
  • Across the U.S., The Hartford covers more than 1.5 million small business customers.

*MoneyGeek featured partner. Editorial rankings below are independent of this placement. Rates, rankings and savings comparisons are based on MoneyGeek's independent research and Hartford-reported data as of 2026. Figures are estimates and averages, not a guarantee of any individual quote, premium or discount.

I ranked seven business insurance providers in Texas on three things: what a business pays for coverage, how the insurer treats a policyholder who needs help, and whether the policy holds up when a claim gets filed. I scored each of the 25 industries in the analysis separately, since a fair rate for a restaurant isn't a fair rate for a consulting office, and benchmarking within each industry keeps the comparison honest.

Affordability carries the most weight at 50%, because price is where most owners start and it's the one factor every business can compare head to head. Customer experience makes up 30%, covering how easy the insurer is to buy from, how well it communicates and how it handles a claim. Coverage accounts for the last 20%, reflecting the depth of protection, the limits available and the range of policies each carrier writes. See MoneyGeek's full methodology.

ERGO NEXT

ERGO NEXT: Best for Overall Value and Quick Coverage

COMPANY HIGHLIGHTS

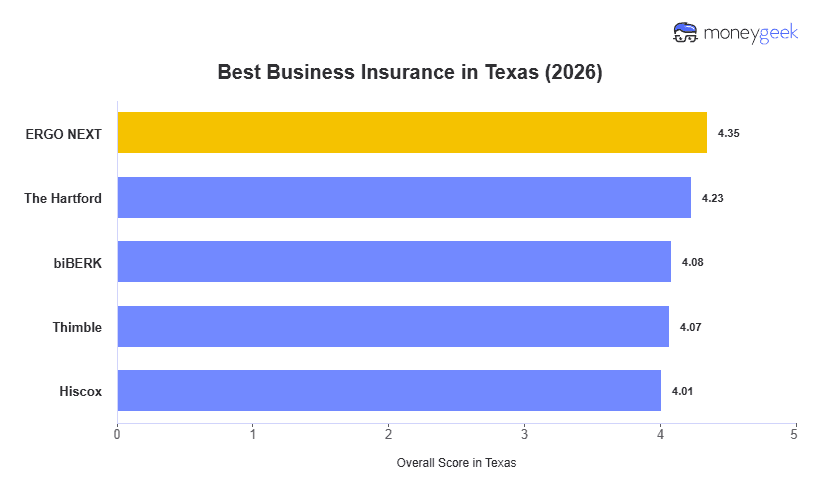
ERGO NEXT is my pick for most Texas small businesses with straightforward coverage needs, since it pairs the lowest average rate in the analysis, $104 a month, with a fast, self-serve buying experience. You can quote, buy, issue certificates of insurance and make routine policy changes from the website or app, no agent required. Its pricing lands hardest for the trades, running roughly 25% below the Texas benchmark for contractors and construction crews. Coverage ranks a respectable third of the seven providers, which is enough for most standard operations. It's a weaker fit for high-risk businesses that need very high limits or specialized endorsements.

Learn More: ERGO NEXT Business Insurance Review

The Hartford

The Hartford: Best for Comprehensive Coverage Options

COMPANY HIGHLIGHTS

The Hartford is my pick for growing or established Texas businesses with more complex coverage needs. It ranks first of the seven providers for coverage depth, offering the highest limits and the widest set of endorsements, enough to satisfy larger client contracts along with coverage for employees and expensive equipment. Its dedicated claims and risk-engineering teams can also review your safety practices and help head off losses before they happen. At $116 a month it isn't the cheapest, and some policies can't be finalized without talking to an agent, so an owner who wants to handle everything online may find it less convenient.

Learn More: The Hartford Business Insurance Review

biBerk

biBerk: Best for Low-Cost Direct Coverage

COMPANY HIGHLIGHTS

biBerk is my pick for straightforward Texas small businesses that want no-frills coverage and are comfortable managing a policy themselves. It sells directly with no broker, which keeps pricing low, and it carries the financial backing of Berkshire Hathaway behind a fully digital experience. That direct model suits owners who already know the coverage they need. The trade-off shows up in service: biBerk ranks last of the seven providers on customer experience, and its coverage ranks sixth of seven, so it's thin for anything complex. At $115 a month, the savings are real for the right buyer but modest against cheaper flexible options.

Learn More: biBERK Business Insurance Review

Thimble

Thimble: Best for On-Demand Coverage

COMPANY HIGHLIGHTS

Thimble is my pick for solo operators and seasonal Texas businesses with on-and-off schedules, since it's the one provider in the analysis that lets you buy coverage by the job, the month or the year. You can get covered online in minutes and pull a certificate of insurance right when a client needs proof before work starts, which fits project-based and short-term jobs well. Its pricing is strong for the trades, about 15% under the Texas benchmark for construction and 18% under for manufacturing. The catch is depth: coverage ranks last of the seven providers, so it's not built for businesses with employees or a company-owned vehicle to insure.

Learn More: Thimble Business Insurance Review

Hiscox

Hiscox: Best for Professional Services

COMPANY HIGHLIGHTS

Hiscox is my pick for Texas consultants, agencies and other professional firms whose biggest risk is being blamed for a mistake rather than a physical accident. It has specialized in professional liability, also called errors and omissions (E&O), for decades, and it packages that coverage for office-based and client-facing work. Financial services run about 12% under the Texas benchmark, and its customer experience ranks third of the seven providers, ahead of the cheaper carriers. At $118 a month it's the priciest on the list, and it's a weaker fit for hands-on trades: it prices fitness and recreation about 12% above benchmark and healthcare roughly 15% over.

Learn More: Hiscox Business Insurance Review

Best Types of Business Insurance in Texas

Most Texas businesses start with general liability, then add coverage based on what they own, who they employ and what they drive. Texas is unusual in that it doesn't force private employers to carry workers' comp, but it does set minimum limits for any vehicle used for business, so the right stack looks different from one operation to the next.

Third-party bodily injury, property damage and related legal costs, like a customer slipping in your shop or damage you cause on a client's site.
Almost every business needs it, and clients, landlords and general contractors in Texas routinely require proof before you can work.
Your building, equipment, inventory and furnishings against fire, theft, storms and similar losses.
If you own or lease a space, or keep valuable equipment or stock on hand. Texas hail and windstorm exposure makes this matter.
Claims that your advice, service or work caused a client a financial loss, also called errors and omissions (E&O).
If your business sells expertise or advice, like consultants, agencies, tech firms and financial offices.
Liability and physical damage for vehicles used in your business, including accidents, injuries and property damage.
Required for any business vehicle in Texas, which sets a 30/60/25 liability minimum. Essential for trucking, delivery and trade fleets.
Medical bills and lost wages for employees hurt on the job, plus employer liability protection.
Optional for most private Texas employers, but often expected by clients and worth carrying once you have staff.
Costs tied to a data breach or cyberattack, including notification, recovery and liability to affected customers.
If you store customer data, take payments online or rely heavily on digital systems.

Best Business Insurance in Texas Checklist

A short checklist keeps you from overpaying for coverage you don't need or, worse, finding a gap after a claim. Work through these five steps before you buy, since the best provider in Texas depends far more on how your business runs than on who ranks first overall.

  1. 1
    Match the Insurer to Your Support Needs

    If you'd rather quote, buy and manage a policy online without calling anyone, go with a digital-first insurer like ERGO NEXT or biBerk. If you want an agent to structure the policy and handle a complicated claim, choose The Hartford. This one preference alone rules out half the field.

  2. 2
    Set Your Coverage to Your Real Risk

    For a low-risk business that needs basic general liability, chase the lowest rate among the light, self-serve carriers. For high limits, expensive equipment or specialized endorsements, go with a carrier that has real coverage depth like The Hartford. Match the insurer to your exposure, not just the cheapest premium.

    Read More: How Much Business Insurance Do I Need?

  3. 3
    Pick a Structure That Fits Your Schedule

    For year-round operations, a standard annual policy from any of the top picks works fine. For seasonal, project-based or event-driven work, Thimble lets you buy coverage by the job or the month instead of paying for a full year.

  4. 4
    Use a Specialist for Business Vehicles

    If your business runs on trucks or vans, treat commercial auto as your main exposure and meet the Texas 30/60/25 liability minimum for every business vehicle. For fleet-heavy operations, a commercial auto specialist like Progressive Commercial usually beats a generalist.

    • ERGO NEXT for smaller operations that need coverage fast.
    • Progressive Commercial for fleets, where commercial auto drives most of the premium.
  5. 5
    Review and Adjust Every Year

    Your coverage should track your business. Adding employees, buying a vehicle, signing a bigger client contract or moving into a new space all change what you need. Re-quote annually on identical limits so you catch both new gaps and better pricing.

Best Business Insurance in TX: Bottom Line

The best insurer is rarely the same for any two businesses, so the useful question isn't who ranks first overall, it's which company is built for the way you operate. Three questions usually get you there.

  • What single loss would actually sink you? A liability lawsuit, an injured employee, a hail-damaged roof, a wrecked truck. The answer points to the coverage that matters most and the insurer that prices it well.
  • Do you want to run insurance yourself or hand it off? Self-service and low rates pull you toward ERGO NEXT or biBerk. Wanting an agent on a messy claim pulls you toward The Hartford.
  • How steady is your work? Year-round operations fit a standard annual policy. Seasonal or project-based work is where Thimble's buy-it-by-the-job model earns its place.

ERGO NEXT is the right starting point for most Texas owners, since it pairs the lowest average rate in the analysis with the smoothest buying experience. If your business carries real coverage complexity, The Hartford is worth a serious look. Once you've got a shortlist, get quotes from two or three insurers on identical limits and let the numbers decide.

Best Business Insurance in Texas Chart

Best Texas Business Insurance: FAQ

About Connor Bolton


Connor Bolton, Senior SEO and Content Manager (Business & Pet), MoneyGeek

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.

The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.

Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.

Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.