Best Business Insurance Companies For Dog Grooming

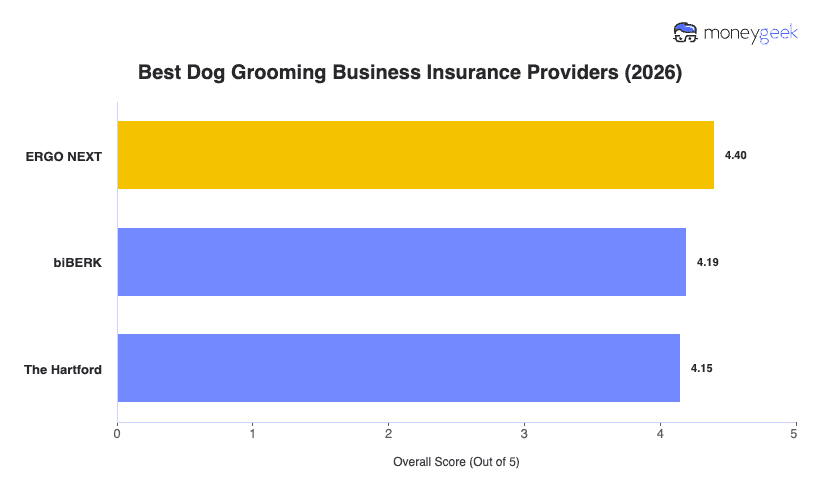
My analysis ranked these companies as the best small business insurers for dog grooming businesses:

  • Choose if you want fast setup and self-service policy management: ERGO NEXT
  • Choose if you want the lowest cost and direct-to-insurer buying: biBERK
  • Choose if you need animal bailee coverage and dedicated claims support: The Hartford

I don't take rankings lightly when a grooming shop's livelihood depends on the recommendation. My rankings are built on three things: what you'll actually pay, what happens when you need help and whether the coverage holds up when it counts. I scored each provider across affordability (50%), customer experience (30%) and coverage options (20%), weighted that way because premium cost determines what a solo groomer or small shop can financially sustain, but it's rarely where the decision should end.

This is what made up my analysis of popular insurers, which was assisted (not run) by AI:

  • Affordability: I pulled quotes isolating pricing factors across pet care sub-industries, all 50 states (plus DC), employee count (5 ranges from 0 to 49), 16 vehicle types (for commercial auto) and six of the most common coverage types, extrapolating 500,000+ estimates to build a full pricing picture for dog grooming businesses specifically.
  • Customer Experience: 300,000+ reviews, forum conversations and industry research were aggregated and manually parsed to identify the patterns that made customers enjoy and dislike service from each insurer. I also went through what an actual grooming shop owner would go through for all providers analyzed, testing their quoting experiences and policy management tools (excluding claims due to limitations).
  • Coverage Options: I read the fine print of policy terms, isolated the exclusions and hidden costs that affect grooming businesses (like care, custody and control carve-outs, animal bailee sublimits and per-animal caps), and documented every option available for all providers to determine which has the best coverage for your shop now and as it grows.
ERGO NEXT

ERGO NEXT: Best Overall for Digital-First Grooming Shops

On ERGO NEXT's site
checkmarkpros
  • Strongest customer experience scores for groomers

  • Quote to bound policy in under 10 minutes

  • 10% discount when bundling two or more policies

closecons
  • Animal bailee coverage not explicitly confirmed

  • Claims support scores below average on appeals

  • Solo operator pricing runs above benchmark

COMPANY HIGHLIGHTS

I recommend ERGO NEXT for most grooming shops because it pairs the fastest buying experience in this study with consistently strong customer satisfaction. Backed by Munich Re since July 2025, it runs about 9% below the sub-industry monthly benchmark and lets you pull a COI instantly from its app at no extra cost. That matters when your landlord needs proof of coverage before your lease starts or at renewal. The 10% bundle discount kicks in when you stack a second policy, and you can manage everything from quoting to claims through the same mobile platform.

Where ERGO NEXT falls short is on the coverage side for grooming specifically. Its pet grooming pages do not explicitly list animal bailee as an available product, so you need to verify directly whether injuries to dogs in your custody are covered before you bind. Claims experience also ranks mid-tier in this study, with below-average scores on appeals handling and defense counsel quality. If a contested animal injury claim is a real possibility for your shop, those gaps are worth weighing against the convenience.

Read Our Review: ERGO NEXT Business Insurance Review

biBerk

biBERK: Best for Cost-Conscious Grooming Shops

checkmarkpros
  • Lowest average monthly cost in this study

  • Berkshire Hathaway AM Best A++ financial backing

  • Licensed advisors walk first-time buyers through options

closecons
  • No animal bailee coverage available

  • Claims and policy support score lowest in study

  • Cancellations require a phone call

COMPANY HIGHLIGHTS

biBERK costs less than every other provider in this study, running about 12% below the sub-industry monthly benchmark on average. That savings comes from its direct-to-business model, which cuts out brokers and middlemen entirely so you keep more of what you'd otherwise lose in fees. Berkshire Hathaway's AM Best A++ rating sits behind every policy, giving you a price point that most small carriers cannot match without sacrificing financial strength. Trustpilot reviews also show that biBERK's licensed advisors explain coverage clearly if you're buying business insurance for the first time.

The trade-off is coverage depth. biBERK does not offer animal bailee coverage at all, which means your standard GL policy leaves a gap for any dog injured, lost or killed while in your shop's custody. Claims and ongoing policy support also score the lowest in this study, and cancellations still require picking up the phone even though everything else can be managed online. If your shop handles a high daily volume of dogs or boards animals overnight, those limitations carry real weight.

Read Our Review: biBerk Business Insurance Review

The Hartford

The Hartford: Best for Shops Needing Animal Bailee and Coverage Depth

On The Hartford's site
checkmarkpros
  • Animal bailee included in pet care BOP

  • In-house claims adjusters and dedicated agent

  • Broadest single-carrier coverage for pet care

closecons
  • Higher average monthly cost than top two

  • Quoting requires agent interaction, not self-service

  • Binding takes longer than digital-first competitors

COMPANY HIGHLIGHTS

The Hartford is the only provider in this study that writes animal bailee coverage as a standard part of its pet care business owner's policy (BOP), with limits typically between $25,000 and $50,000 that can scale up. For a grooming shop, that single feature closes the gap every other carrier on this list leaves open when a dog is injured, escapes or dies while in your custody. It also offers the broadest single-carrier policy selection for pet care businesses, covering GL, commercial property, workers' comp, professional liability and commercial auto under one account without splitting across multiple providers.

The cost of that depth is speed and convenience. The Hartford's quoting process runs through an agent rather than a self-service portal, and binding takes more back-and-forth than competitors who let you finish in minutes. At $62 per month on average, it also runs 13% to 17% above the top two providers in this study. But when a client's dog suffers a serious injury during a groom and you need someone who knows your policy handling the dispute, in-house adjusters and a dedicated agent assigned to your account matter more than how fast you got the quote.

Read Our Review: The Hartford Business Insurance Review

What Types of Insurance Do Dog Grooming Need?

Dog grooming sits apart from most small businesses because the thing you work on every day is a living animal that belongs to someone else. That creates an exposure standard business insurance was never designed for. General liability covers your premises and client interactions, but it excludes animals in your care, custody and control. Animal bailee coverage fills that gap and is the single most grooming-specific policy your shop needs. Beyond those two, workers' comp protects your staff against the bites, back strain and repetitive injuries that come with handling dogs all day, and commercial property covers the equipment your shop cannot operate without.

The table below summarizes the most common types of business insurance that dog groomers need to meet requirements and cover financial risks.

Claims and legal costs when a client is injured on your premises or you damage someone's property, including dog bites to customers in your lobby or waiting area
Your landlord will require this before your lease starts, and it applies from day one if clients enter your shop

More than 4.5 million people are bitten by dogs each year in the U.S., and a grooming shop with daily animal contact and wet floors faces both bite and slip-and-fall exposure simultaneously.

Animal bailee coverage
Veterinary bills, recovery costs and liability when a dog in your custody is injured, escapes or dies during a groom, bath or while kenneled between appointments
Every grooming shop needs this because standard GL policies exclude animals in your care, custody and control
Most generic business insurance was not built for businesses handling live animals. Without animal bailee, a clipper nick requiring vet stitches or a dog that overheats in a cage dryer generates a claim your GL policy will not pay.
Employee medical bills and lost wages after a work injury, including dog bites, back strain from lifting large breeds and repetitive motion damage from sustained scissoring and blow-drying
When you hire your first employee, including part-time bathers or seasonal staff

A peer-reviewed study found that 95% of pet groomers report musculoskeletal symptoms, driven by repetitive manual tasks, awkward postures and the unpredictable movement of the animals they handle.

Damage or loss to your grooming tables, tubs, clippers, dryers, inventory and business income if a covered event forces your shop to close
If you lease or own a shop, run a mobile van or work from home with grooming equipment
Your landlord's policy covers the building, not your contents. A single grooming station runs $5,000 to $15,000 in equipment, and a fire, burst pipe or theft can shut your shop down overnight while your lease obligations continue.
Defense costs and settlements when a client claims your grooming technique, product choice or advice caused their dog harm
If you perform any service beyond a basic bath, including dematting, medicated treatments or breed-specific cuts
When a client alleges your shampoo caused a chemical burn or your clipper work injured their dog's skin, the claim targets your professional judgment. GL will not respond because it was not a premises injury.
Injuries and vehicle damage from accidents during mobile grooming runs, client pickups or supply trips in a business-owned vehicle
If your shop owns a grooming van, offers pickup and delivery or uses a vehicle primarily for business
Personal auto policies typically exclude commercial use, so an accident while transporting a client's dog to your shop leaves both the vehicle damage and the animal injury uninsured.
Bundles general liability with commercial property coverage at a single location, often at a lower combined cost than buying each separately
Small shops that need both GL and property coverage and want to simplify their policy management
A BOP consolidates two of your most essential coverages into one policy with one renewal date and one premium, and some carriers like The Hartford include animal bailee as a standard addition to their pet care BOP.
Costs from data breaches, ransomware and notification obligations when client records or payment data stored in your booking software are compromised
When your shop stores client contact information, processes card payments or uses cloud-based scheduling tools
A breach that exposes client payment data triggers notification requirements in every state, and the legal and remediation costs can reach five figures before your shop even addresses the reputational damage.
mglogo icon

WHY GETTING DOG GROOMING INSURANCE IS IMPORTANT

Your shop works with sharp tools, heated dryers, water and anxious animals every day. One serious incident can generate costs that make years of premium payments look small. The average dog bite liability claim paid $65,450 in 2025, and total U.S. insurer payouts for dog-related injuries reached $1.57 billion in 2024. General liability for a grooming shop averages $79 per month. That means a single uninsured bite claim could equal more than six years of premium payments, and it does not account for the separate exposure your shop carries when a dog is injured in your custody, an employee is bitten or your equipment is destroyed.

How Much Does Dog Grooming Business Insurance Cost?

Dog grooming insurance costs for a small shop with 1 to 4 employees average $59 per month across all coverage types, which is 47% above the all-industry average. Commercial auto runs the highest at $102 per month because your policy covers both the vehicle and the dogs your shop is transporting, while professional liability is the least expensive at $30 per month. What you actually pay depends on your daily dog volume, whether you offer boarding or mobile services alongside grooming and how many employees are on your payroll.

Here's an overview of costs for common coverage types:

What Are These Costs Based On?

Our business insurance calculator below can give you a more tailored estimate based on your shop's details. It also connects you directly with a provider match when you're ready to get quotes.

Dog Grooming Insurance Cost Calculator
Select Coverage Type
Select Employee Count
Select Vehicle Type
Select State
Average Monthly Cost—

How To Buy The Best Dog Grooming Business Insurance

I've outlined the buying process below step by step. If you want something to take with you while gathering quotes, download the dog grooming business insurance buying worksheet to keep everything organized across providers.

  1. 1

    Identify Required Coverages

    Start with your lease agreement, because your landlord almost certainly requires general liability before you can open. Then look at whether your state mandates workers' comp at your first hire, since most do and grooming's injury rate makes it essential regardless. If commercial clients like boarding facilities or veterinary offices refer customers to your shop, check whether their referral agreements require specific limits or endorsements. A certificate of insurance (COI) proves your coverage exists, but if a landlord or referral partner needs to be listed as an additional insured, that has to be added through your carrier as a policy endorsement.

    Read More: Business Insurance Requirements

  2. 2

    Map Your Shop's Risks to Coverage

    Walk through a real scenario and test which policy would pay. Say a dog in your cage dryer overheats while you are working on another animal, and the dog dies before you notice. General liability will not respond because the animal was in your care, custody and control. Only animal bailee coverage would apply. Run that same exercise for a client who slips on your wet floor, a groomer who develops carpal tunnel from years of scissoring and an employee who is bitten by an anxious dog on the table. Each points to a different policy, and any gap means your shop absorbs the full cost.

  3. 3

    Set Limits That Reflect Your Actual Exposure

    Your limits should reflect the worst realistic claim your shop could face, not the cheapest option available. A dog that dies during a groom can generate veterinary bills, replacement value disputes and emotional distress claims that push well past a $5,000 animal bailee sublimit. On the premises side, dog bite liability claims averaged $65,450 in 2025. If your shop handles 15 or more dogs daily, a single bad day with two simultaneous incidents could exhaust a $1 million per occurrence GL limit.

    Read More: How Much Business Insurance Do I Need?

  4. 4

    Research Providers Who Understand Dog Grooming

    Not every insurer writes coverage that accounts for the risks a grooming shop actually creates. Some carriers exclude care, custody and control entirely from their GL policies and do not offer animal bailee as an add-on. Others will cover your premises but price workers' comp poorly for the bite and repetitive strain exposure that grooming generates. Before requesting quotes, confirm that each provider on your list covers pet care businesses specifically and ask whether animal bailee is available and what the per-animal sublimits look like.

  5. 5

    Compare Pricing and Quotes With Identical Terms

    Look up what dog grooming insurance typically costs for your shop size and service mix so you have a baseline before requesting quotes. Then request quotes using the same limits, deductibles and endorsements from every provider. A policy that costs $15 less per month but excludes animals in your custody or caps animal bailee at $2,500 per incident is not actually cheaper. Line up the terms side by side before comparing premiums.

  6. 6

    Review Your Policy Before Buying

    Read the policy document against your lease requirements and any referral agreements before you sign. Confirm that care, custody and control is covered explicitly, not just implied. Check that your named insured matches your business's legal name exactly, because a mismatch can invalidate a COI your landlord already accepted. Verify that business interruption coverage is included if a covered loss would force your shop to close, since your lease payments and staff obligations do not stop when your doors do.

  7. 7

    Reassess Coverage When Your Shop Changes

    Hiring your first employee triggers workers' comp requirements in most states. Adding boarding or overnight stays changes your animal bailee exposure from daytime custody to around-the-clock liability. Buying a grooming van introduces commercial auto. Opening a second location may require separate property policies for each site. Any of these shifts can create gaps in coverage that did not exist when you first bought your policy. Review your coverage at least once a year and before any operational change takes effect.

Dog Grooming Insurance: FAQ

Beyond what this guide covers, I've answered the most common remaining questions grooming shop owners have before purchasing business insurance.

Best Dog Grooming Business Insurance: The Bottom Line

The one thing that separates grooming insurance from most small business coverage is animal bailee. Your standard GL policy excludes animals in your care, custody and control, which means the most common and most costly claim a grooming shop faces is the one most generic policies will not pay. 

When you compare quotes, check whether animal bailee is included, what the per-animal sublimits are and whether the aggregate cap can absorb a multi-animal incident on a busy day. Two policies at the same monthly cost can look identical until a dog is injured and one of them responds while the other does not. And as a reminder before you compare, these are my top picks overall for dog groomers.

Best Dog Grooming Business Insurance Chart

Get Dog Grooming Business Insurance Quotes

Use our matching tool below to find providers that fit your grooming shop. From there, you can get quotes and compare coverage directly on their site.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources