Best Workers' Comp Insurance Companies in New Hampshire

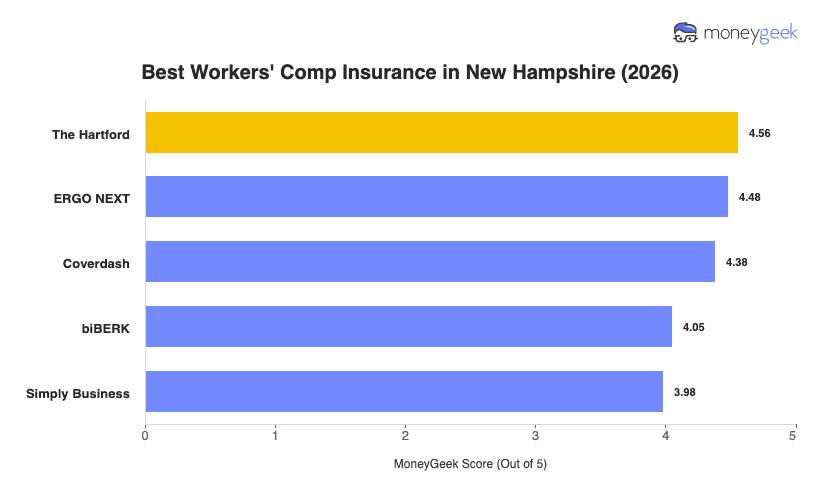
The Hartford is the best workers' compensation insurance provider in New Hampshire, costing you an average of $89 per employee per month. ERGO NEXT, which comes next in my analysis has the same monthly rate. Which provider is best for your business depends on your preferences and priorities.

If you have layered needs and want tailored support from a dedicated team, The Hartford is a better fit. However, if your work requires you to have same-day coverage or you prefer to manage your policy on your own, ERGO NEXT might be the better option.

The Hartford4.56$8933
ERGO NEXT4.48$8916
Coverdash4.38$10551
biBERK4.05$11288
Simply Business3.98$12422

MoneyGeek analyzed workers' comp insurance rates and provider performance across New Hampshire using small business profiles with one to four employees spanning 408 major industries. Companies earn up to five points in each category in our scoring system. We then use a weighted average of these category scores to calculate a MoneyGeek score out of five.

  • Affordability (55%): Based on average payroll for the most common employee code per industry and state classification, priced per employee for a one to four employee business.
  • Customer Experience (35%): Evaluates buying (20%), which covers quote access, pricing accuracy and sales support; policy management (30%), which covers payroll reporting, audits, billing and loss control; and claims (50%), which covers FNOL speed, adjuster support, medical access, wage replacement and dispute handling.
  • Coverage Options (10%): Assesses coverage completeness (35%), including employers' liability and wage and medical reimbursement; policy flexibility and endorsements (25%); eligibility, state and industry breadth (20%); and policy terms, limits and exclusions (20%).
The Hartford

The Hartford

Best Workers' Comp Insurance in New Hampshire

MoneyGeek Rating
4.6/ 5
4.9/5Affordability
4.1/5Customer Experience
4.5/5Coverage Points
  • Average Monthly Cost

    $89
  • Claims Processing Score

    4.1/5
  • Policy Management Score

    4/5
  • Buying Process Score

    4/5
ERGO NEXT

ERGO NEXT

Best New Hampshire Workers' Comp Insurance: Runner-Up

MoneyGeek Rating
4.5/ 5
4.8/5Affordability
4.2/5Customer Experience
4.1/5Coverage
  • Average Monthly Cost

    $89
  • Claims Processing Score

    4/5
  • Policy Management Score

    4.1/5
  • Buying Process Score

    4.4/5

Cheapest Workers' Comp Insurance Companies in New Hampshire

Workers' comp costs in New Hampshire start as low as $9 per month for financial services businesses, where The Hartford offers the cheapest workers' compensation rates. The Hartford leads on price across most low- to mid-risk industries, including marketing, consulting, retail and health care. ERGO NEXT takes over as the cheapest option in higher-risk categories like construction, transportation and agriculture, where rates climb considerably. Coverdash offers the best rates for childcare and fitness services.

Financial ServicesThe Hartford$9$108
Beauty, Body & Wellness ServicesThe Hartford$11$132
Marketing & CommunicationsThe Hartford$12$144
Consulting ServicesThe Hartford$14$168
Real Estate & Property ServicesThe Hartford$15$180
Other Professional ServicesThe Hartford$18$216
Tech/ITThe Hartford$30$360
Childcare ServicesCoverdash$33$396
Hospitality, Travel & TourismThe Hartford$34$408
Healthcare & MedicalThe Hartford$36$432
Food & BeverageERGO NEXT$39$468
Retail & Product RentalThe Hartford$42$504
Nonprofit & AssociationsThe Hartford$47$564
Pet Care ServicesERGO NEXT$58$696
Fitness ServicesCoverdash$60$720
EducationThe Hartford$61$732
Repair & MaintenanceERGO NEXT$66$792
Arts, Media & EntertainmentERGO NEXT$86$1,032
Cleaning ServicesThe Hartford$100$1,200
Recreation & SportsERGO NEXT$102$1,224
ManufacturingThe Hartford$120$1,440
Agriculture & Natural ResourcesERGO NEXT$149$1,788
Wholesale & DistributionERGO NEXT$176$2,112
Construction & ContractingERGO NEXT$215$2,580
Transportation & LogisticsERGO NEXT$274$3,288

How to Get the Best Workers' Comp Insurance in New Hampshire

Follow these steps to secure the right workers' comp coverage for your New Hampshire business. For a full overview, see our guide on how to get workers' compensation insurance.

  1. 1

    Confirm New Hampshire Coverage Requirements

    New Hampshire requires workers’ compensation coverage when you have one or more employees, including part-time workers. Sole proprietors and partners generally do not count as employees, but other ownership structures may receive different treatment. Confirm your state’s workers’ compensation requirements before anyone begins work.

  2. 2

    Identify Your NCCI Class Codes

    New Hampshire follows NCCI’s classification system, which assigns each type of work a code based on its injury risk. Focus on employees’ actual responsibilities rather than broad titles such as “assistant” or “manager.” The New Hampshire Insurance Department directs employers to NCCI for detailed class descriptions when a worker’s duties do not fit neatly into one category.

  3. 3

    Document Payroll, Employee Count and Claims History

    Separate your payroll by class code and obtain loss runs, which summarize your previous workers’ compensation claims. Check anyone you treat as an independent contractor as well. New Hampshire uses a specific legal test to determine whether someone works independently, so issuing a 1099 does not automatically remove that person from your coverage obligations. You can review the state’s independent contractor criteria before requesting quotes.

  4. 4

    Request Quotes From Multiple Licensed New Hampshire Carriers

    Each carrier applies its own expenses and pricing approach to New Hampshire’s approved loss costs, so premiums can differ for the same business. Compare business insurance quotes from insurers licensed in the state. If you cannot secure coverage through the standard market, NCCI administers New Hampshire’s assigned risk plan, which serves employers that insurers will not cover voluntarily.

  5. 5

    Compare on Quality, Not Just Price

    New Hampshire allows an injured employee to choose their own physician, unlike states that limit treatment to an insurer’s network. Ask how each carrier coordinates with outside providers and processes medical bills. Clear claim communication also matters because delays between the employer, doctor and adjuster can slow benefit decisions.

  6. 6

    Complete Purchase and Establish Payroll and Audit Reporting

    Ask your insurer for New Hampshire’s required workplace poster and set up the payroll reporting method used for your policy audit. If an employee gets hurt, you must submit an Employer’s First Report of Injury within five days of learning about the injury. File the report even if you question whether the claim qualifies; reporting an incident does not mean you accept responsibility for it.

  7. 7

    Review at Annual Renewal

    Compare the payroll used in your audit with the estimates on your renewal offer. Correct outdated class codes and confirm that anyone treated as an independent contractor still meets New Hampshire’s test. NCCI updates the state’s loss costs regularly, but your own claims record and the carrier’s pricing can move your premium in a different direction. Get fresh quotes if the renewal no longer reflects your operations.

Best Workers' Compensation Insurance in New Hampshire: Bottom Line

The Hartford and ERGO NEXT are the best workers' comp insurance providers New Hampshire, both averaging $89 a month. The Hartford's stronger claims handling suits employers who expect to file frequently, while ERGO NEXT's digital platform fits businesses that prioritize buying ease and daily management. Coverdash serves employers who need the broadest coverage options in the state.

Best Workers' Comp Insurance in New Hampshire Chart
mglogo icon
LEARN MORE ABOUT NEW HAMPSHIRE BUSINESS INSURANCE

The best business insurance in New Hampshire includes more than workers' comp. See which providers we recommend for other coverage types you might need.

New Hampshire Workers' Compensation Insurance FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com