Best General Liability Insurance Companies in Florida

I determined the best general liability insurance for Florida small businesses by gathering quotes from 10 major insurers, across 25 general industries, including professional firms and repair services. Cost, however, was only one part. I also reviewed how accessible carriers are when you need support and how fast you can get proof of coverage.

My top picks are as follows:

  • Choose if you offer hands-on service: ERGO NEXT
  • Choose if you want affordable coverage: The Hartford
  • Choose if you're in services: biBerk
  • Choose if you want to compare multiple carriers: Simply Business
  • Choose if you want comprehensive coverage needs: Coverdash

For our Florida general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of Florida's small businesses, while weighting results to ensure broader industry and location representation across Miami, Tampa, Jacksonville, Orlando and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 6,800 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Florida businesses consistently across different industries and regions. We then rated each company across affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Florida, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

6,837

Customer Experiences Analyzed

ERGO NEXT

ERGO NEXT: Best Overall, Best for Hands-On Industries

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT has a digital-first platform that delivers quotes in under 10 minutes and instant certificate-of-insurance generation through its mobile app. The buying process requires no agent, allowing Florida businesses to bind coverage for standard risks from their phones. Claims handling is less competitive, with recorded complaints on BBB from Orlando, Tampa and Jacksonville businesses citing slower resolution timelines and inconsistent adjuster communication. One Tampa contractor reported a 90-day slip-and-fall claim that competitors resolved in 30 to 45 days.

ERGO NEXT is the second most affordable insurer in Florida, saving businesses 15% against the state benchmark. Repair services, maintenance, hospitality and construction see the biggest savings. Liquor liability and pollution coverage are not available, which rules ERGO NEXT out for some Florida restaurants and contractors.

Learn More: ERGO NEXT Business Insurance Review

The Hartford

The Hartford: Best Cheap General Liability Insurance

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford offers small businesses in Florida coverage options including liquor liability endorsements valuable for Florida's tourism and hospitality industries, professional liability bundling and umbrella policies up to $10 million. While this breadth separates it from other insurers, it requires you to work with agents. That affects the overall customer experience since it takes longer to get a quote than digital-first alternatives. It does well with policy management, with Florida businesses in Miami, Tampa and Jacksonville praising local Hartford agents for same-day turnaround on certificate modifications, and one Orlando contractor reported adding an additional insured within hours.

The Hartford averages $122 a month, the lowest rate in Florida and 16% below the state average. Its dedicated adjusters handle claims and keep you updated. One Tampa restaurant owner reported that a customer injury claim was resolved in 45 days, and Better Business Bureau (BBB) reviews from Fort Lauderdale and Sarasota describe good outcomes after hurricane-related incidents.

Learn More: The Hartford Business Insurance Review

biBerk

biBerk: Best for Service and Activity Businesses

COMPANY HIGHLIGHTS

With a hybrid digital-agent buying model that lets businesses choose instant online quotes or consultative agent support, biBerk offers a different experience to business owners. For most part, the insurer provides reliable, though not stellar, service. One Jacksonville business owner described a slip-and-fall claim as "straightforward" but "not particularly fast," resolving in 60 days.

biBerk saves Florida businesses 8% compared to the state benchmark, with service industries like hospitality businesses, manufacturing and real estate operations enjoying the lowest rates. It’s also the cheapest option for solopreneurs, giving them 15% savings. When it comes to coverage, biBerk includes liquor liability endorsements valuable for Florida hospitality businesses but lacks the specialized endorsements, like EPLI bundling and pollution liability.

Learn More: biBerk Review

Simply Business

Simply Business: Best for Comparing Multiple Carriers

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business charges $141 monthly. It's not the cheapest in Florida, but 2% below the state benchmark. Beauty and wellness, food and beverage, retail and repair operations pay 10% to 16% below the state average. Marketing, nonprofit and tech businesses pay 7% to 15% more.

Simply Business is a marketplace, not a carrier. Florida businesses enter their information once and get quotes from multiple carriers simultaneously. Endorsement access is broader than single-carrier platforms, but specific carriers and coverage options aren't guaranteed for every business profile. Policy management and claims go directly through whichever carrier you select.

Learn More: Simply Business Review

Coverdash

Coverdash: Strong for Comprehensive Coverage Needs

COMPANY HIGHLIGHTS

Coverdash is a broker marketplace that connects businesses with several partner insurers. Its biggest advantage is endorsement access, since its partners have specialized options for many types of business. Its prices are in the middle of the pack, 4% above Florida's average. Manufacturing and food service businesses save a little. Construction, wholesale and hospitality businesses pay 10% to 17% above average.

Quotes take longer than most competitors, with Florida businesses reporting waits of several days. The platform returns one to two carrier options rather than a wide selection. Policy management and claims go directly through the selected carrier.

Learn More: Coverdash Business Insurance Review

What Determines the Best General Liability Insurance for Florida Businesses

The risks you carry as a Jacksonville roofing contractor are considerably different that if you have a yoga studio in Sarasota, but in both situations, you'll need an insurer that works reliably after the policy begins. The best general liability insurance for your Florida business must remain manageable and keep up when your work changes.

How to Choose the Best General Liability Insurance in Florida

Once you know what matters most for your Florida business, it's easier to get general liability insurance that fits your coverage needs. These steps help you narrow your options and compare your finalists.

  1. 1
    Optimize your payment and coverage structure

    First, map out your business's risks and any general liability requirements that apply to your work in Florida. Most businesses don't think about liability requirements until a client contract asks for proof of insurance or someone gets hurt on a job site. Answer these questions first:

    • Do any clients, venues or contracts require specific liability limits or additional insured endorsements?
    • What's your annual revenue, and how much contact do you have with customers?
    • Could you pay a $2,500 deductible out of pocket, or do you need a lower one?
    • Would monthly payments fit your cash flow better than paying for the year up front?

    Most Florida small businesses need at least $1 million per occurrence and $2 million aggregate. A Tallahassee property maintenance crew working on several commercial sites each month may want monthly payments and a lower deductible to handle frequent small claims. A Clearwater mobile pet groomer with less customer contact can save money by paying annually with a higher deductible.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your priority

    Decide which factor matters most to you right now. It'll break the tie when insurers score about the same. Your industry, how steady your revenue is and how complex your business is all point you toward a starting place.

    • Affordability: Put price first if you work on thin margins and expect few, predictable claims. A Lakeland retail boutique or Pensacola bookkeeping firm with little liability risk gets more out of a stable premium than out of endorsements it probably won't use.
    • Customer experience: Put service first if delays would cost you work. A Naples event planner who books venue contracts every week can't afford slow certificates, and a Daytona Beach subcontractor who adds job sites mid-policy needs quick changes. Fast service keeps you from losing revenue when client requirements change, even if you pay a bit more.
    • Coverage options: Put coverage first if your liability risk is growing. If you expand from residential cleaning to medical facilities in Gainesville, or add chemical treatments to pool routes in West Palm Beach, you'll need an insurer with specific endorsements and higher limits.
  3. 3
    Shortlist two to three providers

    You don't need to compare every insurer in Florida. Narrow your list to two or three that match your priority and coverage needs. A longer list takes more time without leading to a better choice.
    Before you compare in detail, confirm that each insurer covers your industry and your part of Florida. Some insurers exclude high-risk professions or pull out of hurricane-prone counties, so check eligibility early. That way, you won't spend hours on insurers that can't cover a Destin surf shop or Homestead nursery at any price.

  4. 4
    Double-check for dealbreakers before investing more time

    Before you go further, check each insurer on your shortlist against your must-haves. If you find a dealbreaker late, you'll lose hours and have to start over. You don't want to ask for quotes from an insurer that can't cover your business. Confirm these up front:

    • Certificate turnaround: Can you get same-day digital certificates for venue contracts and permit applications, or does the insurer need three to five business days?
    • Additional insured endorsements: Does the insurer charge a fee for each endorsement when a Florida property manager or general contractor asks to be added?
    • Coastal county coverage: Some insurers exclude Monroe, Miami-Dade, Broward or Palm Beach counties because of hurricane risk. That rules them out for South Florida businesses entirely.
    • Industry restrictions: Many insurers won't cover roofing, tree services or watercraft businesses in Florida. Check that you're eligible before you compare.
  5. 5
    Compare your finalists using the same three lenses

    Look at each finalist in all three areas. Your top priority narrows the list, but it doesn't replace a full comparison.

    • Affordability: Look past the first quote. Check how renewal prices change over time, how mid-term changes work when your Ocala retail shop expands or your Bonita Springs landscaping crew hires more people and whether year-end audits bring surprise costs.
    • Customer experience: Check how fast the insurer issues certificates for Naples venue contracts, how quickly it makes policy changes when you add Fort Myers job sites mid-term and how responsive its adjusters are after a slip-and-fall at a customer's property.
    • Coverage options: Check whether you can raise your limits from $1 million to $2 million, which endorsements are available (like hired auto or liquor liability) and whether adding coverage mid-term costs extra for Bradenton event businesses or Vero Beach pool services.
  6. 6
    Use quotes as the final confirmation step

    Ask your two or three finalists for quotes using your exact business details, then compare business insurance quotes. Quotes show whether the insurer can cover your business, whether you're a Coral Springs caterer, a Stuart handyman or a Doral consulting firm. They also catch eligibility problems, surprise prices and coverage gaps before you buy.

Best Small Business General Liability Insurance in Florida: Bottom Line

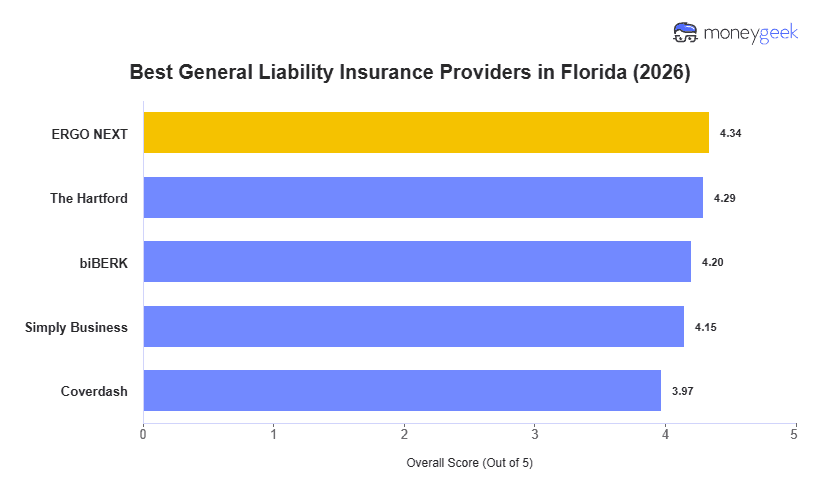
ERGO NEXT, The Hartford, biBerk, Simply Business and Coverdash are the top-ranked options in MoneyGeek's Florida general liability analysis. The right pick depends on your industry, business size and location. The best insurers hold pricing steady, turn certificates fast and scale coverage as the business grows, without charging for exposure that doesn't apply.

Best General Liability Insurance for Small Business in Florida Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

General liability is only one of the coverage types you need to make sure you have enough financial protection. If you want the best small business insurance in Florida, check out the resources below to see which providers we recommend for other coverages.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com