


Jump to the section that meets your needs best below:
Painting Contractor Business Insurance Cost (2026 Report)
Painting contractor business insurance costs for most in the industry are between $71 and $1,161 a month for a single policy. However, this range widens when you consider different business sizes, location vehicle type, and coverage needs.
If you're ready to get a quote, use the tool below to get matched with the best business insurance provider for your painting contractor operations.
Select state
Updated: September 11, 2026
Advertising & Editorial Disclosure
How Much Does Painting Contractor Business Insurance Cost?
Painting ranks 17th in affordability within its general industry category, and 339th compared to all other areas of work, in MoneyGeek's analysis of contractor insurance costs. $183 a month is the average monthly rate that comes out to, slightly below the $190 a month national average for its work category, but well above the $111 a month national average overall.
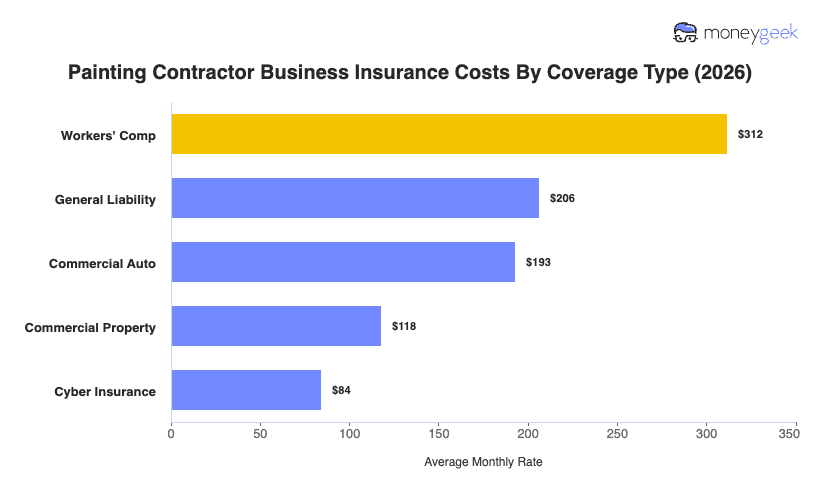
Workers' comp ($312 a month per employee) and general liability ($206 a month) cost the most among contracting coverage types, like any other contracting work, because of high public exposure, the risks that come with frequently changing clients, especially in residential work, and the chance of fall injuries while painting home exteriors or high-rise interior walls.
Commercial property, cyber and commercial auto policies land more toward the middle of the spectrum, but each can rise past benchmarks on its own trigger: specialized equipment for commercial property, extensive stored customer data for cyber, and more frequent or longer-distance driving for commercial auto.
| Cyber Insurance | $84 | $1,007 | 243 |
| Commercial Property | $118 | $1,414 | 288 |
| Commercial Auto | $193 | $2,316 | 282 |
| General Liability | $206 | $2,478 | 339 |
| Workers' Comp | $312 | $3,739 | 373 |
We analyzed quote data from major U.S. commercial insurance providers and modeled standardized premium estimates across business profiles representing around 95% of the market. Results are designed to provide a consistent national benchmark showing how premiums vary by key baseline factors including business size, profession type, location and vehicle type for operations that use commercial vehicles.
Dataset Scope and Assumptions
Our cost modeling uses standardized inputs for consistent comparisons across businesses.
- Total estimates modeled: just over 6 million standardized pricing estimates
- Providers analyzed: 10 major insurance providers
- Geography: all U.S. states including Washington, D.C.
- Employee count bands: solo practitioners, one to four, five to nine, 10 to 19, and 20 to 49 employees
- Vehicle types studied: Sedans, SUVs, pickup trucks, vans, taxis, limousines, tractors, food trucks, semi-trucks (non-HAZMAT and HAZMAT), tanker trucks (non-HAZMAT and HAZMAT), buses, box trucks, dump trucks, flatbed trucks
- Policies studied: general liability, workers' comp, professional liability, commercial auto, commercial property, and cyber insurance
- General liability: $1 million per occurrence and $2 million aggregate
- Workers' comp: state required coverage
- Professional liability: $1 million per claim and $1 million aggregate
- Commercial auto: minimum coverage
- Commercial property: personal property coverage limits personalized to industry, business size and state
- Cyber insurance: $1 million per occurrence and $1 million aggregate
How We Calculated Average Painting Contractor Business Insurance Costs
Our published averages represent modeled premiums for standardized business profiles and were aggregated in two ways.
- National benchmark average: The national average cost reflects the modeled premium for a standardized one to four employee business across all profession categories and states included in our dataset for a standard professional liability policy
- Segment averages: To show how costs vary, we calculated average modeled premiums for our national base profile and isolated for variables, including:
- Employee count (business size ranges)
- Profession / industry categories
- Vehicle types (for commercial auto)
- States (including Washington, D.C.)
Segment averages were produced by aggregating modeled pricing trends across the full dataset so readers can compare how premiums shift across profession types and regions.
See our full business insurance methodology.
Get Painting Contractor Business Insurance Cost Estimates
The painting business insurance cost calculator below lets you get more personalized estimates to compare rates.
Get Painting Contractor Insurance Cost Estimates
Select Coverage Type
Select State
Select Employee Count
Select Vehicle Type
Monthly Rate Estimate—
Select Coverage Type
Monthly Rate Estimate—
Select State
Select Employee Count
Select Vehicle Type
How to Lower Painting Contractor Business Insurance Costs
Painting contractor costs are high at the national level, and the main drivers are coverages you can't avoid paying for, including general liability which is contractually required and workers' comp and commercial auto which are required by state law. The following methods can help you find more affordable coverage without stressing your finances.
 Protect your classification code
Taking on drywall, remodeling, or carpentry can trigger a reclassification away from the painting code, and your workers' comp rate could roughly double for the same payroll. The same logic applies to your general liability rate. Keep your service description consistent across your application, your website, and your contracts.
If you refer out-of-scope work rather than doing it yourself, make that explicit to your carrier. Underwriters check both, and a mismatch between the two is one of the more common reasons painters end up in a higher rate category than their actual work justifies.
 Be specific about your work mix
Assumptions without specifics are a major reason you'll end up paying more for insurance than necessary as a painter or any other contractor. Exterior work, especially at height, involves greater risks than standard interior painting, and insurance pricing reflects that increased risk. If your business is primarily residential interior, being specific about that mix lowers both your GL and workers' comp rates without reducing any coverage you actually need.
A general application that does not distinguish between interior and exterior can price in scaffolding and multi-story exposure you do not carry. So, in order to properly classify your business's risk, communicate with your insurer, provide the most accurate details, and don't just stop at the online buying process to save as much as possible.
 Keep your payroll accurate throughout the year
Workers' comp is audited annually against actual payroll, and the surprise bill at the end of the year is one of the most common ways painting contractors overpay. Getting the number right for both your end and the insurers allows your in-year premium and your audit outcome to be predictable, making you not overpay and making planning for your painting jobs much easier.
 Collect subcontractor COIs before work starts
If subcontractors do not carry their own insurance, you could be held liable for their injuries even if they are 1099 contractors rather than W-2 employees. Uninsured sub exposure flows through to both your GL and workers' comp rates at renewal.
Collecting a current certificate of insurance from every sub before they start is one of the most direct ways to keep claims off your record and your rate from reflecting an exposure you are not actually carrying. Also, requiring a primary and noncontributory clause allows in clear writing for a sub-contractor's insurance to take affect before yours, allowing you to save and avoid the risk of adding another claim to your policy's history.
Painting Contractor Business Insurance Cost: Bottom Line
The $183 monthly average isn't what you'll pay. It's where to start. Your actual quote depends on crew size, vehicle type, the work you take on, and your state.
Workers' comp and GL drive most of the variance in painting quotes. If your number seems off, those are the first two places to look. Three questions help narrow it down:
- Where do you fall in the distribution? Crew size and state are the two biggest positioning inputs. A solo painter and a 10-person crew operate in entirely different price ranges within the same classification.
- Is your quote consistent with your risk profile? Interior-only crews and exterior or elevated work are priced differently. If your quote doesn't reflect what your crew actually does, review that classification with your broker.
- Which cost drivers apply to your business? Not every factor on this page applies to every operation. Identify the ones that describe yours and you'll know what's moving your number.
Most quote gaps trace to one or two inputs, not the full list. Find your position, then find the drivers, and compare quotes from there.
About Connor Bolton

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.
The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.
Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.
Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.