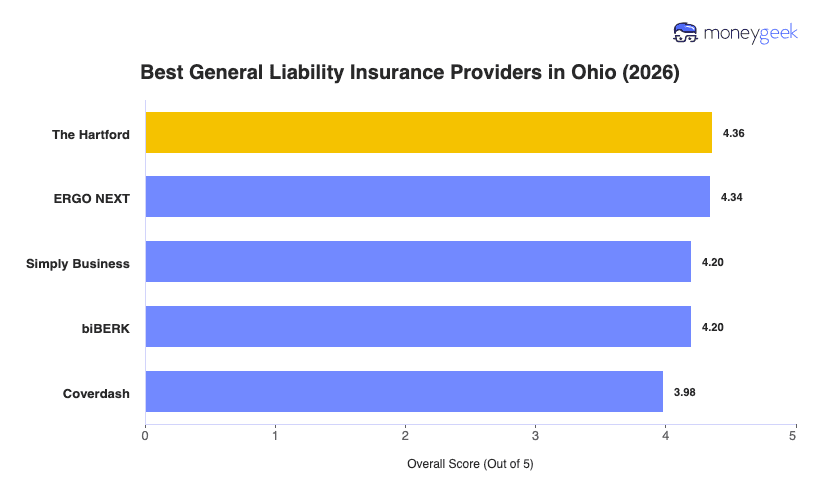
Best General Liability Insurance Companies in Ohio

I reviewed quotes from 10 insurers across 25 industries to choose the best general liability insurance companies in Ohio. These included manufacturing and health care businesses, which are common in the state. I compared how much insurers cost for GL coverage, looked at whether final policy terms matched the quote and whether they clearly explained claim decisions.

My top recommendations are:

  • Choose if you're in health and fitness: The Hartford
  • Choose if you prioritize is customer experience: ERGO NEXT
  • Choose if you want to compare multiple carriers: Simply Business
  • Choose if you work in health and fitness: biBerk
  • Choose if your so seasonal work: Thimble

For our Ohio general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of Ohio's small businesses, while weighting results to ensure broader industry and location representation across Cleveland, Cincinnati, Columbus, Akron and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 3,400 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Ohio businesses consistently across different industries and regions. We then rated each company across affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Ohio, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

3,478

Customer Experiences Analyzed

The Hartford

The Hartford: Best Overall, Best for Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks first in MoneyGeek's analysis, saving most Ohio businesses an average of 16% ($92 monthly vs. the $110 benchmark). It's the top pick for seven industries, from health care and childcare to consulting and retail. Coverage includes a $300,000 sublimit for damage to rented premises and blanket additional insured endorsements for multi-client contracting.

The Hartford leads in policy management and claims handling, with fast endorsement processing and dedicated adjusters who respond within 24 hours. Its buying process ranks lower. Getting a quote requires agent involvement and takes one to three business days rather than offering instant online options.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Customer Experience

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT has a fast buying process; instant online quotes take under five minutes with no agent involvement. Google Reviews from Ohio businesses in Columbus and Cleveland confirm the speed: one Cincinnati contractor got a quote in three minutes and bought the same day. The digital portal offers instant downloads of certificates of insurance (COIs) 24/7, with no agent approval required.

Sole proprietors save the most, at 13%, while most small businesses pay premiums 12% below Ohio's average. ERGO NEXT ranks first for nine industries, with the highest savings in hospitality (33%), manufacturing (29%) and repair services (27%). But standard sublimits are lower ($100,000 for damage to rented premises vs. $300,000 at competing carriers) and endorsement options are limited; no liquor liability or professional liability bundling. BBB complaints cite slow claims resolution, including a 75-day wait for one landscaping slip-and-fall claim, and settlement fairness concerns.

Learn More: ERGO NEXT Business Insurance Review

Simply Business

Simply Business: Best for Multiple Carriers Comparisons

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business customers rank their buying experience well. It's an online broker that aggregates quotes from multiple general liability carriers into a single application. Google Reviews from Ohio businesses mention receiving three to five quotes at once; one Columbus retailer noted it saved time getting quotes from Hiscox, Chubb and others. Because Simply Business brokers policies rather than writing them directly, policy management and claims experience depend on the underlying carrier selected.

Coverage options, sublimits and endorsement availability vary by carrier across Simply Business's network, giving it less consistency than a direct carrier relationship. Simply Business is first for tech and IT businesses in Ohio at 22% savings but averages only 3% savings across most small businesses, at $107 a month.

Learn More: Simply Business Review

biBerk

biBerk: Best for Service Businesses

COMPANY HIGHLIGHTS

At $101 a month, biBerk saves most Ohio businesses 9% on average. Hospitality and repair services each top out at 27% savings. It's the top general liability pick for businesses in cleaning, fitness, pet care, real estate and recreation.

Coverage ranks seventh in the comparison: endorsements for professional liability and liquor liability are absent, and sublimits for damage to rented premises are lower than competing carriers. The buying experience is strong. Quotes take three to five minutes online and pricing breakdowns are transparent.

Learn More: biBERK Review

Thimble

Thimble: Best for Seasonal Businesses

COMPANY HIGHLIGHTS

Thimble offers on-demand coverage in Ohio. Businesses can purchase GL coverage by the hour, day, month or year and pause coverage when not working. This flexibility works well for seasonal or project-based operations, especially with online quotes that only take two to three minutes. Despite that, coverage ranks last in our analysis because of lower sublimits and limited endorsement options. 
BBB reviews citing 60- to 90-day resolution times for contested claims. However, the buying process ranks strongly with instant quotes and transparent pricing. Thimble saves Ohio businesses 7% on average with an average monthly rate of $102 monthly and ranks first for businesses in wholesale and distribution, giving them 17% savings.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for Ohio Businesses

The right general liability insurance policy depends on your business risks and the insurance requirements in your contracts. An Ohio manufacturer needs protection if a finished product later causes damage, while a subcontractor may need specific insurance documents before entering a job site. Keep those in mind when comparing quotes.

How to Choose the Best General Liability Insurance in Ohio

The right general liability insurer depends on knowing what your business needs and how providers differ on the factors that matter most. These steps help you get general liability insurance coverage that best suits your operations in Ohio.

  1. 1
    Optimize your payment and coverage structure

    Determine what coverage your Ohio business needs and how you'll pay for it. Winter weather creates slip-and-fall exposure, and contracts with health care systems or manufacturers often carry different general liability requirements. Answer these questions first:

    • What is your annual revenue, and is it consistent or seasonal?
    • Do you work on client property, in older buildings or with products?
    • Do your contracts require specific coverage limits?
    • Can you afford a higher deductible to lower your premium?
    • Does monthly or annual payment fit your cash flow better?

    Most Ohio businesses start with $1 million per occurrence and $2 million aggregate limits and pay monthly to manage cash flow. A metal fabricator may need more coverage because a failed component could damage costly equipment after installation. Annual payment may fit better if you receive steady orders and have predictable cash flow.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority

    When several insurers look the same, one clear priority breaks the tie. Ohio businesses feel different pressures. Some have to hold costs down when business slows, some need certificates fast to keep a contract moving and some carry risks a standard policy doesn't cover well. Choose what matters most to you today:

    • Affordability comes first if your cash flow is seasonal, like an Ashtabula vineyard, your retail margins are thin or you offer low-risk professional services where basic coverage satisfies your contracts. Start with affordable general liability coverage in Ohio.
    • Customer experience comes first if you need same-day certificates for Mentor construction jobs, quick policy changes when you add snow plowing or fast claims help during the November-to-March slip-and-fall months.
    • Coverage options come first if you're growing from Middletown manufacturing into regional automotive work, handling product liability as Ohio food producers face tighter rules or carrying completed operations exposure on older commercial buildings in Youngstown and Toledo.
  3. 3
    Shortlist two to three providers

    Comparing every Ohio insurer isn't necessary. Eliminate any provider that won't insure your regular work or meet your general liability requirements. Keep the two or three that best match your main priority and business size, so you have time to examine each one instead of skimming options that weren't a practical match.

  4. 4
    Double-check for dealbreakers before investing more time

    Before you dig into detailed comparisons, make sure each provider on your shortlist can really cover your business. A single dealbreaker takes a provider off the list, and you want to learn that now, not after you've switched or filed a claim. Look at four areas:

    • Industry and property eligibility: Some insurers won't write Ohio metalworking manufacturers or food producers, limit older buildings (common in Canton and Warren) or require a minimum revenue that excludes newer businesses.
    • Certificate and vendor requirements: Check that the insurer meets the standards Ohio health care systems or manufacturing supply chains set, and that it can issue a certificate the same day for a construction start or facility access.
    • Seasonal and service expansion: Make sure you can add November snow removal, hire summer hospitality staff or cover seasonal events without restrictions or steep fees.
    • Multi-county and cross-border coverage: Confirm the policy covers work across southeastern Ohio and, if you operate near a border, extends into Michigan, Pennsylvania, Kentucky or West Virginia.
  5. 5
    Compare your finalists using the same three lenses

    By now, every insurer on your list should clear your basic requirements. Compare the ones left on all three areas, using the policy details and answers you've gathered. Let your top priority break a tie, but don't let it hide a weak spot somewhere else.

    • Affordability: A farm service business in Ohio that makes most of its money during planting and harvest can't absorb a surprise renewal increase easily. Which provider explained most clearly when your price might change?
    • Customer experience: Contractors who work for hospitals or manufacturing plants often need proof of coverage before each project starts. Whose turnaround time fits those client deadlines?
    • Coverage options: Suppose you win a contract that needs higher limits or an additional insured endorsement. Which provider could change your existing policy to match?
  6. 6
    Use quotes as the final confirmation step

    After you narrow the list to one or two providers, compare business insurance quotes based on your actual business details. Quotes show pricing for your Ohio location, expose coverage gaps for seasonal or multi-county work and reveal restrictions on older buildings or specific industries. Provide accurate revenue, employee count and building age, along with details on winter services or cross-state work.

Best Small Business General Liability Insurance in Ohio: Bottom Line

The Hartford, ERGO NEXT and biBerk offer the best general liability insurance for Ohio small businesses, but the right match depends on your industry, business size and where you operate. The strongest insurers combine predictable pricing, responsive service for certificates and claims, and coverage that fits your risks. Don't choose on price alone; coverage gaps show up when you file a claim, not when you buy the policy.

Best General Liability Insurance for Small Business in Ohio Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

You'll likely need more than general liability to have the best small business insurance in Ohio. Check out the resources below to see which providers we recommend for other coverages you might need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com