


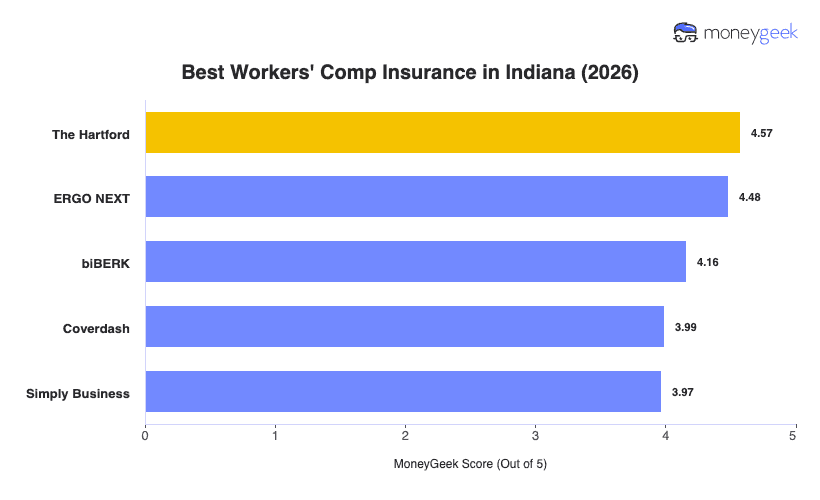
Based on my analysis, The Hartford is the best workers' comp insurer in Indiana. You can get coverage for an average monthly premium of $48, which costs the same as ERGO NEXT, your next best option. Beyond this, The Hartford provides risk-management resources to prevent claims, and also gives strong support and guidance if it still happens.
Best Workers' Comp Insurance in Indiana (2026)
With rates starting at $8 monthly, The Hartford, NEXT and biBerk offer the cheapest and best workers' comp insurance in Indiana.
With our matching tool, MoneyGeek can connect you to top Indiana workers' comp insurance providers so you can find your ideal coverage.
Select state
Updated: August 27, 2026
Advertising & Editorial Disclosure
Best Workers' Comp Insurance Companies in Indiana
| The Hartford | 4.57 | $48 | 3 | 3 |
| ERGO NEXT | 4.48 | $48 | 1 | 6 |
| biBERK | 4.16 | $57 | 8 | 8 |
| Coverdash | 3.99 | $68 | 5 | 1 |
| Simply Business | 3.97 | $69 | 2 | 2 |
MoneyGeek analyzed workers' comp insurance rates and provider performance across Indiana using small business profiles with one to four employees spanning 408 major industries. Companies earn up to five points in each category in our scoring system. We then use a weighted average of these category scores to calculate a MoneyGeek score out of five.
- Affordability (55%): Based on average payroll for the most common employee code per industry and state classification, priced per employee for a one to four employee business.
- Customer Experience (35%): Evaluates buying (20%), which covers quote access, pricing accuracy and sales support; policy management (30%), which covers payroll reporting, audits, billing and loss control; and claims (50%), which covers FNOL speed, adjuster support, medical access, wage replacement and dispute handling.
- Coverage Options (10%): Assesses coverage completeness (35%), including employers' liability and wage and medical reimbursement; policy flexibility and endorsements (25%); eligibility, state and industry breadth (20%); and policy terms, limits and exclusions (20%).

The Hartford
Best Workers' Comp Insurance in Indiana
MoneyGeek Rating
4.6/ 5
4.9/5Affordability Score
4.1/5Customer Experience Score
4.5/5Coverage Score
Average Monthly Cost
$48Claims Processing Score
4.1/5Policy Management Score
4/5Buying Process Score
4/5

ERGO NEXT
Best Indiana Workers' Comp Insurance: Runner-Up
MoneyGeek Rating
4.5/ 5
4.8/5Affordability Score
4.2/5Customer Experience Score
4.1/5Coverage Score
Average Monthly Cost
$48Claims Processing Score
4/5Policy Management Score
4.1/5Buying Process Score
4.4/5
Cheapest Workers' Comp Insurance in Indiana
The Hartford and ERGO NEXT are the cheapest workers' comp insurance providers in Indiana, but they serve different buyer profiles. The Hartford operates through independent agents and brings a long claims track record in commercial lines. ERGO NEXT is a digitally native carrier built for small businesses that want to bind coverage online without a broker conversation.
If your priority is the lowest rate and a fast online experience, ERGO NEXT is worth a close look. If you have a more complex operation or want an agent managing your policy, The Hartford's infrastructure is the better fit at the same price.
| Agriculture & Natural Resources | ERGO NEXT | $78 | $936 |
| Arts, Media & Entertainment | ERGO NEXT | $46 | $552 |
| Beauty, Body & Wellness Services | ERGO NEXT | $9 | $108 |
| Childcare Services | ERGO NEXT | $19 | $228 |
| Cleaning Services | ERGO NEXT | $54 | $648 |
| Construction & Contracting | ERGO NEXT | $112 | $1,344 |
| Consulting Services | The Hartford | $10 | $120 |
| Education | ERGO NEXT | $34 | $408 |
| Financial Services | The Hartford | $8 | $96 |
| Fitness Services | ERGO NEXT | $34 | $408 |
| Food & Beverage | ERGO NEXT | $20 | $240 |
| Healthcare & Medical | The Hartford | $22 | $264 |
| Hospitality, Travel & Tourism | The Hartford | $20 | $240 |
| Manufacturing | The Hartford | $69 | $828 |
| Marketing & Communications | ERGO NEXT | $9 | $108 |
| Nonprofit & Associations | The Hartford | $28 | $336 |
| Other Professional Services | The Hartford | $13 | $156 |
| Pet Care Services | ERGO NEXT | $30 | $360 |
| Real Estate & Property Services | The Hartford | $10 | $120 |
| Recreation & Sports | ERGO NEXT | $53 | $636 |
| Repair & Maintenance | ERGO NEXT | $35 | $420 |
| Retail & Product Rental | The Hartford | $24 | $288 |
| Tech/IT | The Hartford | $19 | $228 |
| Transportation & Logistics | ERGO NEXT | $143 | $1,716 |
| Wholesale & Distribution | ERGO NEXT | $89 | $1,068 |
How to Get the Best Workers' Comp Insurance in Indiana
Use these steps to guide you as you get workers compensation insurance. This way, you're more likely to find the best policy from the provider that matches your needs.
- 1
Confirm Indiana Coverage Requirements
Indiana requires workers’ compensation insurance when you hire your first employee. That said, exemptions apply to certain business owners and independent contractors. Construction contractors claiming exempt status need a state-issued clearance certificate rather than just calling themselves independent contractors.
- 2
Identify Your ICRB Class Codes
Indiana generally classifies the business operation, not each employee’s individual occupation. Separate codes may apply to qualifying clerical or outside sales employees. Review the Indiana Compensation Rating Bureau’s rules before splitting payroll because an unsupported lower-risk classification can be corrected during the audit.
- 3
Document Payroll, Employee Count and Claims History
Start with your prior loss runs so insurers can see the frequency and cost of earlier claims. Pair those records with projected payroll by ICRB class and an explanation of expected staffing changes. Use the same figures on every application to avoid comparing quotes built on different assumptions.
- 4
Request Quotes From Multiple Licensed Indiana Carriers
Workers’ comp pricing can vary between insurers despite using the same advisory rates. Approach several carriers and compare business insurance quotes before considering the Assigned Risk Plan. ICRB operates that plan for businesses that make a good-faith effort but cannot find coverage in the voluntary market.
- 5
Compare Quality, Not Just Price
Slow access to authorized treatment can complicate an otherwise affordable policy. Indiana allows the employer to direct an injured employee’s medical care, so examine each insurer’s provider access and claims coordination. Ask how the carrier handles referrals when an employee needs treatment outside your immediate area.
- 6
Complete the Purchase and Set Up Payroll and Audit Reporting
After binding the policy, post Indiana’s required workers’ compensation notice and follow your carrier’s payroll-reporting schedule. Build injury reporting into your process as well. You must notify the insurer within seven days after learning of an injury that causes death or requires care beyond first aid.
- 7
Review at Annual Renewal
Your premium audit may change the final cost when actual payroll or classifications differ from the original estimate. Resolve those differences before shopping for renewal quotes. Check for ICRB rate or classification updates, then confirm that the carrier’s medical providers still cover the areas where your employees work.
Best Workers' Compensation Insurance in Indiana: Bottom Line
The Hartford, NEXT and biBerk are Indiana's strongest workers' comp options for most small businesses. The right choice depends on your industry, class codes and whether you weight rate, claims performance or buying experience most heavily.

LEARN MORE ABOUT INDIANA BUSINESS INSURANCE
You'll likely need more than workers' comp in your mix when you're building your Indiana business insurance policy. If you want more resources about the top providers for other coverage types, you can find those below.
Indiana Workers' Compensation Insurance FAQ
The Hartford is the top workers' comp insurance provider in Indiana. For employers focused on cost, the cheapest options in Indiana are:
- The Hartford: $48 a month
- NEXT: $48 a month
- biBerk: $57 a month
- Thimble: $62 a month
- Nationwide: $64 a month
Indiana requires workers' comp coverage for any employer with one or more employees. The Indiana Workers Compensation Board oversees compliance and enforcement across the state. Employers who fail to carry required coverage face civil fines, stop-work orders and personal liability for all injury costs their employees incur.
Indiana's state average workers' comp cost is $63 per employee per month across all providers and industries, well below the $74 national average. State average rates vary widely by industry.
Indiana operates a competitive private market with no state fund, meaning employers purchase workers' compensation coverage directly from licensed carriers. Most Indiana employers can get coverage through the voluntary market. Employers who cannot secure voluntary market coverage may access the Indiana Workers Compensation Assigned Risk Pool through NCCI as a fallback option.
Workers' comp insurance in Indiana covers four core areas:
- Medical expenses: Covers all necessary medical treatment for work-related injuries; the Indiana Workers Compensation Board administers the fee schedule.
- Wage loss benefits: Pays temporary total disability at 66⅔% of the employee's average weekly wage, subject to the maximum weekly benefit cap set annually by the Indiana Workers Compensation Board. Verify the current 2026 maximum weekly benefit cap directly with the Board before quoting or binding coverage.
- Vocational rehabilitation: Provides retraining and placement services for workers unable to return to their pre-injury occupation.
- Death benefits: Pays burial expenses and compensation to qualifying dependents based on the deceased's average weekly wage.
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com