Best General Liability Insurance Companies in Massachusetts

Quotes from 10 insurers across 25 industries and their respective average rates helped me determine the best general liability providers in Massachusetts. Cost, however, wasn't my only basis. I also researched how each insurer deals with different businesses. That means looking at how much they ask about work to produce an accurate estimate and whether they provide resources help manage risks.

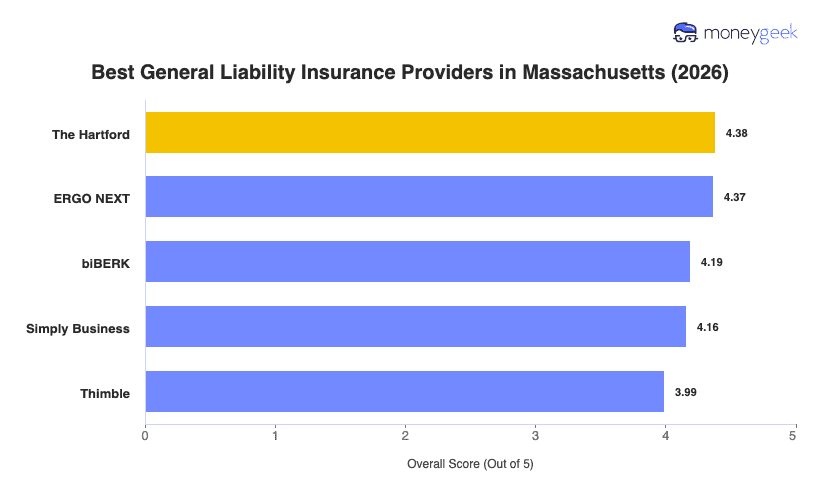
At the top of my list are:

  • Choose if you offer professional services: The Hartford
  • Choose if you prioritize customer experience: ERGO NEXT
  • Choose if your business has lower risks: biBerk
  • Choose if you want to compare carriers: Simply Business
  • Choose if you want on-demand coverage: Thimble

For our Massachusetts general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of Massachusetts's small businesses, while weighting results to ensure broader industry and location representation across Boston, Worcester, Springfield, Cambridge and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 2,000 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Massachusetts businesses consistently across different industries and regions. We then rated each company across categories of affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Massachusetts, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

2,059

Customer Experiences Analyzed

The Hartford

The Hartford: Best Overall, Best for Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks first overall in our analysis of the best general liability insurance companies in Massachusetts, with the lowest rates across 17 of 25 general industries. Professional services, tech, education and health care businesses save 14% to 31% under the state benchmark. The Hartford is also the top choice for all small businesses with employees.

The insurer leads in policy servicing and claims handling, though coverage requires working through an agent instead of buying online instantly. Massachusetts businesses say the slower buying process pays off. The Hartford's local agents in Boston and Worcester have deep familiarity with Massachusetts coverage requirements.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Customer Experience

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT leads customer experience with instant online quotes that take 10 minutes or less and same-day certificate downloads. That’s a buying process Massachusetts sole proprietors and small teams report as significantly faster than traditional agent-based models. It also has top-ranking digital policy management tools for certificate generation and account changes, though customer support relies on chat and email rather than dedicated phone reps or account managers.

It ranks second for affordability at $143 monthly, saving hands-on businesses like construction, repair, food service and hospitality 22% to 32% compared to the state benchmark. It’s also the best option for sole proprietors, giving them 14% savings. Coverage options rank lower, as its streamlined policies focus on standard endorsements rather than specialized options, and claims resulting in lower settlement fairness scores and communication gaps that two Massachusetts businesses in the Boston area specifically flagged.

Learn More: ERGO NEXT Business Insurance Review

biBerk

biBerk: Best for Lower-Risk Service Businesses

COMPANY HIGHLIGHTS

biBerk costs $156 a month, or $1,876 a year, making it the fourth most-affordable insurer for Massachusetts small businesses. It ranks third overall. Most businesses save around 9% under the state benchmark. Sole proprietors do slightly better, at 10%. Hospitality, fitness services, real estate, cleaning and recreation businesses save the most: 17% to 30% under benchmark rates.

Berkshire Hathaway backs biBerk with an AM Best A++ rating, and biBerk's endorsement options cover most common requests. Getting a policy takes little effort. Coverage can start the same day or the next. Policy management and claims handling land closer to average: BBB and Trustpilot reviews cite slow endorsement turnaround and claims service that gets the job done without excelling.

Learn More: biBerk Review

Simply Business

Simply Business: Best for Comparing Carriers

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business operates as an online broker, matching businesses with carriers instead of underwriting policies itself. Coverage options rank fourth here for one reason: actual limits, sublimits and endorsements depend entirely on which carrier ends up underwriting the policy. Businesses get instant quotes from three to five Massachusetts-licensed insurers through the platform, then manage certificates from one dashboard.

Pricing tells a different story. At $168 a month, Simply Business sits at the state benchmark, and most businesses save just 3%. Professional services, construction, agriculture and marketing businesses actually pay 11% to 16% above the Massachusetts average.

Learn More: Simply Business Review

Thimble

Thimble: Best for On-Demand Coverage

COMPANY HIGHLIGHTS

Thimble offers instant online quotes, immediate certificate downloads and flexible policy terms. Unlike traditional insurers, it offers monthly and per-project/on-demand coverage rather than annual-only policies, but endorsement options are limited to basic additional insured and waiver of subrogation. BBB and Trustpilot reviews back up lower customer ratings for claims handling, citing low settlement offers and slow processing.

Thimble is the most affordable option in only one industry: construction. Construction companies pay an average of $153 monthly and can save as much as 22%. More than half of the industries in our analysis, including hospitality, marketing, nonprofits and retail, pay 3% to 31% above state benchmarks.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for Massachusetts Businesses

An insurer may quote your business but still fall short of the requirements in your lease or client contracts. As you look for the best general liability insurance, consider what the policy will cost over time and how the provider handles the requests you’ll make after buying it.

How to Choose the Best General Liability Insurance in Massachusetts

Six steps lets you get general liability insurance that's best for your business without going through every provider on the market. Our guide makes sure you cover multiple angles and not jut go with the carrier with the lowest cost.

  1. 1
    Optimize your payment and coverage structure

    Decide how you’ll pay for coverage and how much liability protection your Massachusetts business needs. Your payment schedule affects when premiums come out of your cash flow, while your limits set the most the insurer can pay for a covered claim.

    Ask yourself:

    • Can you pay annually upfront, or do you need monthly payments to match revenue cycles?
    • Will seasonal work, such as landscaping or tourism, require flexible payment options during slow months?
    • Do clients visit your location, or do you work on their property?
    • Will contracts require proof of insurance with specific coverage limits before projects start?

    You'll spend 5% to 10% less on coverage if you pay annually, but monthly payment breaks the cost into smaller pieces. That usually makes it easier to manage seasonal revenue. Limits of $1 million per occurrence and $2 million aggregate works for most operations and let's you meet common general liability requirements. Consider higher limits if you work regularly take on large commercial contracts.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority

    Your priority depends on your cash flow, how often you need insurer support and your liability exposure. That priority also becomes your tiebreaker when providers score similarly.

    • Prioritize affordability if your margins run tight, or if you need more affordable insurer because of a past claim. This might also be a new businesses' priority, since predictable insurance costs make it easier to hire staff or expand.
    • Prioritize customer experience if you often need COIs because of vendor contracts, or frequently need to update because of seasonal staff.
    • Prioritize coverage options if your have risks beyond what a standard policy can cover, like when a client contracts require specific endorsements.
  3. 3
    Shortlist two to three providers

    Not every general liability insurer in Massachusetts is worth researching. Some won't match your business size, industry or doesn't cater to your priority area. Two or three options let you focus on the details that affect your operations.

    Look for providers that work regularly with businesses like yours and offer the payment and coverage structure you need. Confirm each finalist meets your baseline requirements before you dig into the details.

  4. 4
    Double-check for dealbreakers before investing more time

    Confirm each finalist can meet your non-negotiables before you spend more time on the details. Common examples include:

    • Certificate turnaround time: Some insurers issue certificates within 24 to 48 hours; others take a week. Construction firms and event planners often can't wait that long once a contract deadline hits.
    • Additional insured endorsements: Confirm whether the insurer can add landlords, clients or municipal agencies as additional insureds. Many Massachusetts commercial leases and public project contracts require this before work starts.
    • Payment flexibility: Ask whether monthly payments are available, or only annual billing. Seasonal businesses need payment timing that matches when revenue comes in.
    • Coverage for your industry: Not every carrier writes policies for every business type. Some won't cover restaurants with fryers or outpatient medical practices.
  5. 5
    Compare your finalists using the same three lenses

    Compare your finalists side by side before making a choice. A thorough review lets you consider all three areas to determine which provider really stands out.

    • For affordability, see how premiums change at renewal and whether payroll audits push costs up unexpectedly. Confirm payment schedules work for seasonal businesses, and note how clearly insurers explain rate adjustments.
    • When checking at customer experience, see how fast each insurer issues certificates. Also, note how easily you can adjust coverage for seasonal workers or new locations, and whether you can reach live support quickly when a claim happens.
    • Assess coverage options by checking whether each insurer offers the endorsements your contracts require. Confirm that liability limits can scale with your growth, and look for features like automatic coverage for new equipment or locations.
  6. 6
    Use quotes as the final confirmation step

    Request and compare business insurance quotes that use your actual business details, such as industry classification, payroll, revenue and location. Earlier steps relied on general estimates. Real quotes show whether your own profile triggers rate adjustments, so you don't just rely on general estimates when you decide. You'll also see coverage restrictions or eligibility issues that didn't show up during general research.

Best Small Business General Liability Insurance in Massachusetts: Bottom Line

The strongest Massachusetts general liability insurer balances competitive pricing with fast certificate turnaround and scalable coverage, rather than excelling in just one area. The Hartford, ERGO NEXT, biBerk, Simply Business and Thimble lead our rankings, but fit varies by your industry risks, employee count and how often you need policy changes. Use this framework to match coverage to your actual operations and how you'll interact with your insurer.

Best General Liability Insurance for Small Business in Massachusetts Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

The best small business insurance in Massachusetts include more than just general liability coverage. Use the resources below to see which providers we recommend for other coverage types you might need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com