Cheapest Iowa General Liability Insurance Companies

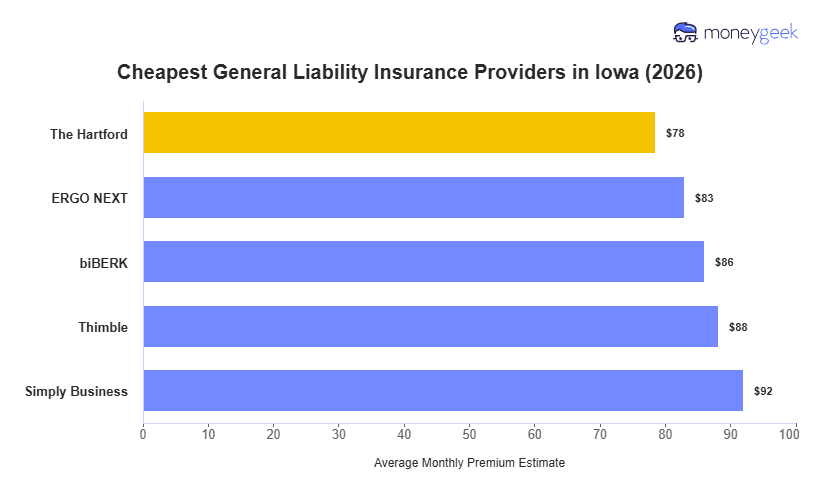
The cheapest general liability insurance companies in Iowa vary by industry, with different insurers offering the lowest rates depending on your type of business. After analyzing quotes from over 400 business types, these four consistently top my list:

  • The Hartford: Often cheapest for office-based professional services and community-focused businesses (arts and media companies, financial services firms, marketing and communications agencies, nonprofit organizations)
  • ERGO NEXT: Generally has the lowest rates for hands-on trades and service businesses (construction and contracting, repair and maintenance services, manufacturing operations)
  • biBERK: Typically most affordable for personal services and property-related businesses (cleaning services, fitness centers, pet care providers, real estate and property services, recreation and sports facilities)
  • Simply Business: Usually cheapest for retail, technology, and childcare operations

These categories serve as a starting point for identifying which insurers to compare. General liability costs vary based on your specific business activities, revenue, location within Iowa, and coverage limits. Request quotes that match your business type to find your lowest price.

The Hartford$88$1,05317%
ERGO NEXT$93$1,11213%
biBERK$97$1,1688%
Thimble$98$1,1777%
Simply Business$103$1,2383%
Coverdash$110$1,319-4%
Progressive Commercial$112$1,345-6%
Hiscox$119$1,425-12%
Nationwide$119$1,433-13%
Chubb$121$1,447-14%
The Hartford

The Hartford: Cheapest General Liability Insurance For Office-Based Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford is most often cheapest for office-based professional services and community-focused businesses, including arts and media companies, financial services firms, marketing and communications agencies and nonprofit organizations. Of the 25 general industries we analyzed, it was most affordable for 23%. Most Iowa businesses pay an average of $78 monthly for general liability coverage through The Hartford, which is 13% below the state average and saves $16 per month.

Most often cheapest for these business profiles:

  • General industries most often cheapest for: Arts, Media & Entertainment, Education, Financial Services, Healthcare & Medical, Marketing & Communications, Nonprofit & Associations
  • Employee counts most often cheapest for: 1 to 49 employees

Not a Fit? Jump To: ERGO NEXT, Simply Business or biBERK

ERGO NEXT

ERGO NEXT: Cheapest for Hands-On Trades and Customer-Facing Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT offers the lowest rates across the widest range of Iowa industries, ranking first in 146 out of 408 business types. Most businesses pay around $96 monthly for general liability insurance, which is 10% lower than Iowa's average. Businesses in hands-on trades and customer-facing operations like construction contractors, repair shops, hospitality businesses and transportation services see the biggest savings at 40%. 

Most often cheapest for these business profiles:

  • General industries most often cheapest for: Construction & Contracting, Consulting Services, Hospitality, Travel & Tourism, Manufacturing, Marketing & Communications, Nonprofit & Associations, Other Professional Services, Pet Care Services, Repair & Maintenance, Transportation & Logistics, Wholesale & Distribution

Not a Fit? Jump To: The Hartford or biBERK

biBerk

biBerk: Cheapest General Liability Insurance For Personal Services and Property Businesses

COMPANY HIGHLIGHTS

While businesses in education (firearms instructors), healthcare (EMTs, optometry practices), and skilled trades like roofing and auto repair save between 30% to 37% with biBERK, most small businesses in Iowa pay an average of $86 monthly ($1,032 annually). That’s 10% below the state average and saves $9 per month ($102 per year) compared to typical rates. It ranks cheapest for 22% of all Iowa  general industries analyzed.

Most often cheapest for these business profiles:

  • General industries most often cheapest for: Cleaning Services, Fitness Services, Other Professional Services, Pet Care Services, Real Estate & Property Services, Recreation & Sports
  • Employee counts most often cheapest for: Solo operators (0 employees)

Not a Fit? Jump To: The Hartford or ERGO NEXT or Simply Business

Simply Business

Simply Business: Cheapest General Liability Insurance For Retail, Tech and Childcare

On Simply Business site
COMPANY HIGHLIGHTS

Small Iowa businesses pay an average of $92 monthly ($1,104 annually) for general liability coverage through Simply Business, which is 4% below the state average. Getting your general from this provider saves you $3 per month compared to typical rates. 

Simply Business provides the biggest savings to food and beverage businesses (bakeries, butcher shops, delis, fast food restaurants), tech companies (video game development, web design, SaaS startups), and retail stores (vape shops, clothing stores). It ranks cheapest for only three general industries: childcare services, retail and product rental and tech/IT.

Most often cheapest for these business profiles:

  • General industries most often cheapest for: Childcare Services, Retail & Product Rental, Tech/IT

Not a Fit? Jump To: The Hartford or ERGO NEXT or biBerk

Is The Cheapest General Liability Insurance Right For Your Iowa Business?

A low-cost general liability policy can work well if your business has straightforward operations and minimal contract requirements. However, gaps in coverage may leave you paying out of pocket when something goes wrong at your Iowa location.

Before choosing based on cost of general liability alone, consider these four factors:

  • Coverage limits match what clients or landlords require so you can bid on Des Moines commercial projects or lease retail space in Cedar Rapids without scrambling for higher limits later
  • Deductibles you can actually afford when a slip-and-fall happens during an Iowa winter or a client claims property damage at their Davenport facility
  • Industry-specific add-ons available as your Ames tech startup grows into manufacturing or your Iowa City consulting firm takes on higher-value contracts
  • Responsive claims support that helps you file quickly after storm damage or a customer injury, not just low rates that look good online

Affordable coverage matters, but only if it covers your costs when claims arise. Start with a policy that meets your current contract and operational needs to find the best general liability insurer for your business. You can then adjust limits as your revenue and risk exposure grow.

How To Get Cheaper General Liability Insurance in Iowa Without Sacrificing Protection

Lowering your general liability costs in Iowa without sacrificing coverage means focusing on accurate pricing and demonstrating lower risk to insurers, not just accepting the first quote you receive or cutting limits to save money.

  • swipe icon

    Compare general liability quotes using the same limits (apples-to-apples)

    Request and compare business insurance quotes with identical coverage limits and deductibles so you can see which insurer actually charges less for the same protection. If a Des Moines restaurant requests quotes from multiple providers but gets $1 million per occurrence from one and $2 million from another, the price difference reflects coverage levels, not better value. Standardizing limits across all quotes shows you the true cost and helps you avoid buying less coverage than your contracts require.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Insurers price general liability based on your business classification code, which groups similar operations by risk level. If a Cedar Rapids coffee roastery gets misclassified as a full restaurant with seating and cooking, the premium reflects higher slip-and-fall and fire risks that don't match the actual operation. Confirming your classification is accurate can lower your rate without changing any coverage, especially if your business does lighter-risk work than the initial code suggests.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    Buy limits that match your actual risk exposure and any general liability requirements in client contracts or lease agreements, not the highest option available. An Ames consulting firm working from home with minimal client interaction may only need $1 million per occurrence, while a Sioux City landscaping crew working on commercial properties might require $2 million to meet contract terms. Paying for $5 million in coverage when your contracts cap at $2 million wastes premium dollars without providing additional coverage your Iowa business needs.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    Raising your deductible lowers your premium, but only choose an amount you can afford to pay out of pocket when a claim happens. A Dubuque furniture store with steady cash flow might save 15% to 25% annually by moving from a $500 deductible to $2,500, while a startup Iowa City tech company with tight margins may need to keep the deductible lower to avoid financial strain after a client injury claim. Calculate what you could cover from savings or operating cash before committing to a higher deductible just to cut your monthly cost.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    A business owner's policy (BOP) bundles general liability with commercial property coverage, often at a lower total cost than buying each policy separately. A Council Bluffs retail shop with inventory and equipment might save 10% to 20% on the cost of a BOP compared to purchasing standalone general liability and property policies.

    A Waterloo consulting firm working from home with minimal physical assets only needs general liability and shouldn't pay for property coverage it won't use. Compare BOP pricing against the combined cost of standalone policies to confirm bundling makes sense for your Iowa business needs.

  • takingNotes icon

    Lower your claim risk in ways Iowa insurers reward

    Iowa's competitive insurance market gives carriers room to reward businesses that control their risks. Document how you're managing the claims issues most common to Iowa businesses and share that proof when you shop for quotes or renew your policy. Many insurers reduce premiums 10% to 20% for businesses that show active risk management:

    • Document winter safety protocols for customer-facing businesses: Iowa's harsh winters create slip-and-fall risks from ice and snow accumulation. Written protocols for salting walkways, clearing entryways within specific timeframes, and training staff on weather monitoring reduce premises liability claims during peak winter months.
    • Implement equipment maintenance schedules for ag-related operations: Iowa businesses that service farming equipment or handle agricultural products deal with machinery hazards and product liability exposure. Documented maintenance logs, safety inspections, and operator training records demonstrate risk controls that insurers reward with lower premiums.
    • Train employees on proper lifting and material handling: Iowa's manufacturing, warehousing, and distribution sectors involve physical work that can lead to customer property damage or third-party injury claims. Certified training programs, documented safety meetings, and equipment checklists reduce incidents that trigger general liability claims.
    • Install security systems and document incident response procedures: Retail businesses in college towns like Iowa City and Ames deal with theft and vandalism risks that can escalate into liability claims. Monitored cameras, alarm systems, and written procedures for handling accusations help prevent fraudulent injury claims and demonstrate proactive risk management.

Affordable General Liability Insurance in Iowa: Bottom Line

There's rarely one cheapest general liability insurer for every Iowa business, since rates vary by industry, business size, location within the state, and contract requirements. The lowest premium only works when the policy covers your actual risks and meets lease or client coverage mandates. 

Use the industry breakdowns above to narrow your options, then request quotes with identical limits to see who charges least for your profile. The goal is the lowest cost that still meets your needs, not the cheapest policy regardless of fit.

Cheapest General Liability Insurance in Iowa Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

Use this page to see the cheapest providers for other coverage types you might need in your insurance mix. When you have layered risks, your insurance costs can rise quickly and these can help you keep them manageable.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com