Best General Liability Insurance Companies in Iowa

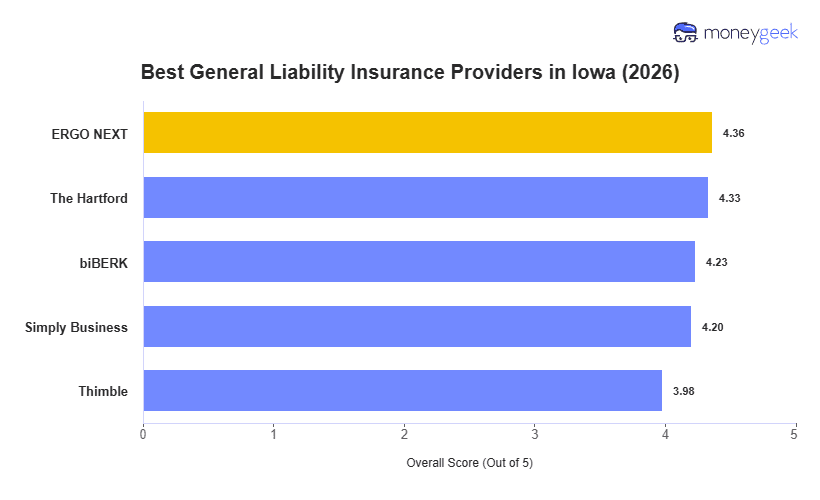
To find Iowa’s best general liability providers, I looked at how well insurers support different types of businesses. Contractors, for example, need quick updates to proof of insurance for new jobs, while professional firms need clear explanations of what GL doesn’t cover. I also compared average rates from 10 insurers using quotes with limits of $1 million per claim and $2 million total coverage to get my top picks. These are:

  • Choose if you prefer doing everyone online: ERGO NEXT
  • Choose if you're in a licensed profession: The Hartford
  • Choose if you're in service  or recreation: biBerk
  • Choose if you want to compare carrier options: Simply Business
  • Choose if you want on-demand coverage: Thimble

For our Iowa general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent a large share of Iowa's small business market, while weighting results to ensure broader industry and location representation across Polk County, Linn County, Scott County and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 900 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Iowa businesses consistently across different industries and regions. We then rated each company across categories of affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Iowa, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

948

Customer Experiences Analyzed

ERGO NEXT

ERGO NEXT: Best Overall, Best for Digital-First Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT is the top general liability insurance company in Iowa. Although it offers solid customer experience and competitive rates, coverage options are more limited. The policy offers standard $1 million/$2 million limits and common endorsements like additional insured and waiver of subrogation, but it doesn’t offer standalone EPLI, requiring Iowa businesses needing it to find a separate carrier.

ERGO NEXT quotes take under 10 minutes, and the price you see upfront is what you'll actually pay at binding. Their portal can generate a certificate of insurance instantly too. Their policy management tools work well if you're running a digital-first business, but customer support is chat and email only, no phone option, which can be frustrating if you'd rather just talk to someone. Claims handling is where they fall short: reviews mention slow adjuster communication and disputes over settlements.

In Iowa, hospitality businesses save 37%, repair and maintenance businesses save 31%, and manufacturing and construction businesses save 24% to 28%. Solo operators and micro-businesses get the best rates here compared to other insurers in our study.

Learn More: ERGO NEXT Review

The Hartford

The Hartford: Best for Professional And Regulated Industries

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks second overall in our general liability insurance study, earning top marks in affordability and coverage options that suit Iowa businesses needing more than basic protection. You’ll find coverage options  with $1 million/$2 million limits and endorsements that many online-only carriers don't, such as including EPLI and cyber liability. Iowa health care and education businesses save 31% below state benchmarks, and financial services and nonprofits save 16% to 19%. Mid-sized businesses with five to 49 employees get the most competitive rates relative to other providers in our analysis.

Trustpilot reviews praise responsive phone support, flexible billing and fair settlements from adjusters. However, quotes often require agent involvement or callbacks rather than instant online binding. An independent agent network in Iowa supports this hands-on approach, though owners who want to buy quickly may find it frustrating. 

Learn More: The Hartford Review

biBerk

biBerk: Best for Service and Recreation Businesses

COMPANY HIGHLIGHTS

biBerk, a Berkshire Hathaway company, offers competitive general liability premiums and a buying process that's easy to follow, which puts it third overall in our analysis. Users say the quote process is fast and simple, with coverage explained clearly, though policy management and claims handling land somewhere in the middle of the pack. On Trustpilot, some reviewers mention that endorsement changes and COI requests can take longer than expected, and BBB feedback on claims is mixed, with a few owners noting delays before a claim even gets started.

biBerk is the third-most affordable option for Iowa businesses. Hospitality businesses save 29%, and manufacturing, education, health care, cleaning, fitness, real estate and recreation businesses save anywhere from 18% to 26%. Solo operators get the most competitive rates of any employee size group. If your Iowa business has fairly straightforward coverage needs, biBerk is worth a look, it offers standard $1 million/$2 million limits and common endorsements like additional insured and waiver of subrogation. That said, it doesn't offer EPLI, and its add-on options are more limited than what you'd find with other carriers.

Learn More: biBerk Review

Simply Business

Simply Business: Best for Comparing Carrier Options

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business ranks fourth among Iowa general liability insurers, earning its position through reliable customer experience and broad coverage access. As a marketplace rather than a direct carrier, the platform runs quotes from multiple insurers in a single session, and policyholders cite the side-by-side comparison view as a standout feature. Coverage explanations and sales support are thinner than what direct carriers offer, though, and policy management routes through whichever carrier backs the plan. Owners who want a consistent service relationship may find that unpredictable.

Coverage availability varies by carrier. Most options include standard $1 million per occurrence/$2 million aggregate limits and common endorsements such as additional insured, but specific add-ons aren't guaranteed across all carriers. Iowa retail and tech businesses save 22% through the platform, childcare businesses save 19%, and hospitality and repair businesses save 15% to 16%. Construction, marketing and wholesale businesses pay above benchmark rates.

Learn More: Simply Business Review

Thimble

Thimble: Best for On-Demand Coverage

COMPANY HIGHLIGHTS

Flexible, short-term coverage helps Thimble place fifth overall for general liability insurance in Iowa instead of relying on traditional annual policies. Construction businesses save 21%, while manufacturing businesses cut costs by 20%, especially for project-based work that fits Thimble’s hourly, daily or monthly structure. Beauty, wellness and fitness businesses see smaller savings of 8% to 9%.

The buying experience is a clear differentiator. Users praise the app for fast quotes and transparent pricing, and the platform generates COIs instantly. Phone support is limited for complex policy changes, and BBB and Trustpilot reviews flag slow claims communication and disputes over settlement amounts. Coverage depth is narrower than direct carriers: endorsement options are limited and rented premises coverage caps at $100,000.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for Iowa Businesses

A low premium matters less if the insurer becomes difficult to reach when a contract changes or increases rates noticeably at renewal. When comparing general liability insurance in Iowa, look at what the policy will cost over time, how the provider handles requests after purchase and whether the policy fits the work you actually perform.

How to Choose the Best General Liability Insurance in Iowa

A quick quote comparison won't help you get general liability insurance that fits your business. These steps help you sort through your options, compare providers based on your priorities and confirm the right fit before you commit.

  1. 1
    Optimize your payment and coverage structure

    Before you start comparing providers, figure out exactly what your Iowa business needs.

    • Where's your liability risk really coming from: foot traffic at a storefront, job site exposure at a farm equipment dealership, or the products you make and distribute?
    • Do your contracts with wind energy contractors, food processors or commercial landlords set minimum coverage limits?
    • Can your cash flow handle annual payments, or does seasonal revenue make monthly billing the better fit?
    • Would raising your deductible lower your premium enough to make the extra out-of-pocket risk worth it?

    A Des Moines insurance agency with barely any foot traffic has nothing in common with a Newton metal fabrication shop where workers and visitors are in and out all day. Most Iowa small businesses start with $1 million per occurrence and $2 million aggregate, but your contracts or operations might change your general liability requirements.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority

    Your biggest priority right now should drive the final call when providers look similar across the board.

    • Affordability matters most for seasonal operations like a marina in Clear Lake or a custom harvesting crew that earns heavily during planting and harvest but goes quiet come winter. Stable pricing keeps your budget predictable and keeps renewal costs from hitting during your slower months.
    • Customer experience is the priority if your business depends on fast COIs, midterm changes or responsive claims handling. Subcontractors on renewable energy installations and HVAC technicians servicing rural hog confinement facilities often need same-day documentation just to stay on schedule.
    • Coverage flexibility becomes the deciding factor when your operations are complex or growing. A food processor in Cedar Rapids adding a new product line, or a window installer in Pella moving into commercial work, needs liability limits and endorsements that can scale with them.
  3. 3
    Shortlist two to three providers

    Too many options just leads to decision fatigue, not a clear answer. Narrow your list down to two or three carriers that fit your main priority and cover your baseline needs. Look for providers who actually know your industry, whether that's ag services, manufacturing or professional consulting.

    Iowa general liability costs shift depending on business size, so figure out where yours lands before you commit. Also confirm each carrier actually writes policies where you're located, since some have limited availability in rural western Iowa and smaller towns off the I-80 corridor.

  4. 4
    Double-check for dealbreakers before investing more time

    Before you get into detailed comparisons, make sure each provider on your shortlist clears your non-negotiables. Common dealbreakers for Iowa businesses include:

    • They won't cover agricultural service classifications like crop scouting or livestock hauling
    • They can't add grain terminals, ethanol plants or meatpacking facilities as additional insureds
    • Their policies exclude completed operations coverage that your commercial construction contracts require
    • They don't offer an online portal for managing certificates during busy seasons, when turnaround really matters

    A quick check at this stage saves you from wasting time on providers that won't work out anyway.

  5. 5
    Compare your finalists using the same three lenses

    Score each shortlisted provider across all three areas, not just the one you care about most.

    • Affordability: Look at their renewal rate history, how they handle audits and whether rate changes come with a clear explanation. For Iowa ag service businesses with revenue that swings throughout the year, audit-friendly billing matters just as much as the initial quote.
    • Customer experience: Check their COI turnaround times, how easy it is to make policy changes and how responsive they are with claims. Contractors working tight schedules at biofuel facilities or food processing plants need insurers who can get documentation out fast.
    • Coverage options: Look at available per occurrence and aggregate limits, what endorsements are available for Iowa industries like construction and ag services, and whether the insurer offers flexible billing or a digital way to manage certificates.
  6. 6
    Use quotes as the final confirmation step

    Once you've compared your finalists, get actual quotes to compare based on your specific business details. A real quote tells you whether the rate matches what you expected and whether the coverage actually fits what you do. Read through the quote documents carefully and watch for general liability exclusions that could leave gaps, especially if you work around livestock, service farm equipment or run heavy machinery on client sites.

Best Small Business General Liability Insurance in Iowa: Bottom Line

Iowa businesses get better long-term value by comparing more than the lowest quote. Fast policy updates, reliable COI access, stable pricing and flexible coverage terms often matter more once daily operations begin. ERGO NEXT, The Hartford, biBerk, Simply Business and Thimble lead the rankings, but the right fit still depends on your industry, company size and location. A policy built around your actual operations prevents gaps and cuts unnecessary costs.

Best General Liability Insurance For Small Business in Iowa Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

While general liability is the most common policy for owners and entrepreneurs, the best small business insurance in Iowa involves other coverages. Use the resources below to see which providers we recommend for other policies you need in your mix.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com