Cheapest Ohio General Liability Insurance Companies

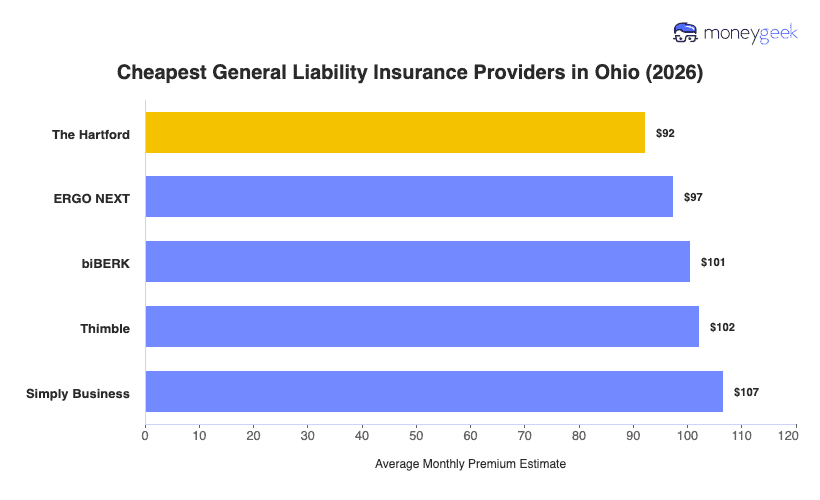
I analyzed general liability rates across 408 business types in Ohio from 10 major providers to identify which insurers most often have the lowest general liability rates for businesses with $1 million per occurrence/$2 million aggregate coverage. I'd recommend these five:

  • The Hartford: Most affordable for creative professionals and consulting services, including photography, videography, IT consulting and virtual assistant work
  • ERGO NEXT: Lowest rates for construction trades and personal services, including concrete contracting, handyman work, massage therapy and tattoo shops
  • biBerk: Cheapest for cleaning services and fitness businesses, including house cleaning, janitorial services, yoga studios and personal training
  • Thimble: Lowest rates for specialized construction and engineering, including HVAC, electrical contracting, engineering firms and excavation work
  • Simply Business: Most affordable for retail stores and tech services, including book stores, gift shops, software development and web design

Your general liability premium depends on your industry's risk profile, annual revenue, employee count and where in Ohio you operate. A small manufacturer in Akron managing equipment risks faces different exposures than a Toledo landscaping contractor dealing with lake-effect snow or a food vendor at the Ohio State Fair. Request quotes that reflect your operations and your business's seasonal challenges.

The Hartford$92$1,10616%
ERGO NEXT$97$1,16912%
biBERK$101$1,2079%
Thimble$102$1,2277%
Simply Business$107$1,2813%
Coverdash$115$1,376-4%
Progressive Commercial$115$1,384-5%
Chubb$124$1,488-13%
Hiscox$124$1,492-13%
Nationwide$124$1,494-13%

For Ohio, we kept the pricing assumptions consistent across insurers so the comparisons reflect differences in cost rather than differences in coverage.

  • Pricing data: More than 20,000 standardized estimates from 10 major insurers.
  • Business scope: 408 business types across 25 industries, with zero to 49 employees.
  • Coverage baseline: $1 million per occurrence and $2 million aggregate limits, with modeled revenue and payroll included.
  • Overall rankings: Average rates across industries for businesses with one to four employees.
  • Industry recommendations: Rates for businesses with one to four employees, keeping company size consistent.
  • Employee-size comparisons: Pricing combined across industries to show how rates change as workforce size grows.

These Ohio figures are estimates, not personalized quotes. Actual premiums can vary based on business classification, claims history, revenue or payroll, limits, deductibles and endorsements. Compare quotes using equivalent coverage terms.

Read our full methodology.

The Hartford

The Hartford: Cheapest for Creative and Consulting Professionals

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford is often the cheapest for creative professionals and consulting services across Ohio, including photographers, videographers, IT consultants and virtual assistants. Most small businesses pay around $92 monthly, 14% below the Ohio average and save $216 annually. The Hartford also offers the most savings for health care providers, such as EMTs and pharmacy technicians, who can save up to 47%.

Most often cheapest for these business profiles:

  • General industries: Arts, Media and Entertainment, Childcare Services, Consulting Services, Education, Financial Services, Health Care and Medical, Retail and Product Rental
  • Employee count: Zero to 49 employees

Not a fit? Jump to: ERGO NEXT, Thimble, biBerk or Simply Business

ERGO NEXT

ERGO NEXT: Cheapest for Construction Trades and Personal Services

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT offers the lowest rates for Ohio businesses doing hands-on work. Concrete contractors, handyman services, massage therapists and tattoo shops find the lower rates here than with most competitors. Hospitality operations also see particularly strong savings, with tour guide services and resorts cutting costs by up to 40%. Small businesses outside of these industries can still save $153 annually, typically paying around $97 monthly.

Most often cheapest for these business profiles:

  • General industries: Beauty, Body and Wellness Services, Construction and Contracting, Hospitality, Travel and Tourism, Manufacturing, Marketing and Communications, Other Professional Services, Repair and Maintenance, Transportation and Logistics

Not a fit? Jump to: The Hartford, Thimble, biBerk or Simply Business

biBerk

biBerk: Cheapest for Cleaning Services and Fitness Operations

COMPANY HIGHLIGHTS

biBerk delivers the lowest rates for cleaning companies (house cleaning, janitorial services) and fitness businesses (yoga studios, personal trainers) in Ohio. These operations save 20% to 21% compared to the state average. With a monthly rate of $101 for most small businesses, a general liability policy from biBerk cut annual expenses by $115. Repair shops see the most savings: plumbing contractors save 38%, while tire shops and auto repair operations save 30% to 36%.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Pet Care Services, Real Estate and Property Services, Recreation and Sports

Not a fit? Jump to: The Hartford, ERGO NEXT, Thimble or Simply Business

Thimble

Thimble: Cheapest for Specialized Construction and Engineering

COMPANY HIGHLIGHTS

Thimble gives its biggest discounts to railroad contractors and irrigation services, with savings of 35% to 37% on general liability coverage in Ohio. Small businesses usually pay $102 a month, 7% below the state average, for annual savings of $95.

HVAC contractors, painting contractors, insulation installers and remodeling contractors save 32% to 34% with Thimble. The carrier ranks cheapest statewide for wholesale and distribution operations as well.

Not a fit? Jump to: The Hartford, ERGO NEXT, biBerk or Simply Business

Simply Business

Simply Business: Cheapest for Retail and Tech Businesses

On Simply Business site
COMPANY HIGHLIGHTS

Most Ohio small businesses spend $107 monthly ($1,281 annually) with Simply Business, though retail stores (toy stores, gift shops, candy stores) and tech services (web design, software development, video game development) see the lowest rates.

On average, Simply Business's monthly rate is 5% lower than the state average, but certain industries enjoy savings of 29% to 34%. These include delis, butcher shops and fast food restaurants.

Not a fit? Jump to: The Hartford, ERGO NEXT, Thimble or biBerk

Is the Cheapest General Liability Insurance Right for Your Ohio Business?

Most small businesses assume general liability means comprehensive protection, but it doesn't. Budget carriers keep premiums low by excluding common risks, and they often cap coverage far below what claims actually cost. Ohio businesses often run into those gaps when:

  • Winter premises liability: A Columbus restaurant owner faced a lawsuit after a customer slipped on black ice in the parking lot during a January cold snap. Her budget policy excluded weather-related injuries, leaving her personally liable for medical costs and lost wages.
  • Automotive supply chain product defects: A Mansfield parts manufacturer found that his low-cost policy capped product liability at $100,000. When defective brackets damaged equipment at a Detroit assembly plant, the $220,000 claim left him covering the difference and nearly cost him his supplier contract.
  • Pollution and environmental cleanup: A Cleveland dry cleaner's solvent leak contaminated neighboring properties, but his cheap policy excluded pollution liability entirely. He paid $85,000 out of pocket for environmental remediation and legal fees.
  • Multi-state work coverage gaps: A Cincinnati contractor working on a project in northern Kentucky learned his budget insurer only covered Ohio operations. When a worker was injured across the state line, he had no protection and settled the claim himself.
  • Agritourism seasonal exposure: A Holmes County farm offering hayrides and pumpkin picking faced a lawsuit when a visitor fell from a wagon. The discount policy excluded farm entertainment activities, leaving the owners unprotected during their busiest season.

Read your policy exclusions before choosing the cheapest option. If your business involves manufacturing, winter operations, environmental risks, cross-border work or agricultural tourism, your coverage needs are often more complex. In these scenarios, I suggest looking for the best general liability insurance, not just the most affordable one.

How to Get Cheaper General Liability Insurance in Ohio

You can lower your premium without cutting essential coverage by focusing on accuracy, smart limits and risk reduction strategies that insurers reward.

  • swipe icon

    Compare general liability quotes using the same limits

    When you shop for general liability insurance in Pennsylvania, request the same liability limits from every carrier. A quote with $500,000/$1 million limits isn’t directly comparable to one with $1 million/$2 million limits, even if the first looks cheaper. Keep coverage amounts, deductibles and policy terms consistent, then compare business insurance quotes. That shows which insurer is actually offering the lower price for the same level of protection.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Insurers assign rates based on your industry classification code. An Akron machine shop doing precision CNC work but coded as general manufacturing pays higher premiums because general manufacturing includes higher-risk fabrication and assembly. A Cleveland food truck coded as a full-service restaurant overpays because restaurants typically have alcohol liability and dine-in premises exposure. 

    Ask your insurer to confirm your code reflects what you actually do: light assembly work prices differently than heavy industrial manufacturing, and mobile food service costs less than brick-and-mortar restaurants with seating.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    Ohio manufacturers supplying automotive plants usually need $2 million in coverage to meet tier-one supplier requirements, while construction contractors working on commercial projects in Columbus or Cleveland often face minimums of $1 million from general contractors and property owners. Buying $500,000 when your general liability requirements mandate $1 million forces you to upgrade mid-term at higher rates. 

    Review your client contracts, supplier agreements and commercial lease terms before setting general liability limits so you meet those requirements from the start rather than paying to increase coverage when you discover the gap.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    Higher deductibles cut premiums but create immediate out-of-pocket costs when you file a claim. Moving from a $500 to $2,500 deductible saves 15% to 25% annually, which is big savings for a Cincinnati metal fabricator with consistent revenue and strong reserves. But the same increase puts a Holmes County farm market at risk if a customer injury happens during peak pumpkin season when cash is already tied up in inventory and seasonal labor. Before raising your deductible, confirm you can cover that amount during your slowest revenue month without affecting payroll or operations.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    A business owner's policy (BOP) bundles general liability with property coverage and often saves 15% to 20% compared to buying each separately. This works well for businesses with physical locations and inventory, like a Findlay retail shop or Medina bakery. However, it doesn't make sense for mobile businesses or service providers with little or no property exposure. The cost of a BOP might now be worth the savings if it means getting coverage your business doesn't need.

  • takingNotes icon

    Lower your claim risk in ways Ohio insurers reward

    Ohio insurers reward businesses that reduce their claims risk through documented safety and operational controls. These practices impact how carriers price your renewal:

    • Maintain year-round premises safety with documented snow removal and ice melt schedules for winter months when slip-and-fall claims peak
    • Implement visitor safety programs for agritourism operations, including signed waivers and clear pathway maintenance during harvest season
    • Document equipment inspections for manufacturing operations, especially businesses supplying automotive plants, where defects trigger supply chain claims
    • Establish driver safety policies and vehicle maintenance logs for businesses operating across state lines into Michigan, Pennsylvania, Kentucky, Indiana, and West Virginia
    • Create written project scope agreements for contractors working in historic districts where preservation requirements create additional liability exposure

    Carriers review these risk management practices during underwriting and renewals. Businesses that demonstrate active risk reduction through documentation and training specific to Ohio's industrial economy, seasonal weather risks and multi-state commerce typically receive better rates than those without formal safety programs.

Affordable General Liability Insurance in Ohio: Bottom Line

The cheapest insurer for a Youngstown metal fabricator serving Detroit auto plants differs from what a Lancaster farm offering fall hayrides needs or what a Columbus tech startup pays. Ohio's economy includes manufacturing, agriculture and services, so no single carrier offers the lowest rates for all industries.

Identify insurers that price your sector lowest, then confirm the coverage handles Ohio realities such as winter premises liability, supply chain product exposure and projects crossing into Pennsylvania or Michigan. Affordable coverage protects you against your actual risks, not just your premium.

Cheapest General Liability Insurance in Ohio Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

A provider that has the cheapest average premium can help you manage your insurance costs, especially when you need more than just general liability in your policy mix. See which affordable carriers we recommend from our analyses.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com