Cheapest North Carolina General Liability Insurance Companies

Finding the cheapest general liability insurance in North Carolina starts with knowing which providers consistently offer the lowest rates for your industry. My analysis for quotes for 25 general industries showed these results:

  • The Hartford: Cheapest for creative professionals and health care providers, including photography, videography, art galleries and dental practices
  • ERGO NEXT: Lowest rates for construction trades and food service businesses, such as general contractors, HVAC contractors, restaurants and food trucks
  • biBerk: Most affordable for cleaning services and fitness facilities, including house cleaning, janitorial services, gyms and yoga studios
  • Simply Business: Cheapest for retail stores and specialty food businesses, such as clothing stores, bookstores, bakeries and daycare centers
  • Thimble: Best rates for general construction and engineering services, including electricians, engineering firms and land surveyors

Your final general liability premium scales with factors like annual revenue, employee count and the physical risks your work involves. Treat these sweet spots as a starting point, not a guarantee. Compare quotes from multiple insurers to find your actual lowest rate.

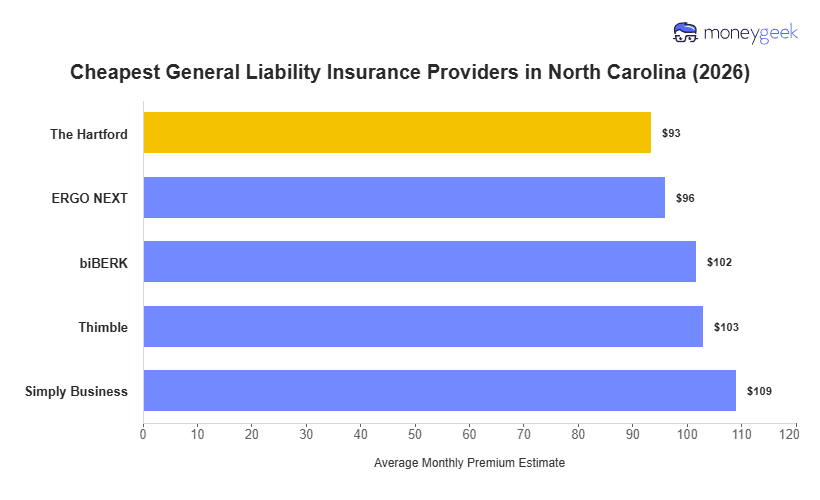
The Hartford$93$1,12116%
ERGO NEXT$96$1,15214%
biBERK$102$1,2199%
Thimble$103$1,2378%
Simply Business$109$1,3082%
Progressive Commercial$117$1,399-4%
Coverdash$117$1,406-5%
Hiscox$126$1,512-13%
Nationwide$126$1,513-13%
Chubb$128$1,539-15%

For North Carolina, we used a consistent policy setup so insurer prices could be compared on the same basis: $1 million per occurrence and $2 million aggregate limits, with modeled revenue and payroll included in each estimate. The analysis covers more than 20,000 standardized estimates from 10 major insurers, 408 business types and 25 industries, with businesses ranging from zero to 49 employees.

We then applied the data differently depending on the question. Overall rankings use average rates across industries for businesses with one to four employees. Industry recommendations keep that employee range fixed, while employee-size comparisons combine rates across industries to show how pricing changes as headcount grows. These North Carolina figures are estimates, not personalized quotes, so actual premiums can vary based on classification, claims history, revenue or payroll, limits, deductibles and endorsements.

Read our full methodology.

The Hartford

The Hartford: Cheapest for Creative and Health Care Professionals

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford is most often the cheapest for creative professionals and health care providers in North Carolina. Photographers, videographers, art galleries and dental practices see some of the strongest savings. Small businesses pay an average of $93 monthly, which is 13% below the state average and saves $219 annually. The Hartford offers the lowest rates across a wider range of industries than any other insurer, ranking as the cheapest for 24% of all North Carolina business types.

Most often cheapest for these business profiles:

  • General industries: Arts, Media and Entertainment, Education, Financial Services, Health Care & Medical
  • Employee count: Zero to 49 employees

Not a fit? Jump to: ERGO NEXT or Thimble or biBerk or Simply Business

ERGO NEXT

ERGO NEXT: Cheapest for Construction and Food Services

On ERGO NEXT's site
COMPANY HIGHLIGHTS

Most small businesses in North Carolina spend around $96 monthly with ERGO NEXT, for annual savings of $189. ERGO NEXT ranks the cheapest for construction trades and food service businesses across North Carolina. General contractors, HVAC contractors, restaurants and food trucks usually have the biggest rate advantages. Capturing the lowest rates in 39% of all business categories, ERGO NEXT ranks cheapest for more North Carolina industries than any competitor.

Most often cheapest for these business profiles:

  • General industries: Childcare Services, Construction and Contracting, Consulting Services, Food and Beverage, Hospitality, Travel and Tourism, Manufacturing, Marketing and Communications, Other Professional Services, Pet Care Services, Repair and Maintenance, Tech/IT, Transportation and Logistics

Not a fit? Jump to: The Hartford or Thimble or biBerk or Simply Business

biBerk

biBerk: Cheapest for Cleaning and Fitness Businesses

COMPANY HIGHLIGHTS

biBerk ranks cheapest across four major industry categories in North Carolina, accounting for 19% of all the lowest rates statewide. Cleaning services and fitness facilities get the biggest savings, including house cleaning operations, janitorial services, gyms and yoga studios. Small businesses pay $102 a month on average, 10% below the state average, for annual savings of $121.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Real Estate and Property Services, Recreation and Sports

Not a fit? Jump to: The Hartford or ERGO NEXT or Thimble or Simply Business

Simply Business

Cheapest for Retail and Specialty Food Operations

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business ranks first across two major industry categories in North Carolina, capturing 6% of all lowest rates statewide. Retail stores and specialty food operations get the best deal, including clothing stores, bookstores, bakeries and daycare centers. Small operations with one to four employees pay $109 a month on average, 4% below the state average, for annual savings of $33.

Most often cheapest for these business profiles:

  • General industries: Beauty, Body & Wellness Services, Retail & Product Rental

Not a fit? Jump to: The Hartford or ERGO NEXT or Thimble or biBerk

Thimble

Cheapest for Construction and Engineering Services

COMPANY HIGHLIGHTS

Tree service companies, arborists, electricians and roofing contractors get the lowest rates with Thimble, 4% of business types across North Carolina. Small operations pay about $103 per month, 3% below the state average, and save $104 annually. 

Most often cheapest for these business profiles:

  • General industry: Wholesale and Distribution

Not a fit? Jump to: The Hartford or ERGO NEXT or biBerk or Simply Business

Is the Cheapest General Liability Insurance Right for Your North Carolina Business?

General liability policies cover basic risks well, but they may not cover common risks for North Carolina businesses. Where you operate and how you work determine whether the lowest rate covers your actual risks.

  • Slow certificate delivery: State projects need proof of insurance within 48 hours, but some budget insurers take four to six days.
  • Lease coverage requirements: Charlotte and Raleigh landlords often require $2 million total coverage; lower-cost policies may cap at $1 million or charge $100 to $175 for landlord endorsements.
  • Seasonal business limits: Outer Banks and mountain retailers close for months, but many cheap carriers won't pause coverage or charge fees when you try.
  • Endorsement restrictions: Contractors add three to five insured parties per job, but budget options often limit you to two or three total.

Instead of focusing on cost, consider looking for the best general liability insurance policy for your business if you have more complex coverage requirements. These include companies with leases, public contracts, seasonal schedules or changing project needs. A cheap GL policy may save money upfront but leave you with coverage gaps that'll cost more to fix later.

How to Get Cheaper General Liability Insurance in North Carolina

You can lower your general liability costs in North Carolina without losing the coverage your lease, contracts or lender requires. These six strategies help North Carolina businesses cut premiums while keeping the coverage their operations actually need.

  • swipe icon

    Compare general liability quotes using the same limits

    Price differences only matter when you're comparing business insurance quotes with identical coverage. A $500 annual quote with $1 million per occurrence looks cheaper than $650, but if the higher quote includes the $2 million your Raleigh landlord requires, you're comparing different products. Request identical limits, deductibles and terms from every insurer so price gaps show the carrier's actual rates, not coverage you'll need to add later.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Insurers use classification codes to set your base rate, and getting coded wrong can raise your premium 30% to 50%. A Greensboro plumber mistakenly listed as a general contractor pays steeper rates because general contractors handle riskier work like framing and excavation, jobs that the plumber never performs. Verify your insurer codes you for the actual services you provide, not a broader category that includes work you don't do.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    Buying higher limits than what your general liability requirements mandate costs more without adding useful protection. An Asheville web developer working from home with no lease requirements might pay $300 extra annually for $2 million aggregate coverage when $1 million adequately covers the risk. Check what your commercial lease, client contracts or lender mandate, then add enough coverage to protect your assets if a claim hits your policy limit.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    Raising your deductible from $500 to $2,500 can cut your annual premium 10% to 15%, but only works if you can afford the higher out-of-pocket cost when you file a claim. A Charlotte catering company with $10,000 in savings might save $150 yearly with a $2,500 deductible, while a new Raleigh food truck with tight cash flow can't cover that amount after a kitchen fire claim. Choose the highest deductible you could pay immediately without hurting day-to-day operations, and pay annually instead of monthly to avoid installment fees that add 5% to 8% to your total.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    Combining general liability and property coverage in a business owner's policy (BOP) can save 15% to 25% compared to buying each separately, but only if you actually need both. A Fayetteville gym with $50,000 in equipment benefits from a BOP covering liability and property damage, while a Winston-Salem bookkeeper working from home pays for property protection they don't use. Compare the cost of a BOP against standalone general liability to confirm bundling actually reduces your total premium instead of adding coverage you won't claim.

  • takingNotes icon

    Lower your claim risk in ways North Carolina insurers reward

    Insurers set rates based on how likely you are to file claims, and showing you actively prevent accidents can lower your premium. North Carolina businesses can reduce their risk profile through safety practices that insurers reward:

    • Construction and trades: Install jobsite barriers, run daily safety meetings and keep equipment inspection logs, which is critical for Charlotte contractors and coastal builders preparing for hurricane season.
    • Restaurants and hospitality: Add slip-resistant flooring, post visible safety signs and train staff on food handling to prevent slip-and-fall and contamination claims.
    • Retail stores: Inspect your property weekly, maintain parking lot lighting and document all incidents, even minor ones that don't turn into claims.
    • Service providers: Verify driver records yearly, require vehicle maintenance logs and carry equipment in secure cases when visiting client sites.

    Share these safety records with insurers when you request quotes. Training logs, maintenance schedules and inspection checklists show you run a lower-risk operation worth better pricing.

Affordable General Liability Insurance in North Carolina: Bottom Line

There's no single cheapest general liability insurer for every North Carolina business. Your industry, team size and location across the state shape which carriers price your coverage lowest. The most affordable option only works when it provides financial protection for your actual risks and meets any commercial lease or client contract requirements. 

Use the provider reviews on this page to see which insurers run cheapest for businesses like yours, then compare quotes using the same coverage limits to confirm who offers the lowest rate. The goal is finding cheap coverage that still covers the costs your operations face and satisfies your contractual needs.

Cheapest General Liability Insurance in North Carolina Chart
mglogo icon

MONEYGEEK EXPERT TIP

You could leave your North Carolina business with coverage gaps if you only have general liability in your insurance mix. But you should your expect your total insurance cost to go up the more coverages you get. I've put a list of resources together showing which providers offer the cheapest average rates for other coverage types you might need to help keep costs manageable.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com