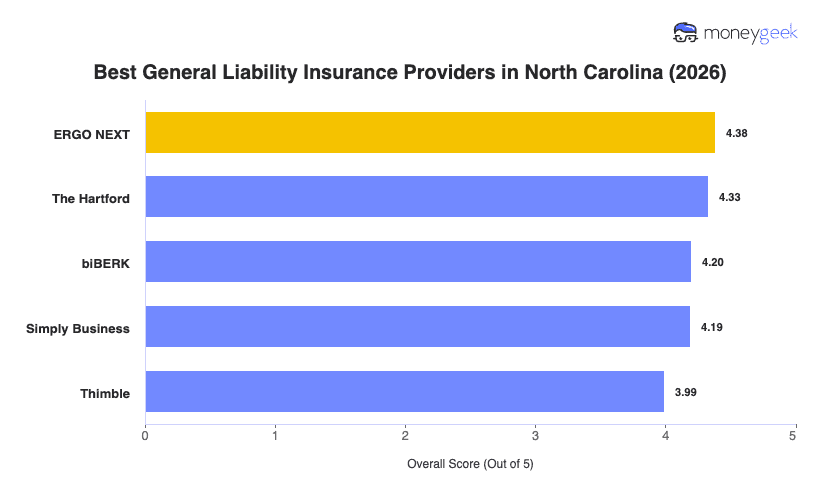
Best General Liability Insurance Companies in North Carolina

To determine the best general liability providers in North Carolina, I compared average rates from 10 insurers using the same $1 million per claim and $2 million total limits. Their GL policies also had to suit a wide range of businesses, including those common in the state, like construction and hospitality. Then I checked if insurers help you confirm coverage when your operations change and let you report claims outside regular business hours.

My top recommendations are:

  • Choose if you do a lot of hands-on work: ERGO NEXT
  • Choose if you want to save on premiums: The Hartford
  • Choose if you're in a service-based industry: biBerk
  • Choose if you want to have multiple carrier choices: Simply Business
  • Choose if you want on-demand coverage: Thimble

For our North Carolina general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of North Carolina's small businesses, while weighting results to ensure broader industry and location representation across Charlotte, Raleigh, Greensboro, Durham and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 3,200 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve North Carolina businesses consistently across different industries and regions. We then rated each company across affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to North Carolina, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

3,250

Customer Experiences Analyzed

ERGO NEXT

ERGO NEXT: Best Overall, Best for Hands-On Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT tops customer experience rankings with its fully digital platform that North Carolina business owners use to get quotes in under 10 minutes and secure same-day coverage. Customer reviews say that no phone calls are required during signup, and the mobile app generates certificates of insurance for job sites within seconds. Affordability is another strength, with a monthly average of $96 per month for most small businesses. That saves North Carolina business owners around 14% compared to the state benchmark.

ERGO NEXT ranks lower for coverage options. It uses standard ISO forms, which fit straightforward operations but can limit businesses that need specialized endorsements. Its claims handling is also less competitive. North Carolina landscapers and contractors report settlement disputes, slow adjuster communication and resolution times that sometimes run past three months.

Learn More: ERGO NEXT Business Insurance Review

The Hartford

The Hartford: Best Cheap General Liability Insurance

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford has North Carolina's lowest rate at every employee count, pricing at $93 a month, 16% under the state average. Professional services buyers save the most, with education businesses paying 30% under the state average. Health care businesses follow closely at 28% under.

Agents can add blanket additional insured and waiver of subrogation endorsements to a policy. Primary/noncontributory language is also available. Agent dependency is where The Hartford's customer experience score drops. Charlotte and Greensboro contractors report quote turnaround from same-day to five business days; competitors turn quotes around instantly online.

Learn More: The Hartford Business Insurance Review

biBerk

biBerk: Best for Service-Based Businesses

COMPANY HIGHLIGHTS

biBerk offers the lowest rates in North Carolina for cleaning services, real estate and property services, and fitness operations, about 20% under the state average. Its general liability policy averages $102 a month, 9% below the state average. Customer experience ranks fourth. Online quotes take 10 to 15 minutes and require no agent.

Coverage ranks seventh. biBerk offers standard ISO forms and common endorsements, including additional insured, waiver of subrogation and hired and non-owned auto liability. Its online-only quoting shows less endorsement detail upfront than agent-based competitors do. Buyers must contact support to verify blanket additional insured or primary and noncontributory language.

Learn More: biBerk Review

Simply Business

Simply Business: Best for Carrier Choice

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business's customer experience ranking is based solely on the buying process. The platform lets North Carolina businesses compare quotes from multiple carriers, including Hiscox, Travelers and CNA, in one application that takes 10 to 15 minutes. Coverage options rank fourth because they vary by carrier partner. The platform does let buyers filter for specific endorsements during the quote process.

This broker model creates variability after purchase. Policy changes and endorsements route to the underlying carrier rather than to Simply Business directly. Claims experiences also differ depending on carrier quality. North Carolina small businesses spend an average of $109 a month, 2% under the state average. Marketing and communications businesses pay 15% above the state average. Retail operations, by contrast, save 20%.

Learn More: Simply Business Review

Thimble

Thimble: Best for On-Demand Coverage

COMPANY HIGHLIGHTS

North Carolina small businesses pay around $103 a month for general liability coverage from Thimble, 8% under the state average. Wholesale and distribution businesses see the most value, saving 18%. Construction operations save 22%. Coverage options rank last, even with Thimble's on-demand model. Flexible coverage brings its own complications: some endorsements are restricted by hourly activation periods, and claims disputes come up over whether coverage was active at the time of the incident.

Customer experience declines at each stage. Buying ranks second: instant quotes and 60-second coverage activation through the mobile app. Policy management ranks fourth. The pay-per-use billing model suits project-based operations but confuses businesses that need continuous coverage. Claims handling ranks seventh. North Carolina businesses report slow communication, lower-than-expected settlements and disputes over coverage gaps tied to on-demand usage periods.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for North Carolina Businesses

A North Carolina furniture maker may worry about problems that appear after a product is delivered, while a contractor may need proof of higher limits before entering a job site. The right general liability policy addresses your coverage needs without becoming unexpectedly expensive after you buy.

How to Choose the Best General Liability Insurance in North Carolina

Decide what your North Carolina business needs most from a general liability insurer, then see where providers really differ. Working through it in order narrows the field and helps you get general liability insurance coverage that fits how you operate.

  1. 1
    Optimize your payment and coverage structure

    North Carolina businesses should balance coverage limits against payment timing that fits their cash flow. Ask yourself:

    • Do customers visit my location, or do I work at client sites?
    • Do I sell products, provide services or both?
    • Can I pay annually upfront, or do I need monthly installments?
    • Do I lease commercial space or operate from home?

    Most businesses need $1 million per occurrence and $2 million aggregate, which satisfies most general liability requirements, and most pay monthly. Your situation may call for something different. A Charlotte event planner managing festivals needs higher limits than a Durham freelance designer, and a Greensboro manufacturer with steady cash flow saves by paying annually to avoid installment fees.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority

    Figure out what your business needs most right now. Maybe cash flow is tight, or you're dealing with contract requirements in several North Carolina counties, or you're taking on riskier work. That need decides it when two providers look about the same.

    If you're a new business with thin margins, or your income rises and falls with the seasons (think Outer Banks tourism or holiday retail), put affordability first. Steady monthly costs matter more than extra features when you're growing on your own money.

    If you need same-day certificates to meet contract deadlines, or clients often ask for additional insured endorsements, put customer experience first. Contractors, event planners and consultants working across counties need fast answers on policy changes and documents.

  3. 3
    Shortlist two to three providers

    Evaluating every available insurer wastes time. Six or more carriers, with calls, portal tests and policy comparisons for each, can take weeks.

    Limit your shortlist to two or three North Carolina insurers that match your priority and know your business type, whether you run a contracting crew in Wilmington, a retail shop in Greensboro or an event planning service in Asheville. Then compare them on county coverage, industry knowledge and response speed.

  4. 4
    Double check for dealbreakers before investing more time

    Before you dig into any provider, check your non-negotiables. A dealbreaker you find after committing costs time and money. Picture a Greensboro contractor who learns too late that the insurer won't add required additional insureds, or a Wilmington caterer who finds out after signing that liquor liability isn't offered. Ask each shortlisted insurer about:

    • County coverage: Does it serve every area where you operate?
    • Certificate turnaround: Ask about same-day or 24-hour delivery, especially if you bid on Triangle-area municipal contracts or have clients who want proof of coverage fast.
    • Required endorsements: Additional insured if you work Outer Banks event venues, hired and non-owned auto if you run deliveries, liquor liability if you're adding alcohol service in Asheville.
    • Policy management: Can you update coverage online? It helps when you're growing from Winston-Salem into Fayetteville and can't wait for an agent to call back.
    • Industry restrictions: Make sure the carrier writes your business type. Some turn away coastal restaurants, high-volume manufacturers and businesses working across several North Carolina markets.

    Catching these now keeps you from starting over after you've requested quotes.

  5. 5
    Compare your finalists using the same three lenses

    Cheap but slow with certificates, or great service but unpredictable renewals: either way, one strong area doesn't carry you. Line up your shortlisted providers on all three and see how each one holds up.

    • Affordability: Look at how renewal pricing works. Do premiums move with claims or growth? How does the insurer let you know about a rate change?
    • Customer experience: See how quickly certificates come back and how simple it is to add endorsements, say when a Raleigh client wants additional insured status. Then contact the insurer yourself and time the reply, so you aren't learning how slow it is during a same-day update or after a slip-and-fall at your Charlotte location.
    • Coverage options: Compare limits (some Triangle businesses need $2 million aggregate for commercial contracts) and how flexible the endorsements are. Find out if the insurer offers umbrella coverage for the day your Wilmington operation outgrows standard limits.

    Providers that do well in all three mean fewer tradeoffs for you.

  6. 6
    Use quotes as the final confirmation step

    Describe your business accurately to each finalist and request the same limits and endorsements. Compare business insurance quotes to see each insurer's price for the same protection. If you serve festivals or plan to add a location, confirm the quote reflects those plans and not a generic small-business profile.

Best Small Business General Liability Insurance in North Carolina: Bottom Line

ERGO NEXT, The Hartford, biBerk, Simply Business and Thimble are the top five for North Carolina. Price gets you in the door, but it's not the whole picture. Renewal stability, how fast the insurer issues certificates and policy change support all affect your day-to-day experience. A cheap policy from a carrier that can't turn around a certificate before a job starts costs you work.

Best General Liability Insurance for Small Business in North Carolina Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

You'll need more than general liability if you want more extensive financial protection. I've put together these resources below so you can see our recommended providers for other coverages you might need to include in your North Carolina small business insurance.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com