

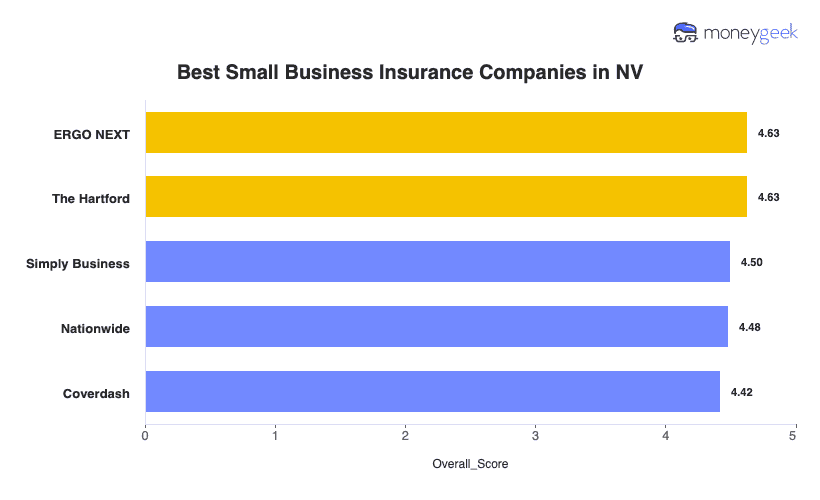
ERGO NEXT and The Hartford tie as the best small business insurance companies in Nevada, each earning a MoneyGeek score of 4.63 out of 5 and averaging $102 per month. ERGO NEXT makes more sense if you regularly need certificates of insurance or want to manage policy changes online. The Hartford offers more hands-on support when you have questions about coverage or need help with a claim. If you'd rather compare policies from multiple insurers before choosing one, Simply Business offers another route at $110 per month.
Best Small Business Insurance in Nevada
After analyzing cost, service quality and coverage, I found that ERGO NEXT, The Hartford and Simply Business are the best business insurers in Nevada.
MoneyGeek helps you compare insurers and uses details such as your state and industry to narrow down providers that fit your business.
Ready to buy? Use the tool below to find insurers that match your Nevada business and the coverage you need.
Select state
Safe & SecureVerified and VettedTrusted Brands
Updated: November 4, 2026
Advertising & Editorial Disclosure
Best Small Business Insurance Companies in Nevada
| ERGO NEXT | 4.63 | $102 | 1 | 2 |
| The Hartford | 4.63 | $102 | 2 | 3 |
| Simply Business | 4.50 | $110 | 5 | 1 |
| Nationwide | 4.48 | $116 | 2 | 4 |
| Coverdash | 4.42 | $115 | 6 | 2 |
| biBERK | 4.40 | $119 | 2 | 5 |
| Thimble | 4.34 | $107 | 8 | 5 |
| Progressive Commercial | 4.33 | $113 | 7 | 5 |
| Hiscox | 4.28 | $122 | 4 | 6 |
| Chubb | 4.27 | $134 | 3 | 4 |
Note: Don’t treat the Nevada averages as a prediction of what your business will pay. They’re built from a fixed comparison profile in MoneyGeek’s methodology: two employees evaluated across 79 major industries. The value here is seeing how coverage costs stack up against one another. Your insurer will calculate your actual rate from the details of your own operation.

The Hartford
Best and Cheapest Nevada Business Insurance
MoneyGeek Rating
4.6/ 5
4.6/5Affordability
4.6/5Customer Experience
4.7/5Coverage Options
Average Monthly Cost of General Liability Insurance
$103This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
$79This rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Survey: Claims Process
4.5/5 (1st)Our Survey: Agent Service
4.7/5 (1st)

ERGO NEXT
Best Nevada Customer Experience
MoneyGeek Rating
4.6/ 5
4.5/5Affordability
4.7/5Customer Experience
4.8/5Coverage Options
Average Monthly Cost of General Liability Insurance
$100This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
$78This rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Survey: Digital Experience
4.8/5 (1st)Our Survey: Likely to be Recommended to Others
4.8/5 (1st)

Simply Business
Best Commercial Coverage Options in Nevada
MoneyGeek Rating
4.5/ 5
4.5/5Affordability
4.2/5Customer Experience
4.9/5Coverage Options
Average Monthly Cost of General Liability Insurance
$109This rate is for small businesses with two employees across 79 major industries or business types and focus solely on general liability policies.Average Monthly Cost of Workers' Comp Insurance
$81This rate is for small businesses with two employees across 79 major industries or business types and focus solely on workers' comp policies.Our Research: Digital Experience
4.5/5Our Survey: Service Quality
4.0/5
How to Get the Best Cheap Small Business Insurance in Nevada
Nevada business owners face wildfire seasons forcing operational shutdowns, unexpected desert flooding and contractor liability rules stricter than neighboring states. Learning how to get business insurance in Nevada means addressing coverage gaps that price shopping alone won't solve.
- 1
Assess what coverage your Nevada business actually needs
Start with the work you do and what could go wrong. requires workers' compensation insurance once you hire your first covered employee. If you use vehicles for work, check whether you need commercial auto insurance rather than relying on your personal policy.
Your location can change what you need, too. A business operating in a flood-prone area may need separate flood insurance because standard commercial property policies generally exclude flooding. If you lease a storefront in Las Vegas, your landlord may also require general liability coverage before you move in.
Read More: How Much Business Insurance Do I Need?
- 2
Get quotes from affordable providers with strong customer ratings
Give each insurer the same details about your business so the quotes reflect similar risks. Be specific about the work you do, especially if you're a contractor. Some insurers won't cover certain trades, which narrows your options before price even comes into play.
Ask for the same liability limits and deductibles before comparing business insurance quotes. Then check what's actually included. A cheaper quote won't save you much if it leaves out coverage another insurer provides.
- 3
Check insurer reliability before choosing based on price
I'd look beyond the premium to see how the insurer handles claims and policy questions. Can you report a claim online? Will someone be available to explain what happens next? Those details become more important when you're dealing with property damage or an interruption to your business.
You can also use the Nevada Division of Insurance to verify that an insurer is authorized to operate in the state. If wildfire or storm damage affects several businesses at once, you'll want an insurer that keeps you informed while handling your claim.
- 4
Cut insurance costs without reducing your protection
You don't necessarily need to lower your coverage limits to pay less. I'd check these options first:
- See whether bundling saves money: A business owner's policy (BOP) combines general liability and commercial property insurance. It may cost less than buying both separately.
- Ask about discounts: Insurers may offer savings for security systems or documented workplace safety practices.
- Compare payment options: Paying annually could help you avoid monthly billing fees.
- Choose a deductible you can afford: A higher deductible may lower your premium, but you'll pay more yourself if you have a covered claim.
The idea is to bring down your business insurance costs without taking on losses you can't comfortably pay yourself.
- 5
Secure coverage that meets client contract requirements
Nevada contracts can require more insurance than state law does. For example, a Las Vegas venue may ask contractors for $1 million in general liability coverage before allowing them on-site. A commercial landlord might also require you to add the property owner as an additional insured, giving them certain protections under your policy.
Review these requirements before buying so you know which insurers can meet them. You'll likely need a certificate of insurance (COI) to prove you have coverage. If the contract also calls for an additional insured endorsement, make sure your insurer adds it to the policy. The certificate alone won't do that.
- 6
Change your coverage when the business changes
Your original policy may no longer fit once your operations change. Say you started with a storefront in Las Vegas and now plan to open another in Reno. You'll need to tell your insurer about the new location so it can account for the additional property and any changes in liability exposure.
The same goes for taking on new types of work or adding company vehicles. I'd review your policy before making those changes rather than finding out after a loss that your existing coverage doesn't apply.
Best Business Liability Insurance in Nevada: Bottom Line
ERGO NEXT and The Hartford tie as Nevada's best small business insurance providers, both scoring 4.63 out of 5 and averaging $102 per month. I'd go with The Hartford if you want someone to help with policy questions or claims, while ERGO NEXT is a better fit for contractors who regularly need proof of insurance and prefer handling paperwork online. Simply Business is also worth considering if you need to compare insurers that can meet specific client contract requirements. Ultimately, the right choice depends on what your business needs covered and how you prefer to manage your insurance.

LOOKING FOR THE BEST INSURANCE FOR A SPECIFIC COVERAGE TYPE?
We've done analysis for several coverage types to help you find the best business insurance provider for each one. The resources below show our top recommendations.
Business Insurance in Nevada: FAQ
Small business owners in Nevada often have questions about choosing the right business insurance. We answer the most common concerns below:
Nevada law sets part of the floor for you. Workers’ comp requirements applies once you hire, and company vehicles need commercial auto that meets Nevada's minimum limits. After that, the real question is what someone else expects from you. A Las Vegas landlord may require general liability insurance before you get the keys, and a client contract can set higher limits than the state does. I’d review those obligations before adding optional coverage.
The cost of Nevada business insurance depends mainly on the coverages you include in your insurance bundle. Per policy, you can expect to spend:
- General liability: $131 per month or $1,572 per year
- Workers' comp: $97 per month per employee or $1,169 per year per employee
- Commercial auto: $167 per month per vehicle or $2,000 per year per vehicle
- Commercial property: $127 per month or $1,525 per year
- Professional liability: $61 per month or $737 per year
- Cyber insurance: $92 per month or $1,110 per year
The best question to ask when building your starter bundle is “Which loss could hurt this business fastest?” For a small Las Vegas hospitality business, I’d probably put general liability and property coverage near the top because customer traffic and a physical location create immediate risks. A Henderson tech company may build differently, prioritizing professional liability or cyber coverage.
Don’t assume one location can simply be copied onto the other. Tell your insurer about both sites and make sure each one appears correctly on the policy. I’d also review property values and liability exposure separately, since a Las Vegas operation may have very different foot traffic or lease requirements from a Reno location. If employees or vehicles move between both, confirm the policy follows those operations too.
About Connor Bolton

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.
The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.
Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.
Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.