Best Business Insurance Companies For Tax Preparers

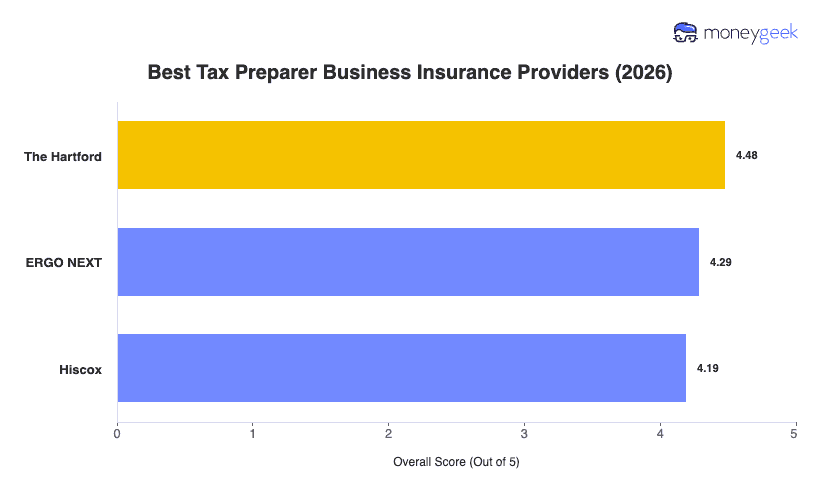
My analysis ranked these companies as the best small business insurers for tax preparers:

  • Choose if you want the best overall value and need coverage depth: The Hartford
  • Choose if you're a solo preparer and want a fully digital experience: ERGO NEXT
  • Choose if you run a small firm and prioritize professional liability terms: Hiscox

Tax preparers face a specific combination of professional liability and data security risk that most general business insurance comparisons don't account for. My rankings reflect that reality. I scored each provider across affordability (50%), customer experience (30%), and coverage options (20%), weighted that way because what you pay determines what you can sustain long-term, but how a provider handles your claim and whether the policy actually covers your exposure is what decides whether that premium was worth anything.

This is what made up my analysis of popular insurers, which was assisted (not run) by AI:

  • Affordability: I pulled quotes isolating pricing factors for tax preparation services across all 50 states plus D.C., employee count ranges from 0 to 49, and the six most common coverage types to build a complete pricing picture specific to this industry.
  • Customer Experience: Over 300,000 reviews, forum conversations and industry research were aggregated and manually parsed to identify the service patterns that matter most to small professional services firms. I also walked through the actual quoting and policy management experience for every provider analyzed.
  • Coverage Options: I read policy terms, documented available endorsements and exclusions, and evaluated how well each provider's professional liability and cyber offerings address the specific exposures tax preparers carry, including claims-made structure, retroactive dates and whether IRS representation work is covered or excluded.
The Hartford

The Hartford: Best Overall, Best For Complex Practices

On The Hartford's site
checkmarkpros
  • Most affordable insurer for tax preparers

  • Broadest professional liability coverage options

  • Dedicated agent assigned to your practice

closecons
  • No fully digital policy management

  • Most actions require calling your agent

  • No in-house commercial auto for small firms

COMPANY HIGHLIGHTS

The Hartford is my top pick for tax preparers because it combines the lowest average premium in our dataset with the widest coverage selection, a pairing that almost never shows up together. Professional liability policies come with flexible retroactive dates on claims-made coverage, which matters for tax work since a return you filed in April can generate a claim 18 months later. Their financial services team also understands the difference between a Preparer Tax Identification Number (PTIN)-only preparer and an Enrolled Agent (EA) practice handling IRS representation, so your policy terms actually reflect the work you do.

Where The Hartford falls short is the buying and management experience. Getting a quote means talking to an agent, policy changes go through that same agent, and there's no self-service portal for routine tasks like pulling a COI.  

Read Our Review: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best For Solo and Small Practices

On ERGO NEXT's site
checkmarkpros
  • Fastest quoting and binding in the field

  • Instant COIs on app and website

  • Ranked first in customer experience

closecons
  • Coverage options limited for complex practices

  • General support, not industry-specific agents

  • Higher premium than The Hartford for this industry

COMPANY HIGHLIGHTS

ERGO NEXT earns its spot in my rankings by making the entire insurance process as fast and painless as possible. I got a quote, purchased a policy and had a COI in hand in under six minutes during my testing, all without speaking to anyone. For a solo preparer or small practice that needs proof of coverage before a client engagement starts, that speed has real value. Their policy management is equally streamlined, with changes, cancellations and COI generation all handled through their app or website.

The tradeoff is depth. Professional liability options are more standardized and may not flex well for practices that handle business returns, IRS representation or complex multi-year engagements. If your coverage question goes beyond the basics, support routes to a general team rather than someone who understands tax preparer exposures specifically.

Read Our Review: ERGO NEXT Business Insurance Review

Hiscox

Hiscox: Best For Professional Liability Focus

checkmarkpros
  • Tailored E&O policies for professional services

  • Online quote and bind available

  • Monthly payment option with no extra fees

closecons
  • Limited coverage types beyond professional liability

  • Customer experience ranks below both competitors

COMPANY HIGHLIGHTS

Hiscox built its reputation on professional liability for service-based businesses, and that specialization shows in how their errors and omissions (E&O) policies are structured for tax preparers. Policy terms are written with professional services exposures in mind rather than adapted from a general small business template, which means fewer surprises when you read the fine print on what's covered and what isn't. Their online quoting process is clean and lets you bind coverage the same day without an agent call.

The limitation with Hiscox is scope. It's strong on professional liability but thinner on the supporting coverages a growing tax practice eventually needs. If you're looking to build a full coverage stack under one provider, you'll hit the ceiling faster than you would with The Hartford. Their customer experience also trails both competitors in my data, which is worth weighing if claims handling responsiveness matters to you.

Read Our Review: Hiscox Business Insurance Review

What Types of Insurance Do Tax Preparers Need?

The first policy any tax preparer should carry is professional liability insurance (also known as E&O), since every return you file is a signed professional judgment that a client can dispute when the IRS comes back with questions. Cyber insurance is the immediate second priority because your systems hold Social Security numbers, bank account details and income records for every client you serve, and the IRS requires all paid preparers to maintain a Written Information Security Plan (WISP) under federal law. These two coverages address what your work produces and what your systems store, which are the two exposures that exist regardless of how your practice is set up.

Beyond that foundation, your practice structure determines what else you need. The table below summarizes the most common types of business insurance that tax preparers need to cover financial risks and meet requirements.

Legal costs and settlements when a client claims your return preparation, tax advice or IRS representation caused them financial harm
Every tax preparer needs this before filing their first paid return

IRS penalties for preparer errors start at $250 per violation and can reach $50,000 per year for identity theft-related disclosures, and that's before a client files a lawsuit.

Breach notification costs, data recovery and legal liability after a cyberattack exposes client financial data

All tax preparers, since the IRS requires every paid preparer to maintain a WISP and you store concentrated volumes of sensitive data

Tax-related identity theft produced over $2.3 billion in fraudulent refunds in 2024, and compromised preparer credentials accounted for 34% of those incidents.
Claims and legal costs when a client or visitor is injured at your office or you damage someone else's property
If clients visit your office to drop off documents or review returns in person
A single slip-and-fall claim can produce medical and legal costs that exceed what most solo practices can absorb out of pocket.
Medical bills and lost wages for an employee injured on the job
When you hire employees, including part-time or seasonal preparers brought on for filing season
Most states require workers' comp coverage the moment you have one employee, and operating without it can result in fines and personal liability for injury costs.
Damage or loss to your office space, tax software workstations, servers and on-site client files
If you lease or own office space and store equipment or prior-year records on-site
A fire or break-in that destroys workstations and prior-year files creates both a replacement cost and an IRS recordkeeping compliance problem.
Injuries and vehicle or property damage after a work-related accident
If you drive to client locations to collect records or conduct year-end consultations
Personal auto policies exclude business use, so an accident on the way to a client meeting leaves you uninsured without a commercial policy.
Bundles general liability with commercial property coverage in a single policy
If you run a storefront or office-based practice and need both premises and property protection
A BOP typically costs less than buying general liability and commercial property separately, and simplifies management for small practices.
mglogo icon

WHY GETTING TAX PREPARER INSURANCE IS IMPORTANT

The math on tax preparer insurance is straightforward once you put actual claim costs next to annual premiums. Professional liability coverage for a solo preparer averages $54 per month, which works out to $652 per year. A single client dispute over a missed deduction or an incorrect filing status that leads to IRS penalties can easily generate $10,000 to $25,000 in legal defense and settlement costs. On the cyber side, the National Association of Enrolled Agents has documented how breaches and professional claims compound quickly for tax practices that handle sensitive financial data at scale during a compressed filing window. One claim in a 20-year career makes every year of premiums worth it.

How Much Does Tax Preparer Business Insurance Cost?

Tax preparer business insurance costs can range anywhere from $16 per month for commercial property up to $93 per month for cyber insurance for a typical small practice with 1 to 4 employees. Though this is only a baseline, your rates will vary depending on your credential level, the complexity of your client base, whether you offer IRS representation and how many returns you file per season.

Whether you hold a PTIN or an EA credential changes how insurers assess your professional liability risk. Practices that operate year-round rather than seasonally also price differently, since cyber and professional liability underwriters factor in how long your systems hold active client data. The number of preparers filing returns under your practice adds aggregate exposure that moves your limit floor and premium together.

Costs for commonly needed coverage types are as follows:

What Are These Costs Based On?

For a more specific estimate, use our business insurance calculator below. Once you have a good idea of what coverage may cost you, you can get matched to a provider by clicking Get Quotes.

Tax Preparer Insurance Cost Calculator

Select your state and industry to view average business insurance premiums in your area. Rates are calculated based on a business with 5 employees and $500,000 in annual revenue.

Select Coverage Type
Select Employee Count
Select Vehicle Type
Select State
Average Monthly Cost—

How To Buy The Best Tax Preparer Insurance

Use the how-to below to guide you through buying the best tax preparer insurance for your practice. You can also download a companion worksheet to help you organize all the information you get from quotes and insurers.

  1. 1

    Identify Required Coverages

    Start with the credential you hold. If your state registration or licensing board requires proof of coverage, document those minimums first. Then review the insurance section of any client engagement letters or contracts, especially if you serve business clients who may require specific limits or endorsements. If a business client asks you to add them as an additional insured, that request must go to your insurer as an endorsement to your policy. Simply providing a certificate of insurance (COI) proves you have coverage but does not extend it to them.

    Read More: Business Insurance Requirements

  2. 2

    Map Your Practice Risks to Coverage

    Walk through a typical client engagement and note where a loss could happen. Suppose a seasonal preparer you hired makes a filing status error on a return submitted under your PTIN. Your professional liability policy would need to respond, but only if it covers work performed by employees and not just your own. Apply the same logic to your data handling by asking whether your cyber policy covers a breach that originates from a phishing email opened by a staff member during tax season, not just an attack on your personal credentials.

  3. 3

    Set Appropriate Limits For Your Risk

    Size your limits against your worst realistic claim, not the policy minimum. For professional liability, think through the most complex client relationship you carry. If you prepare S-corp returns where a basis calculation error could surface a six-figure tax liability two years after filing, a $250,000 limit is not enough. For cyber, multiply your client count by the per-record notification cost of a breach to estimate the exposure a single incident would create.

    Read More: How Much Business Insurance Do I Need?

  4. 4

    Research Providers Specific To Your Practice

    Not every insurer writes professional liability that covers the full scope of tax preparation work. Some policies exclude IRS representation, and others limit coverage to return preparation only. Before requesting any quotes, confirm that a provider's professional liability terms cover the services you actually perform, that their claims-made retroactive date works for your practice history, and that their cyber policy accounts for the volume and sensitivity of financial data your systems store.

  5. 5

    Compare Pricing and Quotes

    Research what insurance costs for your specific credential level and practice size before getting quotes so you have a measuring stick. Then request quotes with identical coverage limits, deductibles and policy terms across providers to make them comparable. A lower premium means nothing if one quote carries a $5,000 deductible and the other carries $1,000, or if one excludes IRS representation work entirely.

  6. 6

    Review Your Policy Before Buying

    Read beyond the declarations page before binding. Confirm that the named insured matches your legal business name, that the retroactive date on your claims-made professional liability policy covers your full practice history, and that any client-required endorsements are actually attached. Check that your cyber policy's breach notification coverage aligns with the FTC Safeguards Rule's 30-day reporting requirement.

  7. 7

    Reassess Your Needs As Your Practice Changes

    Your coverage structure should evolve alongside your practice. Hiring your first seasonal preparer triggers workers' comp requirements in most states. Moving from individual filers to business clients shifts your professional liability limit floor. Upgrading from a home office to a storefront adds general liability and commercial property to your stack. And if you earn your EA credential and begin representing clients before the IRS, confirm your professional liability terms cover that expanded scope of work.

Tax Preparer Insurance: FAQ

I've answered the following frequently asked questions below, beyond what is covered in this guide, to ensure you have everything you need before buying tax preparer insurance.

Best Tax Preparer Business Insurance: The Bottom Line

You now know which providers fit your practice and what coverage your tax preparation work actually requires. When you start comparing quotes, remember that two policies at the same price can look very different behind the declarations page. One may cover IRS representation work while another excludes it. One may carry a retroactive date that protects your full practice history while another only covers claims from the current policy year forward. Those details don't surface until a client disputes a return you filed, and by then the policy is already bought.

The right coverage matches your credential level, reflects the complexity of your client base and comes from a carrier that will respond well when a claim arrives. Before you compare, these are my top picks overall for tax preparers.

Best Tax Preparer Business Insurance Chart

Get Tax Preparer Business Insurance Quotes

MoneyGeek can help connect you with tailored provider matches for your tax preparation business. You can then get quotes and compare coverage on your match's website in just minutes.

About Connor Bolton


Connor Bolton, Senior SEO and Content Manager (Business & Pet), MoneyGeek

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.

The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.

Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.

Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.


Sources