Best Business Insurance Companies For Safety Consultants

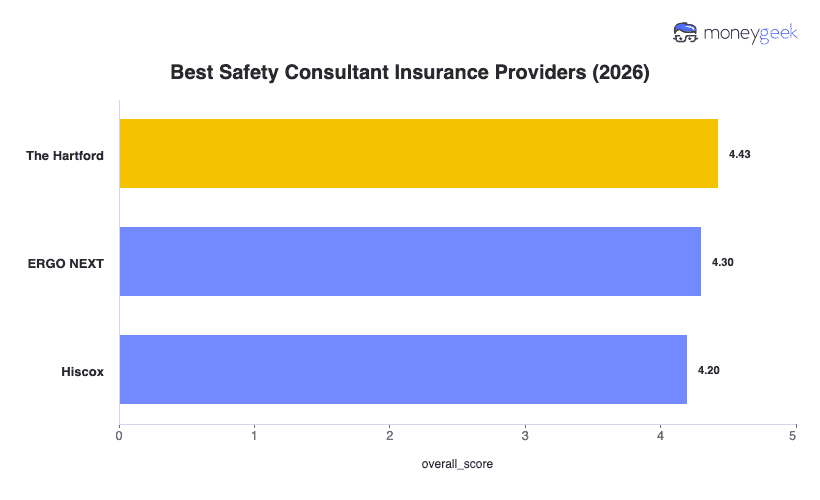
In my analysis, the best business insurance providers for safety consultants are:

  • Choose if you're a larger firm and want the best overall value: The Hartford
  • Choose if you work solo and prefer self-service policy management: ERGO NEXT
  • Choose if you want the broadest professional liability package available: Hiscox
Safety consultants can look similar on paper while having very different insurance needs. A solo consultant doing remote assessments has a different risk profile from a firm sending staff to industrial sites, so I weighted affordability (50%), customer experience (30%) and coverage options (20%) based on how useful each factor is when choosing a provider for this kind of work.

This is what shaped my analysis, with AI used to assist the research rather than make the final judgments:

  • Affordability: I compared how each provider priced safety consultants across different team sizes and coverage needs, with extra attention to whether a carrier stayed competitive beyond the solo-consultant stage.
  • Customer Experience: I looked at what happens before and after purchase, including how easy it is to get a quote, access policy documents and make routine changes when client requirements shift.
  • Coverage Options: I focused on professional liability first, then looked at whether the provider could support the other risks safety consultants may pick up through client-site work, employees or business vehicles.

See our full business insurance methodology.

The Hartford

The Hartford: Best for Larger Firms Looking for Overall Value

On The Hartford's site
checkmarkpros
  • Lowest rate in our provider study

  • Strong fit for growing consulting firms

  • Broad coverage across multiple business needs

  • Higher limits available for larger contracts

closecons
  • Expensive for solo safety consultants

  • Professional liability quotes may require a call

  • Some workforce-related claims face exclusions

  • Limited policy availability in some states

COMPANY HIGHLIGHTS

The Hartford tops my analysis of the best business insurance providers for safety consultants. At an average of $42 per month, it has the lowest rate in my study while still offering a broad range of coverage. I’d recommend it most for larger or growing firms that want to keep more of their insurance with one provider. As your business expands, you can add policies as new risks come up. A safety consulting firm that starts hiring employees, for example, could add workers’ comp without moving the rest of its coverage elsewhere.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Solo Consultants Who Want Self-Service Policy Management

On ERGO NEXT's site
checkmarkpros
  • Lowest rate in our study for solopreneurs

  • Fast online quote and purchase process

  • Unlimited COIs with self-service updates

closecons
  • Rates rise once you start adding employees

  • Standard professional liability limits may be restrictive

  • Less suited to consultants wanting agent-led service

COMPANY HIGHLIGHTS

If you manage your own insurance and regularly need to update certificates or policy details, I’d consider ERGO NEXT. It isn’t the cheapest provider overall, but it had the lowest rate in our study for solo safety consultants. That makes it relevant especially if you work independently and want to keep both costs and routine policy management straightforward. You can also get a quote and buy coverage in about 10 minutes. That helps when a new client needs proof of insurance before you can start work or access a site.

Learn More: ERGO NEXT Business Insurance Review

Hiscox

Hiscox: Best for the Broadest Professional Liability Package

checkmarkpros
  • Multi-national coverage available

  • Long service hours for customer support

  • Highly specialized professional liability coverage

closecons
  • Larger companies pay much higher rates

  • Workers' comp not offered directly

  • Online policy management is not available

COMPANY HIGHLIGHTS

I’d choose Hiscox if you take on larger safety consulting contracts or work with clients across borders. Its professional liability policy can cover earlier work through a retroactive date, which matters if a client raises a claim months after you've given your assessment or recommendation. Hiscox also offers higher liability limits for firms with stricter contract requirements. If you advise multinational clients or review safety practices at overseas operations, worldwide professional services coverage protects that work, subject to where the resulting claim is filed. 

Learn More: Hiscox Business Insurance Review

What Types of Insurance Do Safety Consultants Need?

Your insurance bundle should, at minimum, include professional liability and general liability. PL claims commonly involve alleged service or delivery failures, including advice-based work. For safety consultants, that’s directly connected to your assessments and recommendations. General liability addresses risks from the physical side of your job. For example, you can damage something while moving through an active worksite or cause an accident while setting up for a client session.

After that, additional coverages depend on how your business operates and the risks you take on as your business changes.

Client claims tied to your safety advice, assessments or professional services
All safety consultants should carry it

Aon found consulting PL claims are rising and becoming more varied. For safety consultants, disputes often involve hazard assessments or compliance advice.

Injuries to other people and damage to property caused by your business
Before you begin working at client sites or meeting clients in person

You could accidentally damage client property during a site inspection or have an injury claim if someone is hurt during a training session or walkthrough.

Medical costs and lost wages after an employee’s work-related injury or illness
When you hire employees

Your staff enter client worksites with hazards they can't control. The broader professional, scientific and technical services sector reported 71,600 workplace injuries and illnesses in 2024.

Liability and vehicle damage from accidents involving business-owned vehicles
A vehicle is titled to the business or used primarily for work

Frequent travel between client facilities increases your exposure to crashes while driving for inspections or other consulting work.

Damage to business equipment, furniture and other property from covered events
When you invest in more expensive equipment or have an office.
Replacing laptops or inspection equipment becomes expensive if they’re stolen or damaged by a covered event.
Costs tied to data breaches, cyberattacks and certain resulting claims
You store client records or other sensitive information electronically

Consulting firms often hold sensitive client data and assessment records. Professional Services & Consulting accounted for 15.82% of ransomware attacks in Aon’s 2024 dataset, making it the second-most targeted sector.

scale icon

WHY GETTING SAFETY CONSULTANT INSURANCE IS IMPORTANT

Safety consultants often work inside environments they don’t control. You might identify a hazard and recommend a fix, but the client decides what gets implemented. If an incident happens later, your assessment can still become part of the claim even when the final decision wasn’t yours.

Insurance also helps when client work comes with its own requirements. A manufacturer or construction firm may expect certain limits before allowing you onsite. Carrying coverage that matches the work you take on helps you protect the business without automatically paying for more insurance than you need.

How Much Does Safety Consultant Business Insurance Cost?

The cost of consulting insurance for safety consultants range from $21 per month for workers' comp to $107 for cyber liability. I used a base profile of a firm with one to four employees to get these estimates, so your quote will be different if you work solo or have a larger, more established practice. How much on-site work you do, and the kind of industries you serve, also affect your costs.

Costs by coverage type are as follows for safety consulting operations:

What Are These Costs Based On?

Our business insurance calculator can give you an estimate based on your profile. Then you can click Get Quotes to get matched to an insurer that best matches your coverage needs.

Safety Consultant Insurance Cost Calculator
Select Coverage Type
Select State
Select Employee Count
Select Vehicle Type
Average Monthly Cost—

How To Buy The Best Safety Consultant Insurance

It's easier to find the best safety consultant insurance when you know work through the decisions in order. I’ve broken the process into seven steps below, with a downloadable companion checklist you can use as you compare options.

  1. 1
    Identify Required Coverage

    Some coverages are legally or contractually required. Workers’ comp is an example. If you have employees, state law mandates it, though the threshold varies between states. You’ll also need a commercial auto policy that meets state minimums for any business-owned vehicles. Then check client contracts for general liability requirements, including required limits and certificates of insurance (COIs). I suggest confirming whether you need additional insured endorsements and those requirements before comparing providers so you know the minimum coverage you need to work.

    Read More: Business Insurance Requirements

  2. 2
    Map Business Risks to Coverage Types

    The biggest risk in consulting is that a client says your advice or professional work caused them to lose money. You’ll need professional liability since your work often involves making an assessment, making recommendations or giving guidance on compliance. From there, look at the other risks that come with your profession. That could include storing sensitive client records, which points to cyber coverage. If you’re using inspection equipment that’ll be expensive to repair or replace, consider including commercial property in your bundle.

  3. 3
    Set Appropriate Limits for Your Risk

    You don’t have to automatically get the highest policy limits available, but sometimes, minimum isn’t enough either. Go back to your contracts and see if there are any limit requirements. If there is, use that as a starting point. But you also have to decide whether those amounts are enough for the work you take on. 

    For professional liability specifically, $1 million per claim is usually enough for most safety consultants, but I’d consider raising your limits when your advice affects higher-value operations or larger client contracts. Advising a small office on basic safety procedures carries a different exposure than reviewing hazards for a large industrial facility.

    Read More: How Much Business Insurance Do I Need?

  4. 4
    Research Providers Before Quoting

    You can learn a lot about a provider during the buying process. Don’t automatically dismiss a longer application. Questions about the services you provide or the contracts you take on give the insurer more information to underwrite your business. Check if you can see important policy details before buying. If exclusions or next steps stay unclear until late in the process, I’d be more cautious. You might discover a coverage gap or extra requirement late in the buying process, when switching providers means starting over.

    Finally, consider how much control you’re given. If you prefer handling insurance yourself, strong online tools for accessing policy documents or  requesting changes matter more. If you want guidance, check how easily you can reach an agent before and after purchase.

  5. 5
    Compare Quotes Apples to Apples

    Once you have a shortlist of insurers, compare business insurance quotes using the same limits and deductibles before looking at price. For professional liability, check whether the retroactive date and any contract-required endorsements match. A cheaper quote looks attractive until you realize it carries a lower limit or leaves out coverage another insurer included. That’ll matter to your safety consulting work if a client requires specific limits before work starts.

  6. 6
    Review Your Policy Before Buying

    Before you bind coverage, read the policy itself instead of relying on the quote summary. For professional liability, check that the listed services match the safety consulting work you actually perform. If your policy description leaves out work such as inspections or compliance advice, ask the insurer to correct or confirm it before you buy.

    Another thing worth a closer look are exclusions and any endorsements your contracts require. If your PL policy is claims-made, confirm the retroactive date so you know how far back prior work can be covered. Once all of these are in place, make sure coverage starts before your next engagement begins.

  7. 7
    Reassess Your Needs as Your Company Changes

    You don’t have to wait until renewal to revisit your policy. Review your coverage whenever the way you operate changes, such as if you add employees or take on larger contracts. The same applies when you scale back.

    If you stop using a business vehicle or move away from higher-risk client work, you might be paying for coverage you no longer need. But before cutting anything, check current contracts and legal requirements to make sure you remain eligible for the work you still do. When renewal does come, use your current operations as the baseline instead of automatically carrying last year’s coverage forward.

Safety Consultant Insurance: FAQ

Some insurance questions only come up once you start working with clients or handling more complex engagements. These questions address situations I haven’t talked about so far in this article.

Best Safety Consultant Business Insurance: Bottom Line

Start with the risks your safety consulting work creates, then build your insurance around them. For most safety consultants, that means professional liability and general liability first, with other policies added only when your operations justify them. Cost matters, but I wouldn’t use price alone to choose coverage or a provider.

Among the insurers I reviewed, The Hartford, ERGO NEXT and Hiscox top my analysis but each stands out for different reasons. Compare them based on how well their coverage, service model and policy features match the way you work, then make sure your limits satisfy any client requirements before you buy.

Best Safety Consultant Insurance Chart

Get Safety Consultant Business Insurance Quotes

Match your policies and limits to how you actually work, then compare quotes based on that profile rather than buying a broader package by default.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com